Powell Industries Crushes Q4 Estimates As Growth Accelerates And Backlog Hits $2.7 Billion, But A Falling Stock Shows The Market Already Doubted The Story
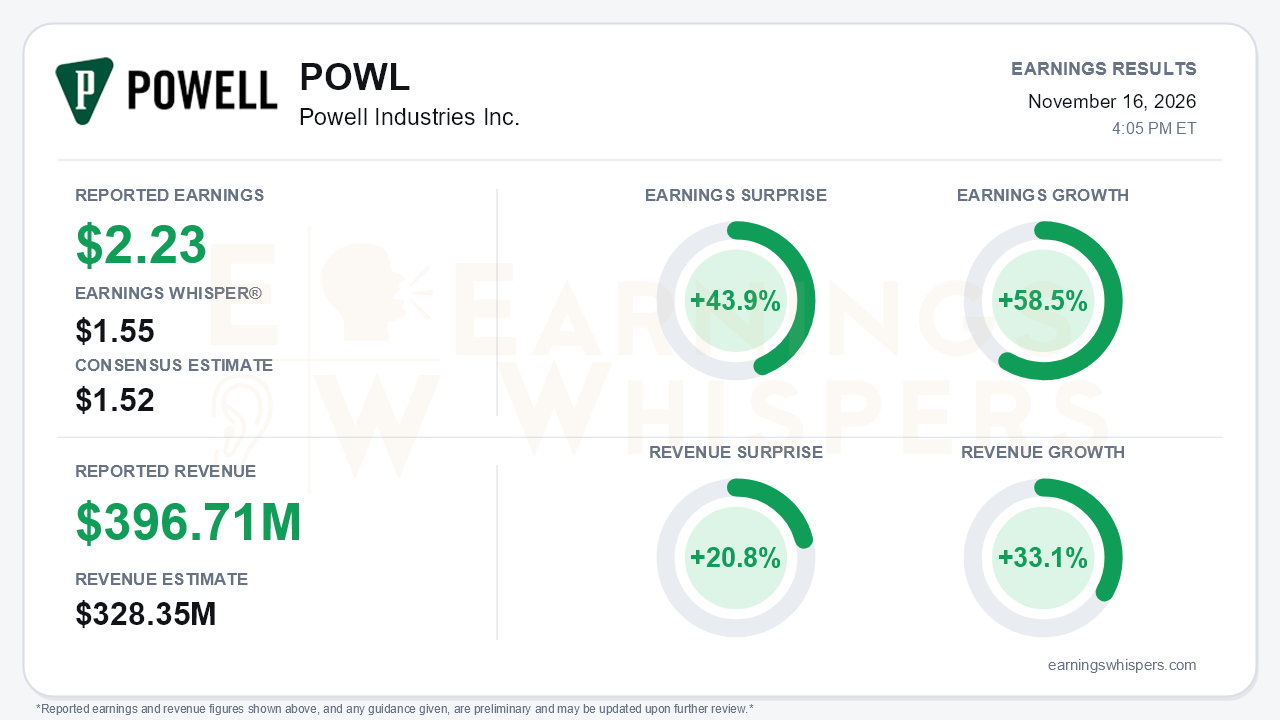
Powell Industries delivered the strongest quarter of its fiscal year, and it was not close. The electrical equipment maker earned $2.23 per share in its fiscal fourth quarter, well ahead of the $1.52 consensus and the $1.55 Earnings Whisper number, a 43.9% surprise. Revenue of $396.71 million topped expectations by 20.8%. Earnings grew 58.5% year over year and revenue rose 33.1%. The central takeaway is acceleration. Revenue growth had been modest through most of fiscal 2026, at 4% in Q1, 6% in Q2 and 9% in Q3, before jumping to 33% as backlog built over the past year began to convert. Sequentially, revenue climbed 27% from $312 million, and EPS rose from $1.42.
The quality of the beat deserves scrutiny, though most of it holds up. Gross margin reached 34.9%, the end of a steady climb from 28.4% in Q1, 29.6% in Q2 and 30.6% in Q3. Roughly 230 basis points of the Q4 figure came from project closeouts, which management treats as a one-time-type tailwind. Stripping that out still leaves a margin in the low 30s. Management said the underlying base margin for the full year was about 30%, compared with about 28% in fiscal 2025. That points to a structurally higher floor rather than a single flattered quarter. Operating income rose to $100.6 million from $63.2 million despite SG&A that included non-recurring legal and professional costs. Cash generation was the quiet standout. Q4 operating cash flow was $239 million and full-year operating cash flow was $434 million, up from $168 million. That lifted cash and short-term investments to $861 million with no debt.
Demand remains the backbone of the story. Q4 orders of $710 million rose 162% year over year for a 1.8x book-to-bill. The quarter included a roughly $250 million LNG award and an $85 million data center order. Full-year orders reached a record $2.6 billion, a 2.0x book-to-bill, and backlog rose every quarter, from $1.6 billion to $2.7 billion. The mix is also shifting. Electric utility and commercial/other industrial work made up 50% of revenue, up from 41% in fiscal 2025, which reduces Powell's historical dependence on oil and gas cycles. Management expects the fiscal 2026 margin profile to be sustainable in fiscal 2027, aside from a seasonally slower first quarter. It also pointed to a rising book-and-ship run rate of $75-80 million per quarter, configure-to-order data center lines and early signs of recovery in petrochemicals.
Bears have legitimate ammunition, but it concerns timing more than demand:
- Q4 orders fell from Q3's record $934 million.
- The share of backlog expected to convert within 12 months slipped to about 50%, from 54% in Q3 and about 60% a year earlier. A bigger backlog is converting more slowly, and revenue will stretch over longer project durations.
- International revenue fell 29% on weaker Canada, petrochemical revenue dropped 49% and traction power fell 24%.
- Management raised skilled craft labor as a fiscal 2027-28 watch item.
- Data center configure-to-order contracts carry higher cancellation and scope-change risk, and some reallocations have already occurred.
- Management acknowledged uncertainty around data center spending following the midterm elections.
- Capacity expansion adds its own execution risk. A new 275,000 sq ft lease comes online in fiscal Q3 2027 and Jacinto Port is adding another 80,000 sq ft. Management warned of a possible productivity air pocket and $15-20 million of incremental capex.
The market setup is more complicated than the surprise implies. Shares stood at $151.20 at the time of the report, down 21.1% from the $191.71 open after the August release and about 29% below the 200-day moving average of $213.04. Investor sentiment swung from modestly positive (0.13) to modestly negative (-0.17), a meaningful shift in tone even though neither reading is extreme. The Earnings Whispers price and AVWAP trend readings are both negative, consistent with a stock that has been sold steadily despite a record order book. Investors appear to have been pricing in peak-cycle risk, data center skepticism and slower backlog conversion rather than near-term earnings weakness.
That disconnect is the central tension. The quarter answered the near-term earnings question decisively: growth accelerated, margins expanded and cash piled up. It did not fully resolve the duration questions behind the stock's slide, including whether longer-dated backlog, data center order durability and labor-constrained capacity can sustain this pace through fiscal 2028.
The bottom line is that Powell posted a decisive beat built on real volume leverage, a higher underlying margin base and record backlog. A shrinking conversion ratio, closeout-aided Q4 margins and data center and labor risks give skeptics something to hold onto. With shares well below their long-term average and sentiment turned negative heading into the print, fundamentals have moved well ahead of how the market has been treating the stock.
Read our earnings preview for Powell Industries Inc.: https://www.earningswhispers.com/article/POWL/23072
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-09 | |
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Oct-07 | |
| Sep-11 | |
| Sep-03 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 |
