MINISO Misses As China Strength Can't Offset An Overseas Stall, A TOP TOY Reversal And Rising Store Costs
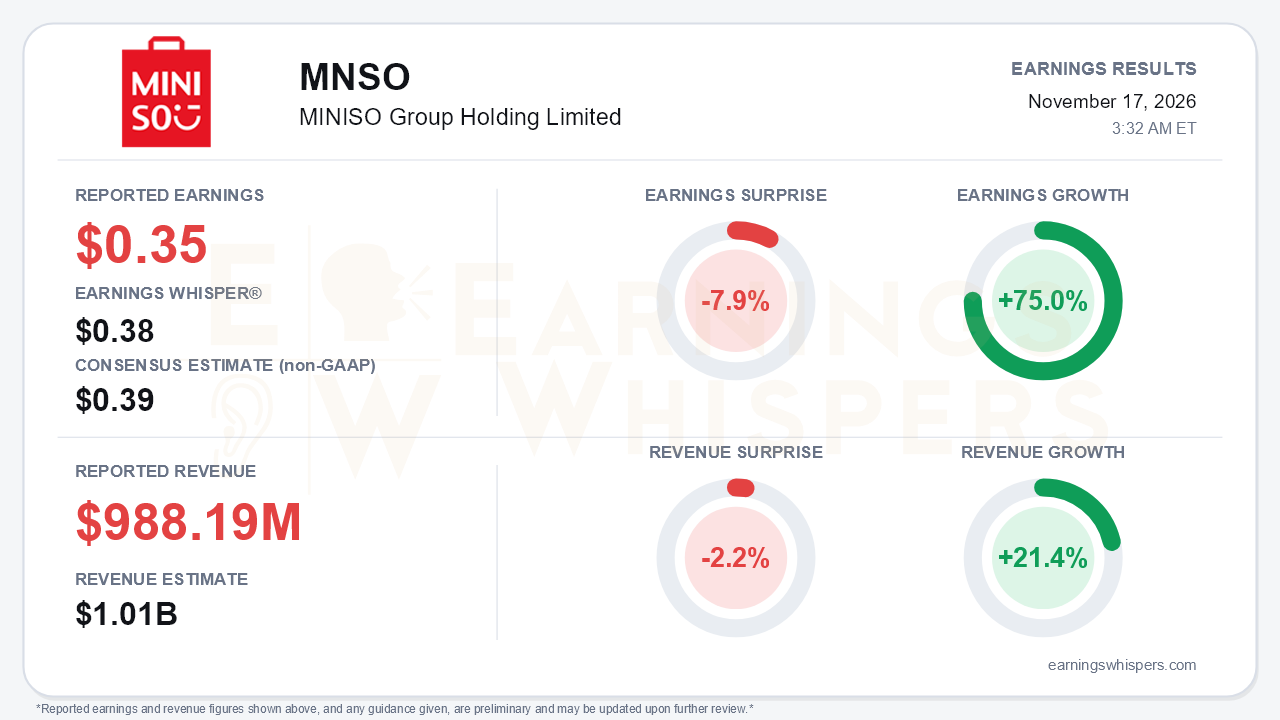
MINISO Group missed expectations for its September quarter, and the miss reflects a real slowdown rather than a rounding error. The company reported earnings of $0.35 per share, short of the $0.39 consensus and the $0.38 Earnings Whisper number, a 7.9% shortfall. Revenue of $988.19 million also trailed the $1.01 billion consensus by 2.2%. On Earnings Whispers' dollar-based comparison, earnings grew 75.0% and revenue grew 21.4% year over year. In the company's reporting currency, the picture is softer: RMB revenue rose 14.3%, and adjusted diluted earnings per ADS slipped to RMB2.36 from RMB2.44. That gap matters. The central tension is that MINISO's domestic business is accelerating while nearly everything around it is decelerating, and costs are rising faster than sales.
The quality of the quarter deserves scrutiny. Gross margin improved to 45.3% from 44.7%, helped by pricing and a richer mix of proprietary and designer IP. That gain was overwhelmed below the gross line. Selling and distribution expenses excluding share-based compensation rose 28.8%, lifting their share of revenue to 25.9% from 23.0%. The drivers were rent and depreciation tied to the directly operated store build-out, IP licensing, overseas payroll and advertising. As a result, adjusted operating margin excluding FX fell to 15.1% from 17.7%, and adjusted operating profit on that basis declined 2.5%. GAAP results were noisier still. A RMB192.1 million mark-to-market loss on an AI-focused limited partnership and a RMB155.1 million derivative loss tied to the equity-linked securities pushed IFRS profit down to RMB290.6 million from RMB443.2 million. Those items are non-cash, but they add volatility that a retailer's earnings line does not usually carry.
Beneath the headline, the business is splitting in two. MINISO's Chinese mainland revenue rose 29.6%, up from 26.2% in the first half. Same-store sales were mid-single-digit for nine months and above 10% in September, marking the sixth consecutive positive quarter. Management now expects to beat its low-single-digit full-year same-store target. Members drive roughly 80% of China sales, and proprietary IP Yoyo passed RMB1 billion in sales. Elsewhere the trend is clearly worse:
- Group revenue growth has slid from 28.5% in Q1 to 22.4% in the first half and 14.3% in Q3.
- Overseas revenue rose just 1.7%, against 22% in Q1.
- Asia ex-China GMV grew only 1.3% over nine months, and the region lost 65 stores year to date.
- Latin America revenue fell more than 10% as distributors destocked.
- TOP TOY revenue dropped 12.5% after growing 51% in Q1.
The call did not cut anything further, but that is partly because the cuts already happened in August. Full-year revenue guidance remains double-digit, with the second half at high-single-digit. Adjusted operating profit is still guided down high-single-digit, with a 3-4 point margin decline. Since nine-month adjusted operating profit excluding FX is up 2.0%, that guide implies a weak fourth quarter. Store-addition plans have shrunk steadily, and inventory days rose to 105 from 98, with overseas inventory near 271 days.
There are credible catalysts. The first US MINISO LAND generated about $1.15 million in roughly a month, and larger formats are planned for Las Vegas and New York. US September orders rose more than 50%, and North America revenue grew about 29% over nine months. Management expects large-format stores to exceed 30% of the China mix in 2027 and China growth of at least 10% annually through 2028. Capital returns are substantial: buybacks topped RMB1 billion year to date, about 4.5% of shares, supported by RMB1.21 billion of nine-month free cash flow. Bears have legitimate ammunition, however. Those big stores carry the rent and depreciation now squeezing margins, and they will enter the same-store comparison base in 2027.
Investors were not positioned optimistically going in. Sentiment stood at a modestly negative -0.15 after the August report. Shares opened at $10.43 after that release, well beneath a 200-day moving average that sits at $13.18, so the stock had already absorbed the guidance reset. Earnings Whispers trend readings are mixed: sequential growth and AVWAP are positive, while momentum remains negative.
The bottom line is that MINISO is executing well in China and showing early traction in the US, but this quarter confirmed that those engines are not yet large enough to offset stalling overseas distribution, a TOP TOY reversal and a costlier store model. Until selling-expense growth converges with revenue growth, the miss looks more like a symptom of the margin problem than an anomaly.
Read our earnings preview for MINISO Group Holding Limited: https://www.earningswhispers.com/article/MNSO/23103
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Nov-17 | |
| Nov-17 | |
| Nov-10 | |
| Nov-03 | |
| Oct-22 | |
| Oct-09 | |
| Sep-29 | |
| Aug-31 | |
| Aug-28 | |
| Aug-28 | |
| Aug-14 | |
| Jun-29 | |
| Jun-18 | |
| May-26 |
