Auna Misses Badly On EPS And Cuts EBITDA Outlook As Colombia Losses Overshadow Mexico's Turn
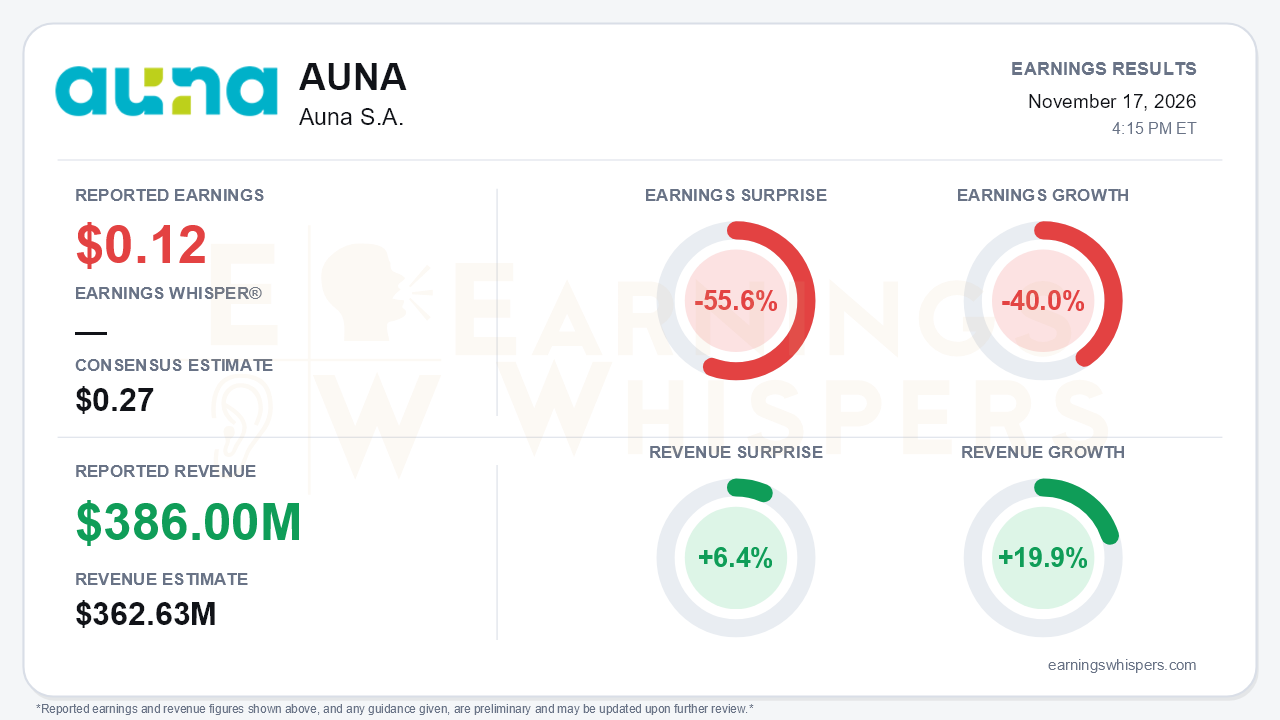
Auna's third quarter delivered a sharp split between top-line strength and bottom-line erosion. Earnings of $0.12 per share missed the $0.27 consensus by 55.6% and fell 40.0% from a year ago. Revenue of $386.0 million beat the $362.63 million consensus by 6.4% and grew 19.9% year over year. That gap is the central tension. Demand is not the problem. Converting that demand into profit is, and management responded by cutting its full-year Adjusted EBITDA outlook for the second consecutive quarter.
The quality of the quarter deserves scrutiny in both directions. On an IFRS basis, net income fell to S/24 million from S/53 million. Much of that decline reflects the absence of a S/40 million non-cash FX gain booked in the prior-year period, partly offset by S/20 million of lower tax expense. Adjusted net income of S/35 million, or S/0.41 per share, still fell from S/58 million. The FX comparison flatters the decline, but the operating picture is genuinely weaker. Adjusted EBITDA was flat as reported at S/231 million and fell 4.6% FX-neutral. The Adjusted EBITDA margin slipped to 17.5% from 18.4% in the second quarter. Reported revenue growth of 19% also leaned heavily on a 20% appreciation of the Colombian peso against the sol. FX-neutral growth was a steadier 10%, roughly in line with the 9% and 10% posted in the prior two quarters.
Beneath the consolidated figures, the three markets are moving in different directions.
- **Mexico** was the bright spot. Segment Adjusted EBITDA rose 5% in local currency after falling 16% in the second quarter. Monterrey network EBITDA climbed 10%, chemotherapy and radiotherapy sessions jumped 34%, and capacity utilization reached 41%.
- **Colombia** was the problem. Revenue grew 12% in local currency, but segment EBITDA collapsed 30%. Management attributed roughly 70% of the hit to an oncology risk-sharing contract where advanced-stage cancer incidence far exceeded assumptions. The other roughly 30% came from regulatory price caps on high-cost oncology drugs. In the second quarter, management had expected Colombian margins to improve in the second half. That expectation reversed.
- **Peru** grew revenue 6% and surgeries 21%, yet EBITDA fell 6%. The drivers were S/18 million in penalties tied to reconciling prior-year receivables, plus higher pharmacy, payroll and B2B onboarding costs.
The guidance trajectory tells the story most clearly. Full-year Adjusted EBITDA was originally framed around roughly 12% growth. In the second quarter it moved to the low end of 10-14% excluding Peru penalties. It is now expected to be broadly stable or slightly down. FX-neutral revenue guidance of 10-14% was reaffirmed and capex guidance was unchanged.
Bears have legitimate ammunition. The Colombian price caps took effect in mid-August and will weigh on the full fourth quarter. The Peru penalty cleanup has been pushed to the second half of 2027, versus a prior expectation of resolution during 2026. Mexico's VAT deductibility change continues to pressure Auna Seguros. Management also flagged a possible strong El Niño affecting northern Peru. Its tone shifted noticeably, from "back on track" earlier in the year to "a very tough quarter," with Colombia described as "concerning" and repeated "dirty quarters" acknowledged. That candor matters because recurring extraordinary items undermine earnings predictability.
The offsets are real, though. Year-to-date operating cash flow rose 62% to S/713 million and free cash flow climbed 95% to S/626 million. Cash reached S/614 million, the cash conversion cycle improved to -15 days, and leverage fell to 3.5x from 3.6x in the second quarter and 3.7x in the first. That moves the company closer to its sub-3.0x target. The loss-making Colombian contract, about 4% of segment revenue, has been terminated and legal recovery options are under review. Upcoming catalysts include:
- the Trecca ambulatory center PPP, which is under construction;
- two OncoSalud corporate agreements adding about 4,000 members in the fourth quarter;
- a possible SOGITS partnership in early 2027.
Investor sentiment remained negative but improved meaningfully, rising from -0.41 to -0.21 ahead of the report. That suggests expectations had already been reset lower after the second quarter. The stock has gone essentially nowhere, trading at $4.77, just 2.8% above the opening price following the prior report. Shares sit about 6.3% below the 200-day moving average of $5.09. Earnings Whispers price and AVWAP trend readings remain negative, consistent with a market that has not been rewarding the cash-flow story.
The bottom line is that Auna's revenue engine and cash generation remain intact, and Mexico has finally inflected. However, a third straight downgrade to the EBITDA outlook, a deep EPS miss and a widening list of country-specific setbacks make profitability the issue investors must underwrite. Improving sentiment shows some of this was anticipated. To change the narrative, though, the company needs to prove that Colombia's damage is contained, Peru's penalties have an end date and earnings can finally track the top line.
Read our earnings preview for Auna S.A.: https://www.earningswhispers.com/article/AUNA/23111
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Nov-17 | |
| Nov-10 | |
| Oct-22 | |
| Oct-22 | |
| Oct-13 | |
| Sep-16 | |
| Aug-19 | |
| Aug-18 | |
| Jul-20 | |
| May-20 | |
| May-19 | |
| Apr-22 | |
| Apr-17 | |
| Apr-15 |
