Kornit Digital Beats On Profit And Recurring Revenue, But Slowing AIC Growth And A Held Outlook Temper The Quarter
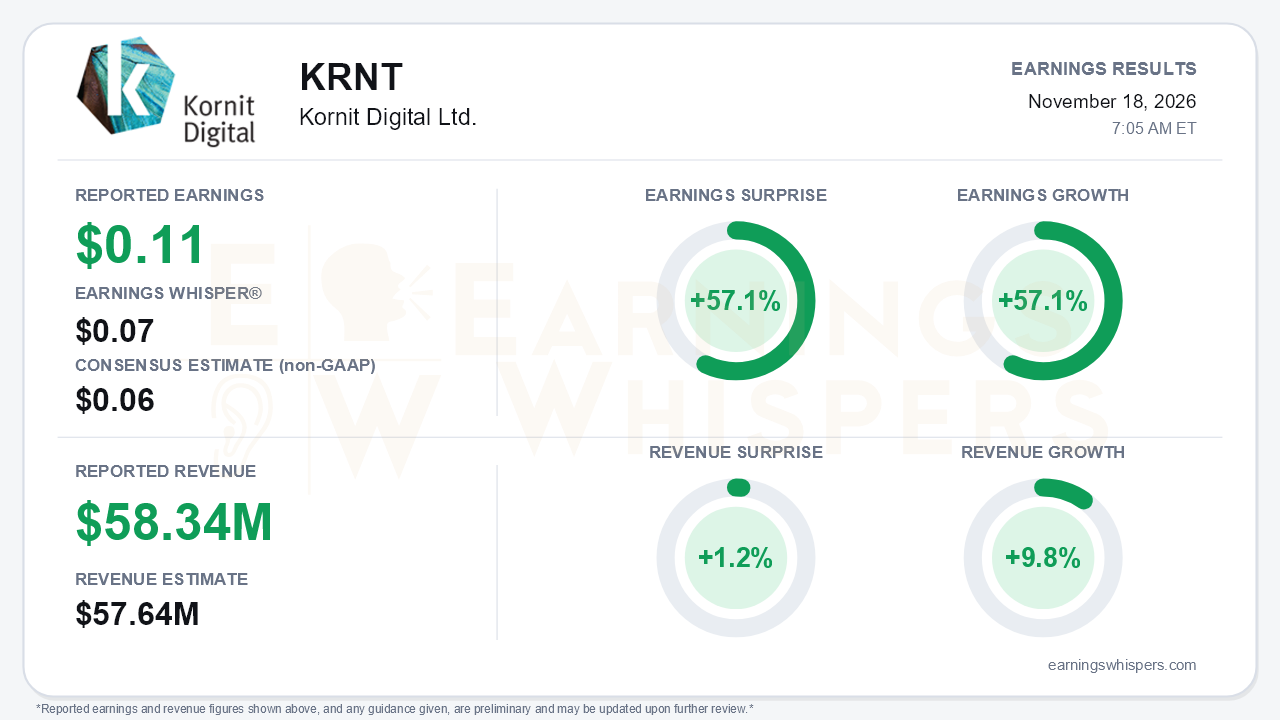
Kornit Digital delivered a clear bottom-line beat in the third quarter, but the details show a company trading near-term momentum for recurring revenue. Non-GAAP earnings of $0.11 per share topped the $0.06 consensus and the $0.07 Earnings Whisper number by 57.1%. Earnings Whispers puts year-over-year earnings growth at 57.1%. The company's own reconciliation shows non-GAAP EPS of $0.11 versus $0.09 a year ago. Revenue of $58.34 million beat consensus by 1.2%, rose 9.8%, and landed near the top of the $55-$60 million guide. On a GAAP basis, the net loss narrowed to $0.4 million, or $0.01 per share, from $2.6 million, or $0.06. The central tension is this: profitability and ARR kept improving, while the growth rates behind the AIC subscription story cooled and the outlook was held rather than raised.
The profit beat came mostly from cost control, not gross margin. Non-GAAP gross margin was 45.8%, flat year over year and below Q2's 47.4%, which had benefited from a tariff refund. Roughly 70 basis points of FX pressure also weighed on margin. Non-GAAP operating expenses fell sequentially to $27.3 million from $28.8 million. As a result, adjusted EBITDA reached $2.7 million, a 4.6% margin, above the 0-3% guide. That margin is up 260 basis points year over year and continues a progression from -5.8% in Q1 and 0.6% in Q2. Services revenue rose 22%, while product revenue grew only about 5%, consistent with a mix shift toward AIC.
Cash generation was weaker. Operating cash flow fell to $0.5 million from $8.5 million in Q2, or about $4.5 million excluding a $4 million legal payment. Inventory, capital spending on AIC systems and $15 million of buybacks drew cash and investments down to roughly $428 million from about $451 million.
The call explained the trade-off. AIC accounted for about 70% of systems shipped, up from roughly half in Q2 and about 40% a year ago. That accelerates recurring revenue but defers upfront product revenue. ARR climbed 83% to $39.4 million, and AIC total contract value rose 70% to $162.4 million. The growth rates, however, are decelerating:
- **AIC revenue:** up 70% year over year, versus 112% in Q2 and 103-104% in the prior two quarters.
- **ARR additions:** net new ARR slowed to $5.6 million from $7 million.
- **Impressions:** full-year growth is now framed at about 10%, versus 15% trailing growth cited in Q2.
Bears have legitimate ammunition here, even if the absolute numbers remain strong.
The strategic thesis, displacing screen printing, looks intact and perhaps strengthening. Screen printers took about 60% of year-to-date system deliveries, and long-run jobs drove 84% of impression growth. Kornit's roughly 250 million impressions compare with an estimated 20 billion screen impressions, implying under 1% penetration. New and expanding wins include:
- **Antler:** a Sri Lankan supplier to Nike and Victoria's Secret, which signed four Atlas Matrix systems and plans to add Apollos.
- **Fast Life Brands and Real Thread:** both added second systems within months.
- **KDS:** deployed the full Apollo, Atlas Max, Print Factory and Kornit X stack.
Management cited sales cycles sometimes under a month for screen printers under AIC, along with full holiday order books. It also volunteered early confidence in 2027, pointing to:
- a recurring revenue base of about 80%;
- ARR carry-in and planned upgrades;
- new product introductions;
- the Connections event in May and ITMA in September.
On the risk side, some AIC customers are running below their minimum commitments, though management said all are paying on time. Shekel and FX headwinds cost about $1.2 million of EBITDA year over year.
Guidance is where the enthusiasm stalls. The Q4 outlook calls for revenue of $60-$65 million and an adjusted EBITDA margin of 6.5-9.0%. The midpoint implies only about 6% growth, and the margin range sits below last year's 9.3%. The reaffirmed framework of second-half revenue about 15% above the first half implies roughly $61 million, in the lower half of the range. Full-year "high single-digit" growth was reaffirmed, not raised.
Investor expectations had reset meaningfully lower into the report, then recovered. Earnings Whispers sentiment improved from -0.27 to roughly neutral at +0.03. Shares closed at $16.56 the day before the report, down 12.8% since opening at $19.00 after the August release. The stock is 14.4% below its inter-earnings high of $19.35, set that same day. It has rebounded 12.6% from the September 24 low of $14.71 and sits just 3.7% above its 200-day moving average of $15.98. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while AVWAP remains negative. That fits a stock that has stabilized but not reclaimed its post-August levels.
The bottom line is that Kornit executed well on profitability and kept building a larger, stickier recurring base, with the screen-printer conversion story gaining credible customer evidence. But the deceleration in AIC growth, slower ARR additions, a softer impression outlook, weaker cash flow and an unraised, modest Q4 guide mean the beat does not settle the debate. The model shift is real. Investors now need to see whether ARR growth translates into reaccelerating revenue in 2027, as management is signaling, rather than simply cushioning near-term product softness.
Read our earnings preview for Kornit Digital Ltd.: https://www.earningswhispers.com/article/KRNT/23126
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 9 hours | |
| 9 hours | |
| Nov-10 | |
| Nov-03 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Jul-29 | |
| May-20 | |
| May-13 | |
| May-13 | |
| May-13 | |
| May-13 | |
| Apr-29 |
