BellRing Beats On Promotion-Driven Volume As New CEO Trades Sales Growth For Margin Repair
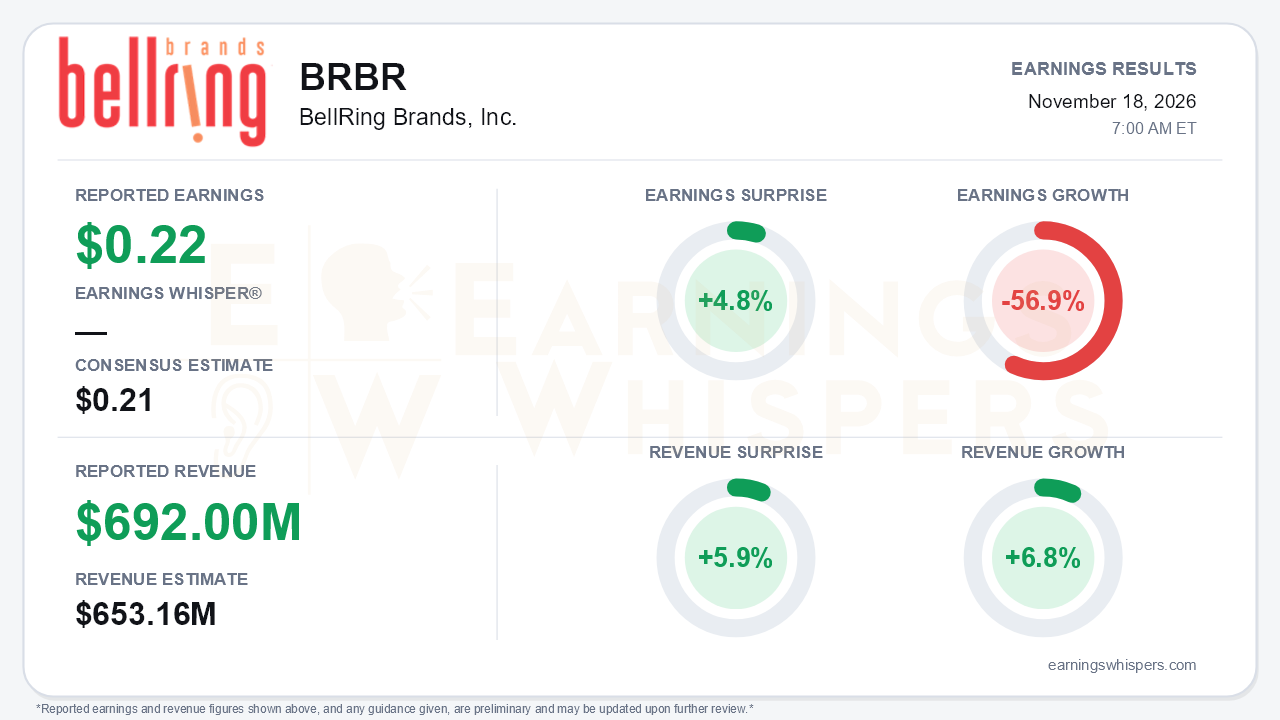
BellRing Brands (NYSE: BRBR) cleared a low bar in its fiscal fourth quarter. Adjusted EPS of $0.22 beat the $0.21 consensus by 4.8%, and revenue of $692.0 million topped the $653.16 million estimate by 5.9%. Revenue growth of 6.8% was a clear step up from the 3.5% pace for the full fiscal year. Earnings, however, fell 56.9% from a year ago. That is the central tension. The quarter's growth was bought with price, and it came at the expense of profitability. The more important news was strategic: new CEO Michael Axelrod is pivoting from chasing volume to rebuilding margins, even if that means shrinking the top line in fiscal 2027.
The quality of the beat deserves scrutiny. Volume jumped 14.9%, but price/mix fell 8.1%. For Premier Protein ready-to-drink shakes, volume rose 16.5% against an 8.6% price/mix decline, which the company attributed to incremental promotional investment. Adjusted gross margin collapsed to 20.1% from 29.7%. Adjusted EBITDA nearly halved to $66.4 million, and EBITDA margin fell to 9.6% from 18.1%. About $16 million of inventory-related charges cost 230 basis points of gross margin. Roughly half was slow-moving inventory reserves and half was trade spend to clear excess shake bottle inventory. Even excluding those charges, margins were far below last year because of tariff-inclusive input inflation, heavier trade spending and higher freight. GAAP EPS of $0.31 actually exceeded the adjusted figure because of a $13.4 million mark-to-market hedge gain, so the GAAP number flatters the quarter. Full-year adjusted EPS fell to $1.04 from $2.17. Operating cash flow dropped to $126.0 million from $260.6 million, and year-end cash was only $20.1 million against roughly $1.05 billion of long-term debt.
The call made clear that fiscal 2027 reverses the playbook. Management is taking a low double-digit price increase on shakes plus additional powder pricing in the first quarter. It assumes price elasticity greater than 1 in every scenario, which means volumes are expected to fall by more than prices rise. Net sales are guided to $2.32-$2.42 billion, or +1% to -3%. Management characterized this as the first expected annual decline, with shipments trailing consumption by a mid-single-digit margin as retailers adjust inventory. Adjusted EBITDA is guided to $310-$350 million, roughly a 14% margin versus about 12% in fiscal 2026. Management expects nearly 400 basis points of gross margin expansion from three sources:
- the pricing actions;
- about $25 million of first-year savings from a new supply chain program targeting at least $100 million over three years;
- lapping this year's inventory charges.
Advertising will rise by about 100 basis points as a percentage of sales.
There were genuine positives. Premier shake consumption rose about 9% in the fourth quarter, ahead of the mid-single-digit expectation. Club consumption turned slightly positive. A club pallet item that management had flagged on the prior call as rotating out has been regained. The company is also entering direct-store-delivery and convenience channels with more than 25 distributors, which it expects to add about a point of revenue. Net leverage ended at 3.6x versus the roughly 4x management had expected, and the target is below 3x in fiscal 2027. Management's tone was more decisive than the defensive posture of earlier calls.
Bears still have legitimate ammunition. The company withdrew its long-term algorithm of 7%-9% sales growth and an 18%-20% EBITDA margin, with a refreshed framework promised on the fiscal second-quarter call. Management expects Premier consumption to grow at a mid-single-digit rate, below a category growing at a high-single-digit rate, which implies continued share loss. Several other risks remain:
- promotional plans with a key food/drug/mass retailer are unfinalized after the price increase;
- commodity inflation is running at a high-single-digit rate, with proteins only about 70% hedged;
- the company may owe minimum-volume payments to co-manufacturers;
- a CFO transition is underway;
- buybacks have been paused in favor of deleveraging.
Credibility is also an issue. Fiscal 2026 EBITDA guidance was cut on every call, from $425-$440 million to $275-$295 million.
Investors entered the report deeply skeptical. Earnings Whispers sentiment, already negative, deteriorated further from -0.44 to -0.59. The stock's path since the August report has been volatile. Shares opened at $10.55 after that release, briefly reached $13.03, then collapsed to a 52-week low of $7.33 on October 1. They have since rebounded about 50% to $11.01, a modest 4.4% gain from the post-report open. The rebound has not repaired the longer-term damage. Shares sit 11.5% below the 200-day moving average and 15.5% below the inter-earnings high. Momentum readings remain negative even as the stock trades above its anchored VWAP.
The bottom line is that BellRing's beat matters less than its reset. The fourth-quarter upside came from promotion-fueled volume that crushed margins. Fiscal 2027 deliberately sacrifices sales and likely market share to restore profitability. The margin recovery plan is concrete, built on pricing, cost savings and the absence of inventory charges. Its success, however, depends on elasticity holding near plan and retailers cooperating, while the company is operating without long-term targets. Until the May strategy update shows that margins can recover without the franchise continuing to lose share, skepticism looks earned rather than excessive.
Read our earnings preview for BellRing Brands, Inc.: https://www.earningswhispers.com/article/BRBR/23122
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 6 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| Nov-12 | |
| Nov-10 | |
| Oct-29 | |
| Oct-27 | |
| Oct-13 | |
| Sep-26 | |
| Aug-18 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 |
