Global-E Beats On Profit And Raises Again, But Acquired Growth Masks Cooling Organic Momentum
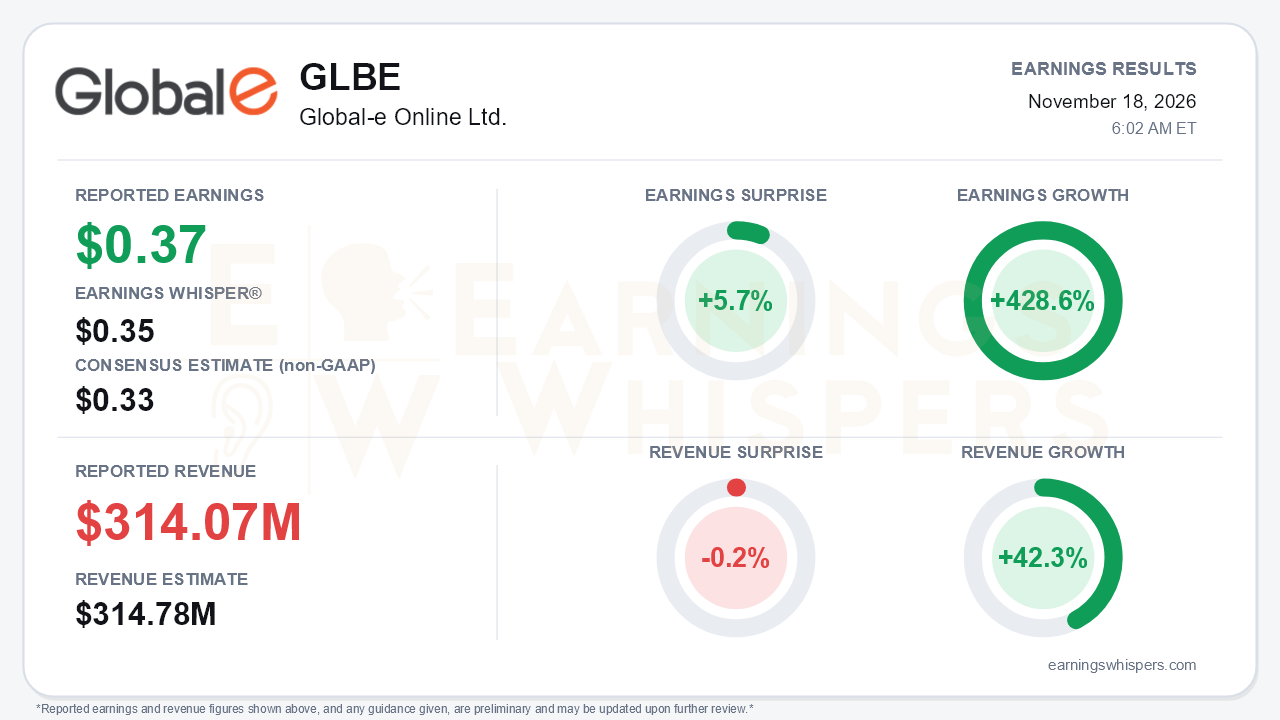
Global-e Online delivered a profit beat and a third straight guidance raise in the third quarter, yet the quarter's real message is that its organic engine is cooling while acquired revenue and cost discipline carry the headline. Non-GAAP earnings of $0.37 per share topped the $0.33 consensus by 5.7% and cleared the $0.35 Earnings Whisper number. Earnings grew 428.6% year over year. Revenue rose 42.3% to $314.07 million but slipped 0.2% short of the $314.78 million consensus. That is a slight miss, but it is notable for a company that beat the high end of its guidance across every metric last quarter and this time cleared only the midpoints on GMV and revenue.
The quality of the beat deserves scrutiny. Reported revenue growth accelerated to 42% from 39% in Q2 and 33% in Q1, but that progression leans on the Passport acquisition. Organic growth was roughly 31%, according to an analyst on the call. GMV growth went the other way, slowing to 35% from 44% in Q2 and 40% in Q1. GMV of $2.042 billion actually fell sequentially from $2.089 billion, counter to the usual seasonal pattern. Service fee revenue, the higher-quality line, grew 30% versus 36% last quarter. Fulfillment services climbed to 57% of the revenue mix from 53% a year ago.
Profitability tells a split story. Adjusted EBITDA reached $63.7 million, above the top of the $58.5-$62.5 million guide, and margin expanded 159 basis points to 20.3%. Operating leverage, aided by AI-supported internal tools, did the work: R&D and sales and marketing each ran near 10% of revenue. Non-GAAP gross margin, however, slid for a second consecutive quarter. It fell to 44.8% from 45.3% in Q2, 47.0% in Q1 and 46.3% a year ago. Management blamed lagging fuel surcharges and Passport's mid-30s gross margin. GAAP net profit of $81.1 million was inflated by a $49 million non-recurring valuation allowance release, which non-GAAP results exclude. Free cash flow fell to $66.4 million from $73.6 million. Cash and investments dropped to about $347 million from $530 million in Q2, after the Passport purchase and $53 million of buybacks.
On the call, management conceded that same-store sales decelerated from the first half. Part of that reflects reversing FX tailwinds, but part goes beyond currency. Management also cited three additional pressures:
- take-rate pressure from volume-tiered pricing for larger merchants;
- slower-than-expected adoption of US J1 duty drawback, as merchants focus on IEEPA tariff refund claims;
- a Passport service-fee mix running below plan.
Against that, the call preserved a credible 2027 growth narrative. Managed Markets GMV growth outpaced the enterprise business late in the quarter, and UK and Canada doubled their share of daily volume. Managed pricing with guaranteed shipping rates has lifted merchant conversion about 50%. Shopify's Global by Default is now on for new Shopify Payments merchants. Passport is the default standard-shipping option for new US merchants. CBP approval to reclaim duties on US returns should produce first claims before year-end, and AI-sourced volumes roughly doubled sequentially.
Guidance moved up, though the raise was more modest than earlier in the year. The full-year revenue range narrowed to $1.329-$1.353 billion from $1.305-$1.355 billion, a higher midpoint but an essentially unchanged top end. Adjusted EBITDA guidance tightened to $290-$300 million from $278-$300 million. Q4 revenue guidance of $464-$488 million sets up a peak season that must offset softer same-store trends. Management again said it expects to exit 2026 ahead of its long-term targets.
Investor sentiment improved meaningfully into the report, moving from modestly negative (-0.20) to modestly positive (+0.23). Price action has been less enthusiastic. At $39.81 on the eve of the release, shares were 3.0% below their open after the August report. They sat 12.1% below the $45.28 52-week high set November 5, having surrendered much of a fall rally. The stock still traded 10.8% above its 200-day moving average and 12.1% above its September low, leaving it mid-range rather than stretched. Earnings Whispers trend readings are mostly positive, though AVWAP remains negative, consistent with buyers who entered at recent highs sitting on losses.
The bottom line is that Global-e delivered a profit beat and another raise, but beneath the headline, GMV, same-store sales, service fees, gross margin and free cash flow all softened. Bears have legitimate ammunition in the sequential GMV decline and Passport's margin dilution. Bulls can point to EBITDA leverage and an expanding set of 2027 catalysts in Managed Markets, Passport and duty recovery. The holiday quarter will show which story carries more weight.
Read our earnings preview for Global-e Online Ltd.: https://www.earningswhispers.com/article/GLBE/23123
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 5 hours | |
| 9 hours | |
| 10 hours | |
| Nov-10 | |
| Nov-03 | |
| Oct-19 | |
| Oct-01 | |
| Sep-18 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 | |
| Aug-10 | |
| Jul-29 |
