Hafnia's Q3 Steps Down From Its Q2 Peak, But $55K Q4 Coverage And The TORM Exit Reshape The Story
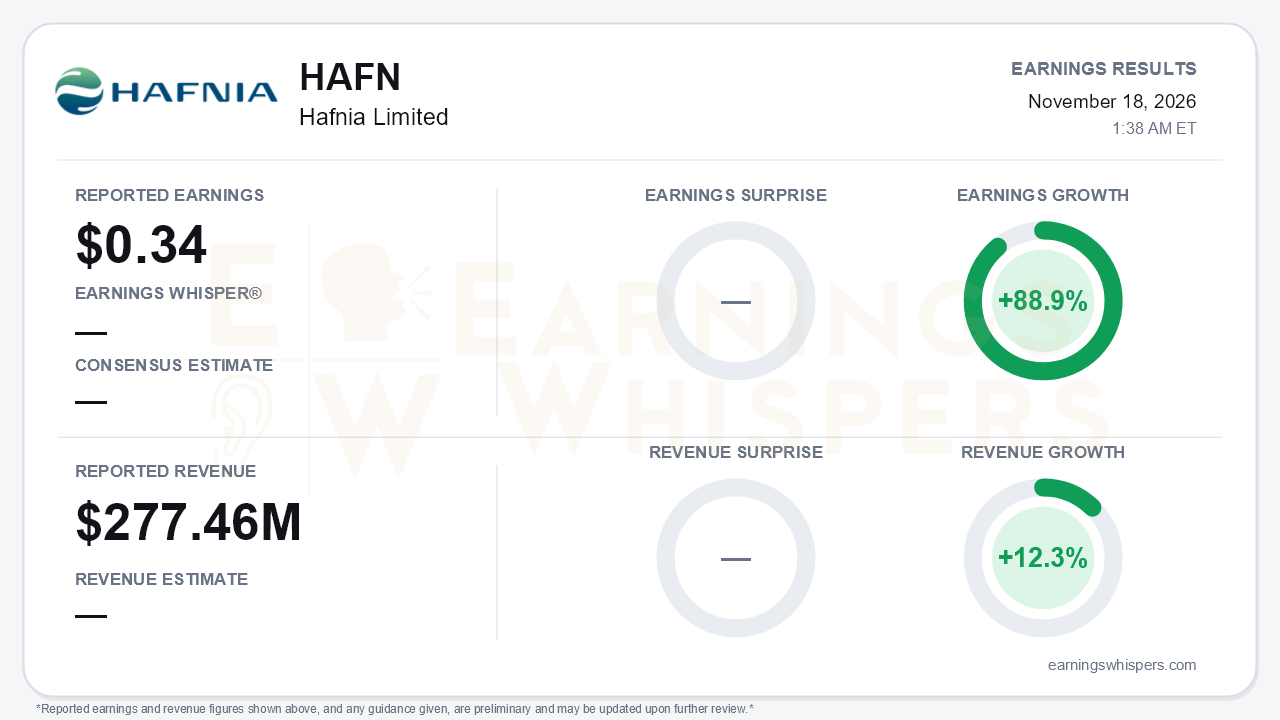
Hafnia Limited (NYSE: HAFN) earned $0.34 per share in the September quarter, up 88.9% from a year ago. Revenue, measured as TCE income, was $277.46 million, up 12.3%. Net profit was $170.8 million, against $91.5 million in Q3 2025. No consensus estimate was available, so there is no surprise to measure. The year-over-year comparison flatters the quarter, because Q3 was a clear step down from Q2. Net profit fell from $277.8 million, TCE income from $372.9 million, and adjusted EBITDA from $287.3 million to $209.7 million. That is the central tension: the trend weakened sequentially, while the forward book points to a much stronger fourth quarter. The quarter's defining event, however, was strategic rather than financial.
The quality of the quarter is reasonably clean, with some qualifications.
- **Rates:** Fleet TCE averaged $32,708 per day, down from $44,093 in Q2. Spot earnings slipped to $35,220 from roughly $50,000.
- **Drydocking:** About 259 off-hire days for scheduled drydockings cut operating days to 8,673, from 9,485 a year earlier. Management expects roughly 99 off-hire days in Q4.
- **Returns:** Annualized ROE fell to 25.3% from 44.6%, and ROIC to 18.9% from 35.2%.
- **Joint ventures:** Share of profit from joint ventures jumped to $20.9 million, from $4.4 million a year ago, and supported the bottom line.
- **Fee-based business:** Earnings slipped to $6.3 million from $8.8 million in Q2.
- **One-offs:** Q3 had essentially no gains on asset disposals. Year-to-date profit of $628.3 million does include about $72 million of such gains booked earlier in the year.
The forward picture is where the call turned constructive.
- **Q4 coverage:** The release says 74% of Q4 earning days were covered at $55,148 per day as of November 13. The call referenced 70% coverage at the same rate. Either way, that rate is far above the $30,716 per day Q3 coverage disclosed on the Q2 call.
- **Full-year outlook:** Management now points to roughly $1 billion of 2026 net profit, the top of the $700 million to $1 billion range floated earlier in the year. That implies a Q4 stronger than any quarter so far in 2026.
- **Market drivers:** Crude tanker strength is pulling LR2s into dirty trades. The clean LR2 fleet is down 31% year over year. Diesel inventories are depleted, and refinery runs are set to climb from their October low. Management sees inventory rebuilding adding about 2.2 million barrels per day of transport demand into 2027.
The bigger shift is strategic. Hafnia abandoned its pursuit of TORM after its approaches were not reciprocated, and management said no other M&A is currently in view.
- **Special dividend:** The board prefers to distribute the entire TORM stake, about 20.4 million shares worth roughly $686.6 million or $1.28 per Hafnia share. This would replace the Q3 and Q4 cash dividends.
- **TORM economics:** The stake cost about $515 million. Including $53.8 million of dividends received, the investment produced a gain of roughly $225 million.
- **Execution risks:** The distribution depends on third-party cooperation. If that cooperation is not secured by November 25, Hafnia will fall back to a 90% cash payout. The ratio is fixed in shares, so recipients bear TORM price risk until payment. The distribution would also cut NAV by about $1.28 per share.
- **Growth plans:** Without consolidation, the near-term growth path rests on exercising eight purchase options for about $235 million and on 10 MR newbuilds.
The balance sheet improved again.
- **NAV:** Rose to about $5.2 billion, or $9.80 per share, from $4.4 billion in Q2.
- **Leverage:** Net LTV fell to 11.9%.
- **Liquidity:** Rose to about $911 million.
Part of that improvement was purchased, however. A roughly $300 million equity raise was 3.5 times oversubscribed but diluted holders by about 7%, at NOK 80 versus a quarter-end NAV of NOK 94.16. A new 100% payout tier applies when net LTV is below 10%. Yet management indicated net LTV would rise to roughly 18-19% under a new fully committed calculation that includes about $400 million of remaining yard installments. That makes the top payout tier less attainable than it first appears.
Bears have legitimate ammunition beyond the sequential decline.
- Clean loadings eased in October to 17.4 million barrels per day, from 18.3 million in September.
- Crack spreads are coming off their peak.
- Normalization at Hormuz or in the Red Sea could release tonnage now absorbed by ship-to-ship shuttling.
- The IEA expects global oil demand to fall 2.7 million barrels per day in 2026.
Investor sentiment and current-price data were unavailable for this report. For context, shares opened at $8.35 after the August report, just above the current 200-day moving average of $8.25. That suggests the stock entered this period near its longer-term trend line and below reported NAV.
The bottom line is that Hafnia's Q3 was a predictable cool-down from an exceptional Q2, worsened by heavy drydocking. The forward evidence matters more: Q4 coverage near $55,000 per day and a roughly $1 billion full-year profit outlook. The quarter's real change is the end of the TORM consolidation thesis, which converts a strategic asset into a one-time shareholder distribution and leaves growth dependent on organic fleet additions. Investors get a strong near-term earnings runway and a cleaner balance sheet. They also face a market still hostage to Gulf security and a capital-return path with execution risk of its own.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| 10 hours | |
| Oct-05 | |
| Sep-25 | |
| Sep-24 | |
| Aug-28 | |
| May-28 | |
| May-08 | |
| Apr-29 | |
| Apr-17 | |
| Apr-14 | |
| Apr-09 | |
| Apr-03 | |
| Mar-27 | |
| Mar-17 |
