C3is Slips To A Q3 Loss As Dry Docks And A Halved TCE Interrupt Its Tanker Windfall, While Cash Keeps Building
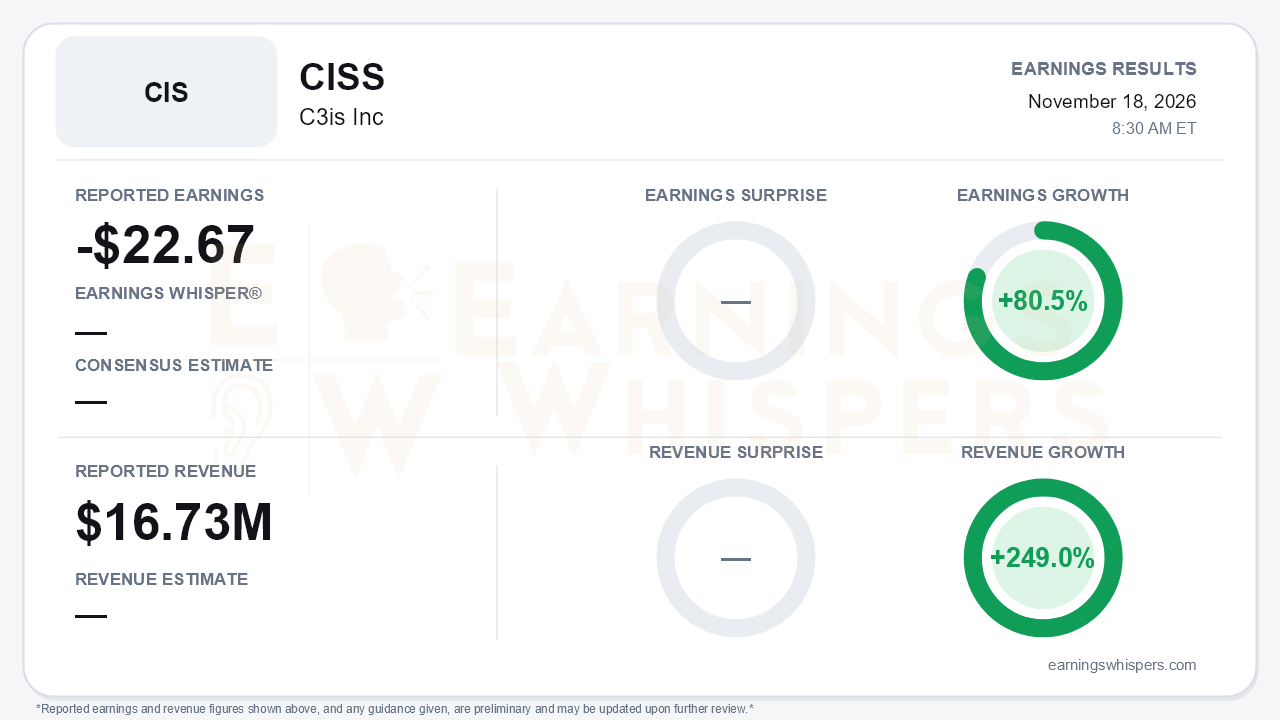
C3is (NASDAQ: CISS) reported a third-quarter adjusted loss of $22.67 per share on revenue of $16.73 million. Revenue grew 249.0% year over year, and per-share earnings improved 80.5% from the year-ago adjusted loss. There was no consensus estimate to measure the quarter against, so the more useful comparison is sequential, and it is unflattering. The year-over-year improvement is real: Q3 2025 was depressed by an idle, dry-docked Aframax. But the quarter's central tension is that earnings fell off a cliff from Q2 even as the market backdrop, the balance sheet and fleet values all kept improving.
The sequential numbers frame the problem.
- **Revenue:** voyage revenue fell to $16.7 million from $24.0 million in Q2.
- **Net revenue:** time-charter-equivalent revenue nearly halved, to $9.3 million from $17.0 million.
- **Rates:** fleet TCE dropped to roughly $20,500 a day from about $40,300, and the Aframax slid to $81,300 from $133,500.
- **Profitability:** operating results swung to a loss of about $2 million from a $9.7 million profit. Adjusted net income moved to a $2.1 million loss from a $9.8 million gain.
- **Cash earnings:** EBITDA was just $1.2 million, and adjusted EBITDA was only $0.3 million.
The GAAP net loss of $1.2 million was cushioned by a $0.9 million warrant gain, which is why the adjusted figure is the cleaner read.
The quality of the quarter deserves scrutiny beyond the rate decline. Two dry dockings, one tanker and one bulker, cost $3.1 million and pulled fleet utilization down to 87.8% from 93.5% a year earlier. Operational utilization fell to 57.0% from 67.7%. Voyage expenses quadrupled to $7.4 million as spot days more than doubled to 251. That makes earnings far more exposed to bunker and port costs.
The per-share picture is where common shareholders should focus. A $4.97 million "down round" deemed dividend on the Series A preferred pushed the loss attributable to common shareholders to $6.4 million on a GAAP basis and $7.2 million on an adjusted basis. That is several times the headline net loss. The share math is also distorted by seven reverse splits since April 2024, the latest in November 2026, which is why the year-ago per-share figures run into the tens of thousands of dollars. The release's own presentation is also inconsistent. It labels nine-month adjusted EPS as positive $23.17, yet its reconciliation shows adjusted income attributable to common shareholders of negative $2.5 million. The call analysis separately flagged conflicting figures. Investors should lean on the dollar-denominated results rather than the per-share ratios.
The call preserved a credible operating story, with several supports:
- **Fleet:** the second MR product tanker, Clean Reaper, was delivered in Q3, completing a six-vessel, 311,431 dwt fleet.
- **Dry bulk:** management called the markets "superb." The Baltic Dry Index averaged above 3,000, its best quarter since 2021.
- **Bulker charters:** new time charters were fixed at $19,500 a day for two vessels and $17,000 a day for the third. That compares with the roughly $12,700 handysize average cited on the Q1 call, giving those three ships better visibility into early 2027.
- **Outlook:** management expects Q4 to sustain the strong nine-month performance, and the CEO noted tanker rates were elevated even on non-war routes.
The balance sheet is the strongest part of the setup:
- **Liquidity:** cash and time deposits reached $59.7 million at quarter-end, up from $14.9 million at year-end 2025, and rose to $64.9 million by mid-November.
- **Debt:** there is no bank debt, and all vessels are unencumbered.
- **Fleet value:** the fleet's market value rose to $145 million from $123 million in Q2, against $110.6 million of book value.
Bears still have legitimate ammunition:
- **Seller financing due:** about $38.7 million of deferred purchase price for the two MR tankers, owed to a related party, comes due in January 2027. It is covered by cash but will absorb most of it.
- **Dilution:** management flagged further equity issuance for growth, extending a pattern that already includes an ATM program, a July offering, warrant exercises and repeated reverse splits.
- **Rate durability:** elevated tanker rates are tied partly to Middle East and Strait of Hormuz disruption, which could normalize.
- **Spot exposure:** spot-heavy tanker earnings swing sharply, as Q3 demonstrated.
Market context offers little help. Investor sentiment readings were unavailable. The shares opened at $2.52 after the August report, while the 200-day moving average sits at $213.72. That gap almost certainly reflects reverse-split adjustment rather than any meaningful technical signal. It underscores how much of the stock's long-term chart has been shaped by capital-structure actions rather than operating results.
The bottom line is that C3is delivered a weak quarter inside a strong year. Dry-dock downtime and a halving of fleet TCE wiped out Q2's profits, and preferred-share deemed dividends deepened the hit to common shareholders. Meanwhile, cash, fleet value and charter coverage all moved in the right direction. Whether Q3 proves to be an air pocket depends on Q4 rates holding up as management expects. It also depends on whether the January 2027 tanker payments and future growth can be funded without further eroding common shareholders' per-share value.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 7 hours | |
| Nov-12 | |
| Nov-05 | |
| Oct-12 | |
| Aug-27 | |
| Aug-27 | |
| Aug-27 | |
| Aug-24 | |
| Aug-17 | |
| Jul-27 | |
| May-18 | |
| May-18 | |
| May-18 | |
| May-14 |
