CAAP Misses On EPS As Argentina Weighs On EBITDA, But Its 2056 Concession Extension Changes The Long-Term Setup
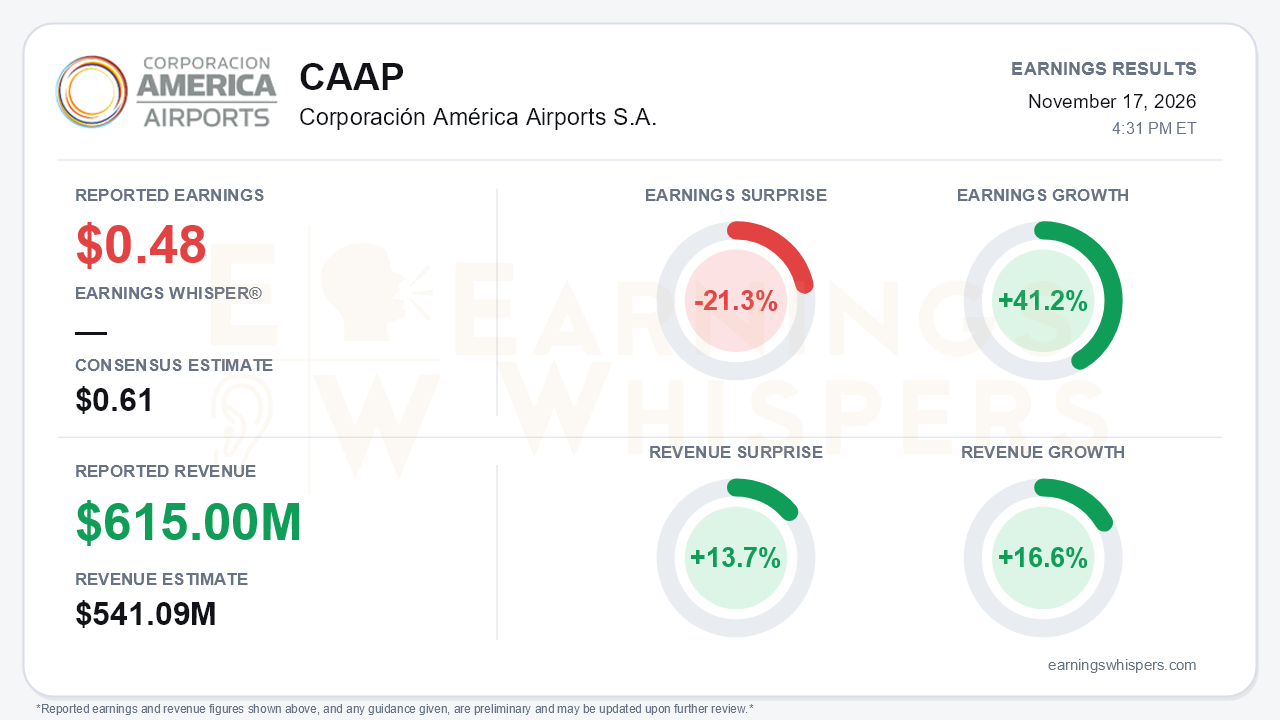
Corporación América Airports delivered a quarter in which the long-term story strengthened while near-term operations weakened. Third-quarter earnings of $0.48 per share missed the $0.61 consensus by 21.3%, even though EPS grew 41.2% year over year. Revenue of $615.0 million beat the $541.09 million consensus by 13.7% and grew 16.6%. Those headline numbers point in different directions, and neither fully captures the quarter. The most important development was the Argentine government's approval of the Aeropuertos Argentina concession rebalancing, which extends CAAP's largest operation through February 2056. Underneath that milestone, Adjusted EBITDA stalled and growth slowed sharply. That is the central tension.
The quality of both the revenue beat and the earnings growth deserves scrutiny. The $615.0 million total includes about $79 million of IFRIC 12 construction-service revenue. That revenue is booked at roughly a 3% to 5% margin. Excluding it, revenue was $536.1 million, up 13.6%, and much closer to the consensus figure. Operating performance was weaker than the reported EPS growth suggests. Operating income fell 2.9% to $142.6 million. Adjusted EBITDA ex-IFRIC 12 slipped 0.9% to $192.5 million. The ex-IFRIC 12 margin contracted 5.3 points to 35.9% from 41.2%. Net income attributable to shareholders rose 42.4% to $78.4 million, so the earnings growth came from below the operating line rather than from core airport profitability. Hyperinflation accounting also matters here: IAS 29 cut $0.17 from reported EPS, and on an ex-IAS 29 basis EPS was $0.65 versus $0.30.
The call made the deceleration plain:
- Traffic growth slowed to 1.3%, down from 7% in the first quarter and 9% in the fourth quarter of 2025.
- Revenue growth eased to 14% from 19%.
- Aeronautical growth dropped to 6% from 17%.
- Adjusted EBITDA fell 1%, compared with gains of 26% in the first quarter and 40% in the year-ago fourth quarter.
Argentina was the culprit:
- Domestic traffic fell 6%, largely because of Flybondi's suspension. That carrier held roughly 15% domestic share a year ago.
- Real peso appreciation inflated local costs.
- Cargo revenue fell 9% against a tough comparison.
- Lower dollar-denominated domestic tariffs added further pressure.
The result was an 11% drop in Argentine EBITDA and a 5.5-point margin decline. Management did point to genuine offsets. Revenue per passenger rose 12% to $22.7. Commercial revenue grew 22%. Armenia traffic accelerated to 17% growth, and every market outside Argentina grew EBITDA.
The forward-looking catalysts are substantial. The Argentine amendment includes:
- dollarized tariffs;
- a domestic passenger fee raised to $9 effective December 10;
- U.S. CPI indexation beginning in 2029 or 2030;
- a 14.3% regulatory IRR;
- $600 million of committed direct investment.
Aeropuertos Argentina issued $400 million of 8% ten-year notes, which were about 2.5 times oversubscribed, to refinance and fund that spending. Combined with Armenia's 35-year extension earlier in the year, the average life of the portfolio has lengthened materially. Pipeline activity also broadened:
- The Toscana Aeroporti stake rose to about 68%.
- CAAP submitted a non-binding offer for Catania Airport.
- The Brasília concession was rebalanced to a revenue-linked fee, with a share auction set for December 17.
- New commercial space opened at Pisa and Brasília.
The near-term risks remain real. October Argentine domestic traffic was still down 1.4%, though management noted a September return to growth. A 17-day Ezeiza runway closure will hit fourth-quarter traffic. Brazil and Italy carried one-off margin drags. Management offered no formal financial guidance.
The balance sheet absorbed a roughly $150 million dividend without strain. Net leverage rose to 0.7x from 0.5x in the first quarter, and net debt climbed to $582 million from $490 million. Cash stood at $476.4 million. Management cited broader liquidity of $840 million, which is a wider measure than cash alone. Bears have legitimate ammunition in the margin compression. However, the leverage profile gives CAAP room to fund its concession commitments and pursue acquisitions.
Investor sentiment moved from roughly neutral to modestly negative, slipping to -0.13 from +0.03. That suggests expectations had already cooled toward the operating slowdown. The stock has gone essentially nowhere, trading at $24.08, up just 2.3% since the open after the August report. Shares sit about 5.4% below their 200-day moving average of $25.45. The AVWAP trend reading remains negative, consistent with a market that has not rewarded the concession progress with sustained buying.
The bottom line is that CAAP removed its biggest long-term uncertainty in this quarter but lost its near-term earnings momentum. The concession extension, dollarized tariffs, and the December fee increase give the Argentine franchise a clearer economic runway. Meanwhile, the quarter showed stalling EBITDA, shrinking margins, and traffic growth near a standstill. For the setup to improve, investors will likely need evidence that the higher domestic fee and a recovering Argentine market can restore margin expansion in 2027. Until then, the beat on headline revenue and the jump in EPS overstate how well the core business performed.
Read our earnings preview for Corporación América Airports S.A.: https://www.earningswhispers.com/article/CAAP/23191
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-18 | |
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-13 | |
| Nov-11 | |
| Nov-11 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Sep-28 | |
| Sep-28 | |
| Sep-16 | |
| Sep-16 |
