Golub Capital BDC Matches On Income, But Credit Losses Push NAV To $14.00 And Leave The Dividend With No Margin For Error
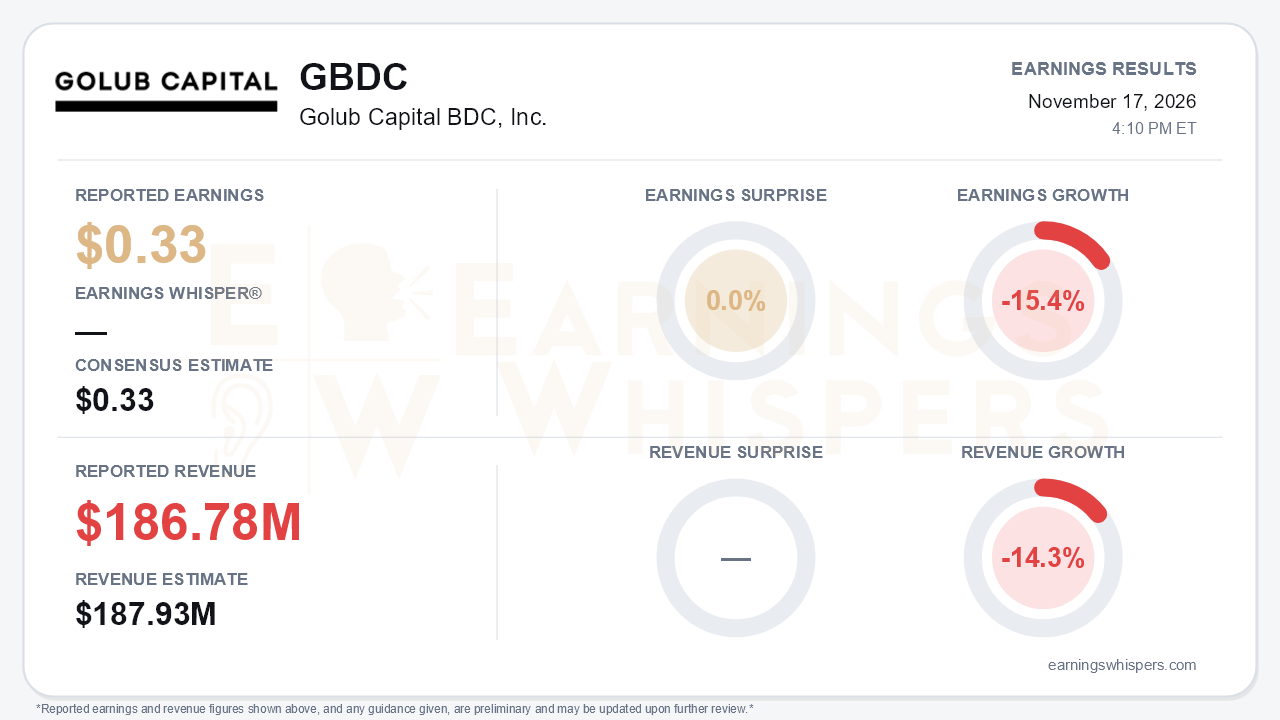
Golub Capital BDC delivered exactly what the income line needed to deliver, and little else. Adjusted net investment income of $0.33 per share for the fiscal fourth quarter ended September matched the $0.33 consensus estimate, but earnings fell 15.4% from a year ago. Revenue of $186.78 million missed the $187.93 million consensus by 0.6% and was down 14.3% year over year. The in-line headline hides a weaker quarter beneath it. GAAP earnings per share fell to $0.08 from $0.22 in the June quarter, NAV per share slid to $14.00 from $14.25, and management itself described the results as disappointing. That is the central tension: income still covers the distribution, but credit losses keep eroding the capital base that produces that income.
The quality of the quarter deserves scrutiny. Adjusted net investment income has stepped down from $0.38 in the first fiscal quarter to $0.34 in the second and third, and now to $0.33. That exactly matches the $0.33 quarterly distribution, which the board has declared again. On a GAAP basis, net investment income was $0.32, a penny short of the payout. Net realized and unrealized losses widened to $0.25 per share on an adjusted basis from $0.12 in the prior quarter. Management attributed the losses mainly to three known problem credits that were on or moved to non-accrual, along with further markdowns on equity in previously restructured companies. NAV has now declined every quarter this fiscal year, from $14.84 to $14.00. Adjusted return on equity fell to 2.3% from 6.2%.
The call explained why income is drifting lower. Golub repaid $600 million of 2.5% notes at maturity in August. That pushed its cost of debt to 5.6% from 5.3% and compressed the net investment spread to 4.3% from 4.6%. Interest expense rose even as total investment income edged down. The portfolio also shrank to $7.8 billion from $8.2 billion, and net leverage fell to 1.17x from 1.23x as management deleveraged and bought back stock. New commitments of about $20 million were up from $13 million but remain negligible against a book of that size. Credit migration was also unfavorable:
- Loans rated 3 on Golub's internal scale climbed to 12.2% of the portfolio from 10.6%, and from 8.7% two quarters ago.
- The two highest rating categories slipped to roughly 85%.
- The non-accrual count rose to 22 from 20, versus 14 at the start of the year.
- Non-accruals at fair value improved to 1.6% from 1.9%, but that partly reflects deeper markdowns rather than healing.
Management did lay out a credible set of offsets. Base rates are now moving higher, and the September increase has not yet flowed into loan yields. Management estimates resets beginning in the December quarter add more than a penny per share each quarter for every 50 basis points. Golub is waiving its full income incentive fee for the December quarter, which directly supports coverage. Management also argued for roughly $0.29 per share of potential NAV recovery if marks on loans rated 4 and 5 normalize. Other supports included:
- a full recovery of principal, interest and equity proceeds on US Dermatology Partners;
- a revolver extended to 2031;
- more lender-friendly terms in software as competing lenders pull back.
Bears have legitimate ammunition, though. Management expects credit stress to stay elevated, at roughly twice normal, for several more quarters. Turnarounds at restructured credits are deteriorating further. Management also flagged lengthening software sales cycles as AI spending pressures customer budgets.
The market has been pricing the stress rather than the tailwinds. Shares closed at $12.08, down 7.9% from the $13.12 open after the August report. That leaves the stock about 5.3% below its $12.76 200-day moving average and at a discount of roughly 14% to the new NAV. Price and AVWAP trend readings are both negative. Investor sentiment slipped from modestly positive (0.06) to slightly negative (-0.02), a meaningful turn but not a capitulation. Insiders and affiliates are leaning the other way. The company repurchased stock at an average of $12.75 in the quarter and $12.43 since quarter-end, and the Golub employee Rabbi Trust bought $23.3 million of shares in the quarter. Repurchases well below NAV are accretive, but they also shrink an already contracting earning base.
The bottom line is that GBDC hit its income target while the forces underneath moved the wrong way. Funding costs rose, spreads narrowed, the portfolio shrank, credit ratings migrated lower and NAV fell again. The rate resets and the fee waiver should support near-term coverage of the $0.33 distribution. The stock's re-rating, however, depends on management's claim that credit stress is contained to a handful of names. Until rated-3 exposure and non-accrual counts stop climbing, the discount to NAV looks more like a reflection of risk than a mispricing.
Read our earnings preview for Golub Capital BDC, Inc.: https://www.earningswhispers.com/article/GBDC/23113
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-18 | |
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-10 | |
| Oct-06 | |
| Sep-14 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-07 | |
| Jun-05 | |
| Jun-02 | |
| May-31 | |
| May-19 |
