Kanzhun's Pricing Pivot Faces First Real Test As Shares Slide Toward Range Lows
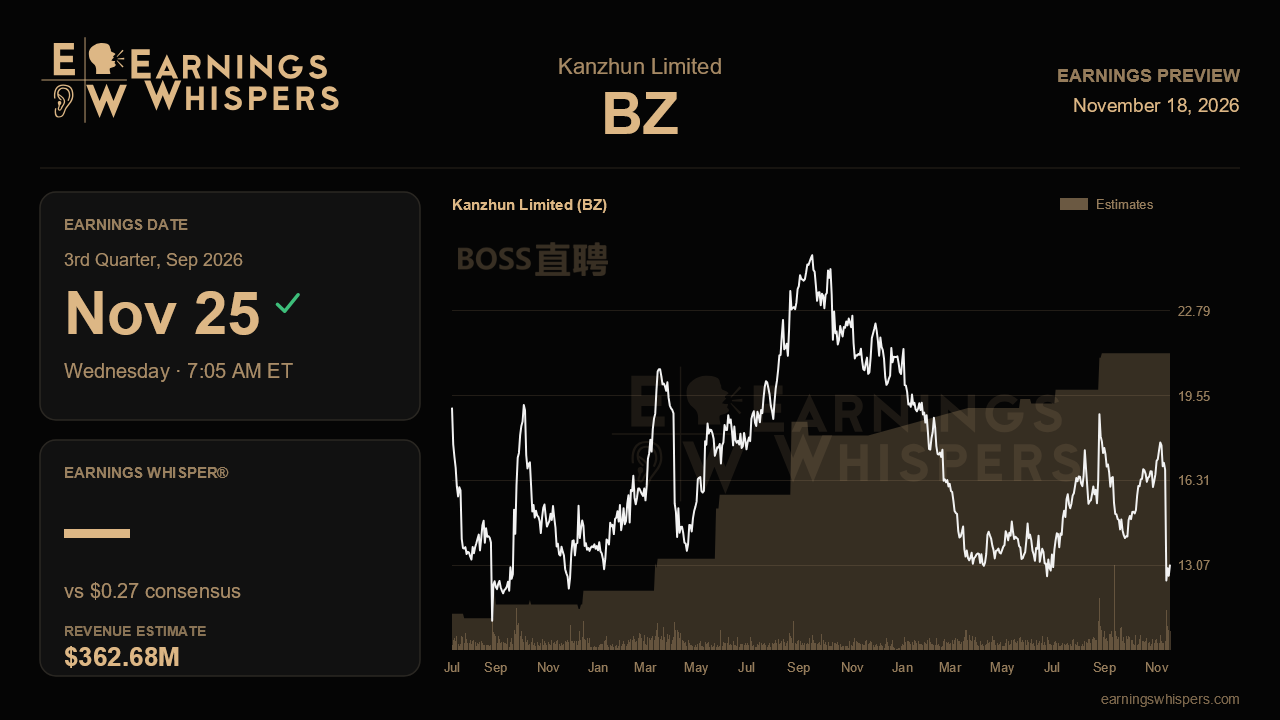
Last quarter Kanzhun told investors that BOSS Zhipin was entering a new chapter, one in which growth would come not only from signing up more employers but from charging mature-market customers more. The market has not bought the story yet. Shares have fallen 14.3% since that report, roughly ten percentage points worse than the S&P 500, even though the quarter featured re-accelerating revenue and a record margin. That gap between operating momentum and stock performance makes the September-quarter report, due before the open on November 25, an unusually clean test of whether the monetization pivot is real.
The Street is looking for earnings of $0.27 per share, matching the prior quarter and up from $0.24 a year ago, on revenue of $362.7 million. That revenue figure implies 19.4% growth in dollar terms, but the more meaningful yardstick is management's own local-currency guidance of RMB2.41 billion to RMB2.50 billion, or 11.4% to 15.6% growth. Translated, the company's outlook spans roughly $358.5 million to $371.9 million, and consensus sits in the lower half of that band, below the midpoint of about $365 million. In other words, analysts are not asking for heroics. A result near the top of the range would signal that the second-quarter acceleration to 14% growth from 7.6% in the holiday-depressed first quarter was the start of a trend rather than a bounce.
The most important number may not be revenue at all but average revenue per paying user. ARPPU rose 7% in the June quarter after hovering around flat through much of the prior year, and the paying ratio improved for a fourth straight quarter. That is the early evidence behind management's plan to lift both conversion and unit prices in Tier 1 and Tier 2 cities while still chasing penetration in smaller cities. It matters because the user engine is maturing: paid enterprise customers grew about 11%, down from the low teens last year. If ARPPU holds in the mid-to-high single digits while customer growth steadies, the pivot looks validated. If pricing gains fade while customer adds keep slowing, the bear case that this is a saturated platform squeezing its base gains traction.
Profitability is the second pillar. The adjusted operating margin hit a record 43.8% last quarter, helped by AI-driven efficiency and flat headcount, even as sales and marketing spending jumped 38% on the World Cup sponsorship. With that campaign's heaviest spend likely behind it, investors should reasonably expect margins to stay elevated. Cash flow deserves equal attention: operating cash flow fell 10% last quarter on marketing and tax outlays, and a rebound would ease concerns that the company's generous capital returns, which already exceeded the prior year's adjusted net income, are outrunning cash generation. GAAP comparisons will also be noisy after last quarter's one-off RMB1.5 billion investment gain, so adjusted figures are the cleaner read.
Sentiment has cooled noticeably, slipping to modestly bearish from roughly neutral heading into the last report, and the stock trades at $13.09, well below its 200-day average near $15.09 and not far above the $12.12 low of its post-earnings range. That positioning reflects worry about the second-half consumption backdrop, a topic management sidestepped last time. Updated commentary on hiring demand from smaller employers and any fourth-quarter guidance will carry real weight.
Ultimately, the report hinges on one question: can Kanzhun raise prices in its most mature markets without choking off the customer growth that built the franchise? Steady ARPPU gains, revenue toward the upper end of guidance and a firm margin would suggest the market has been too skeptical. Anything less would make the new growth strategy look like a response to slowing demand rather than a source of fresh momentum.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-18 | |
| Nov-13 | |
| Oct-23 | |
| Sep-28 | |
| Sep-22 | |
| Sep-21 | |
| Sep-01 | |
| Aug-25 | |
| Aug-25 | |
| Aug-25 | |
| Aug-18 | |
| Aug-13 | |
| Jul-01 | |
| Jun-26 | |
| Jun-25 |
