Pure Cycle's Record Year Ends With A Q4 Profit Dip And A Notably More Defensive Outlook
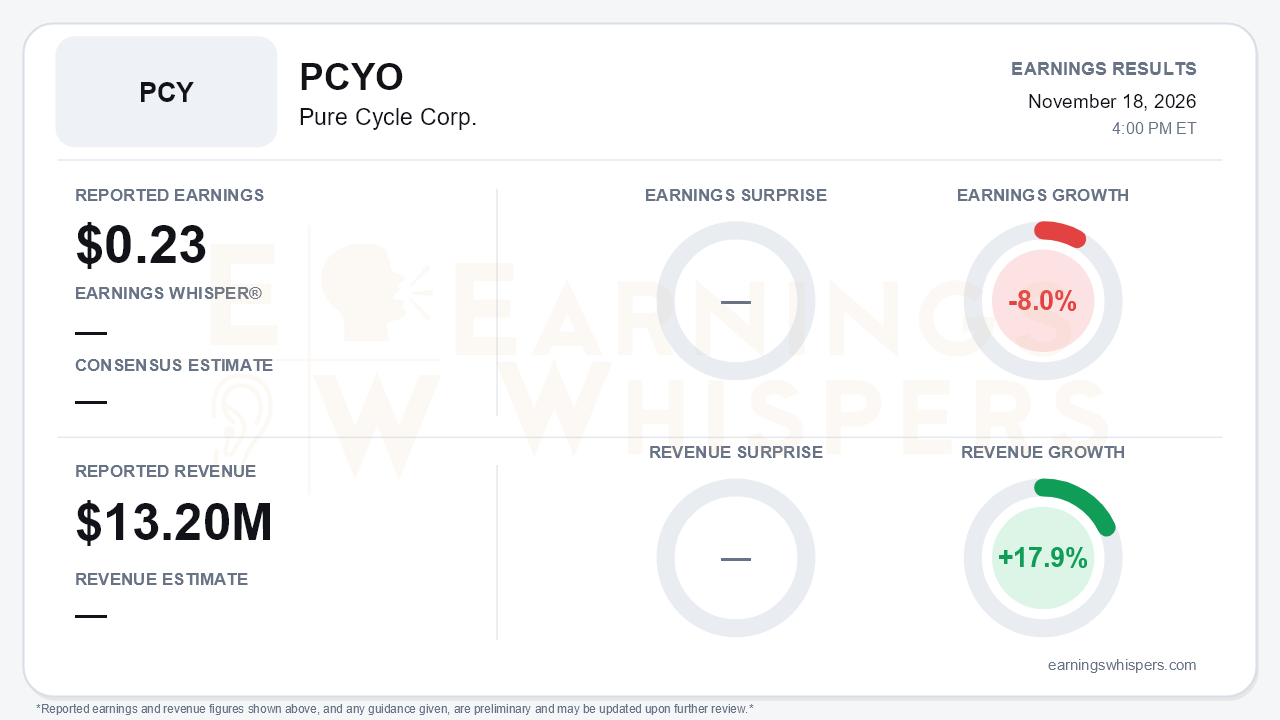
Pure Cycle (NASDAQ: PCYO) closed fiscal 2026 with a quarter that undercuts the 'record year' framing in its release. Fourth-quarter earnings were $0.23 per share, down 8.0% from $0.25 a year earlier, even though revenue rose 17.9% to $13.2 million. No consensus estimate or Earnings Whisper was available, so the quarter has to be judged on its own trajectory. That trajectory shows deceleration. Full-year revenue grew 37% to $35.7 million and EPS rose 9% to $0.59, but fourth-quarter revenue growth slowed to roughly half the annual pace and earnings turned negative. The bigger story, however, was not the numbers. Management used the report to exit a business, suspend buybacks, shrink its next development phase and withhold quantified fiscal 2027 guidance. The release itself warns that fiscal 2027 will carry significant proxy-contest costs.
The operating results were better than the bottom line suggests. Operating income jumped 75% to $13.4 million. Land development revenue rose 40% to $21.4 million as a mild winter let Pure Cycle accelerate percentage-of-completion revenue on Phase 2D. Water and wastewater revenue climbed 30%. Industrial water sales to oil and gas operators were the standout: 1,118 acre-feet delivered to those customers versus 194 a year earlier, and fourth-quarter total deliveries of 638 acre-feet versus 196.
What dragged on earnings was below the operating line. Oil and gas royalty income fell 70% to $2.0 million as the Sky Ranch wells declined from initial production, which held pre-tax income growth to about 8%. The call characterized gross profit as up only ~15% against ~40% revenue growth. The release's line items show stronger gross-margin dollars than that, so the compression appears to sit largely in total income once royalties are included, rather than in segment economics. Either way, the royalty cushion that flattered fiscal 2025 is largely gone. The call's fiscal 2026 revenue range of ~$35.7–37.7 million also differs from the release's $35.7 million; the release figure is the reported number.
The call turned defensive in ways that matter for the forward setup:
- **Rental exit:** The single-family rental plan has gone from roughly 100 homes in Q1 to about 60, then a pause near 70, and now a full exit. The board cited a higher cost of capital and flat rents. Homes will be sold in an orderly fashion, with proceeds used to repay the borrowings secured by those homes.
- **Buyback reversal:** Repurchases were suspended because of a proxy contest led by a former director seeking board control. That reverses the 'more aggressive buyback' message from the Q3 call.
- **Smaller Phase 2E:** At about 154 lots, Phase 2E is the smallest phase since land development began, down from 159–160 cited earlier in the year and well below the typical 230–250. None of its lots were under contract at year-end, yet Pure Cycle broke from its usual practice and kept developing ahead of a signed builder commitment. Management frames that as confidence; it is also a balance-sheet exposure in a housing market it describes as facing affordability, rate and confidence headwinds.
- **No guidance:** No numeric fiscal 2027 guidance was given, despite an earlier promise to provide it.
There is still a credible long-duration story:
- **I-70 interchange:** The permit for the interchange, which would unlock commercial lot sales, is fully submitted, with authorization expected around early 2027 and delivery in 2028. That timeline has drifted from the early-2028 completion framed in Q1.
- **Tap fees:** Management estimates more than $15 million in remaining Phase 2 tap-fee revenue over three years.
- **Industrial water demand:** Management expects oil and gas water demand to continue into fiscal 2027.
- **Capital return:** Management signaled a 'much more aggressive' buyback once the proxy fight is resolved.
- **Land acquisition:** Management also described a softer land market as offering better acquisition opportunities.
Bears have legitimate ammunition, though. Cash fell to $15.4 million from $21.9 million while debt rose to about $17.6 million. Meanwhile, the Sky Ranch CAB receivable kept building, from about $50 million in Q1 to roughly $63 million on the balance sheet. Its collection depends on assessed-value growth and access to the bond market.
Market data offer limited context this time. The stock opened at $10.19 after the July report, and the 200-day moving average stands at $10.86. Without a current price or sentiment reading, it is not possible to say how the shares have traded into or out of this report.
The bottom line is that Pure Cycle's fiscal 2026 operating engine, especially lot deliveries and industrial water sales, was genuinely strong. Even so, the quarter marks a shift from growth to defense. Earnings declined in Q4 and royalty income has faded. The company is unwinding its rental strategy, buybacks are on hold during a proxy fight, and the next lot phase is small and uncontracted, all without numeric guidance. Investors now have to underwrite fiscal 2027 on Phase 2E contract timing, oil and gas water demand and the governance outcome rather than on management's figures.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-19 | |
| Nov-19 | |
| Nov-18 | |
| Nov-18 | |
| Nov-13 | |
| Nov-10 | |
| Oct-19 | |
| Sep-17 | |
| Sep-01 | |
| Aug-25 | |
| Aug-07 | |
| Aug-07 | |
| Aug-04 | |
| Jul-10 | |
| Jul-08 |
