UGI Narrows Its Seasonal Loss And Clears Reduced Guidance, But The Global LPG Spin-Off Is The Real Story
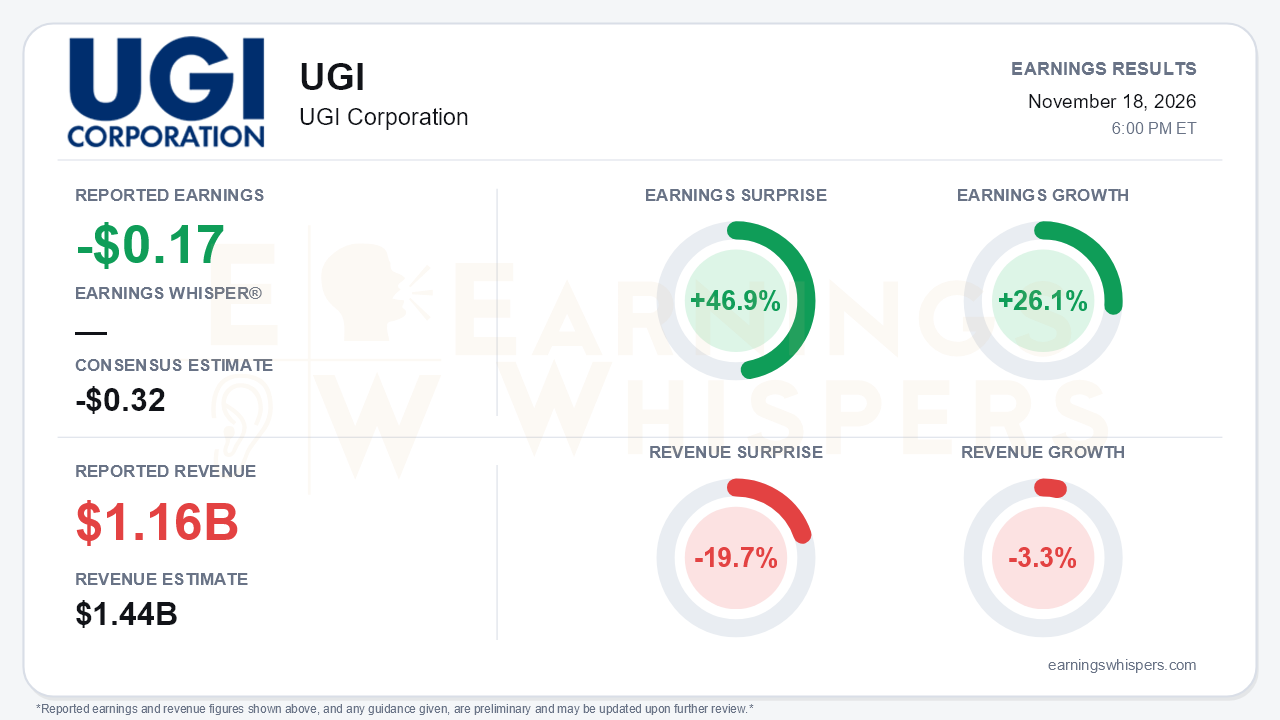
UGI Corporation's fiscal fourth quarter delivered a better-than-expected seasonal loss. The quarter matters less than what management announced alongside it: a board-approved, tax-free spin-off of Global LPG, which combines AmeriGas and UGI International. On Earnings Whispers' normalized basis, UGI lost $0.17 per share against a consensus loss of $0.32, a 46.9% beat and 26.1% earnings growth from the year-ago quarter. Revenue was the weak spot. Sales of $1.157 billion fell 3.3% year over year and missed the $1.44 billion consensus by 19.7%. On a GAAP basis, UGI earned $0.04 per diluted share versus a $0.06 loss a year ago. Derivative gains and other items that management excludes from adjusted results explain the gap between the two figures. The central tension is that UGI is selling investors a cleaner, faster-growing gas utility story while the propane business it intends to separate is still shrinking.
The quality of the full-year result deserves scrutiny. Adjusted EPS of $3.00 cleared the $2.75-$2.90 range set after the second-quarter guidance cut, but it still fell from $3.32 in fiscal 2025. It also included about $0.10 of incremental tax benefits tied to renewable natural gas facilities. Management cited weather-normalized EPS of $3.40, which reframes the year as modest underlying growth. Even so, investors should note that the beat came against a lowered bar. Reportable segment EBIT rose only to $1.198 billion from $1.176 billion, and that gain was concentrated almost entirely in one segment.
That segment is Utilities, which posted record EBIT of $456 million, up $53 million. The drivers were higher Pennsylvania gas base rates, infrastructure-replacement recovery and 5% higher core-market volumes in a colder year. UGI International edged EBIT up to $320 million despite divesting several European LPG businesses and a 10% drop in retail gallons. The other two segments were weaker:
- **Midstream & Marketing:** EBIT slipped to $285 million from $293 million as Marcellus producers stayed disciplined. Management expects fiscal 2027 to look similar, with growth capex pushed out to fiscal 2029-2031.
- **AmeriGas:** EBIT fell to $137 million from $166 million, and retail gallons declined 5%, or 3% on a weather-adjusted basis. That is a deterioration from the flat weather-adjusted volumes discussed at the second quarter. AmeriGas leverage is only 'approaching low 4s,' missing the earlier goal of below 4.0x by year-end.
The call nonetheless marked a clear shift in tone from repair to growth and value unlock. The remaining 'new UGI' would target:
- more than $5 billion of capex over fiscal 2027-2031;
- 8-10% rate base growth;
- 6-8% EPS growth, up from the prior 5-7% framework, with early years near 8-10%;
- no equity issuance for three years after the separation.
Global LPG is being positioned as a cash-return vehicle. Management cited roughly $740 million of EBITDA, $250-$300 million of near-term free cash flow and a 3.25-3.75x leverage target. Supporting catalysts include:
- concluded rate cases in Pennsylvania ($65 million over two steps) and West Virginia ($17 million);
- a FERC certificate for the Auburn pipeline conversion;
- data center NDAs rising to more than 100 from more than 75;
- AmeriGas's first notable commercial volume wins.
Bears have legitimate ammunition. The rate awards fell well short of the $99 million and $27 million requested. Corporate leverage rose to 3.8x from 3.7x, above the 3.75x target, while liquidity fell to $1.8 billion from $2.1 billion. The separation itself carries execution risk around the Form 10 filing, final board approval, still-unnamed management teams and the eventual exit of UGI's retained stake of up to 19.9%. Fiscal 2027 guidance of $2.90-$3.20 brackets the $3.00 just reported, so its $3.05 midpoint implies only modest growth. That outlook also depends on management's promised return to AmeriGas earnings growth, which has yet to show up in the volume data.
Investor expectations have improved meaningfully. Earnings Whispers sentiment swung from mildly negative (-0.11) at the prior report to moderately positive (+0.27). Shares trade at $38.05, up 8.1% from the open after the August report and about 3.9% above the 200-day moving average of $36.60. The trend picture is mixed: price trend readings are positive while AVWAP remains negative. That suggests the recent advance has not fully repaired the stock's longer positioning. The market has been rewarding the simplification narrative, which raises the bar for execution on the spin.
The bottom line is that UGI beat a low bar on the quarter and the year, but the investment case has been redefined around the separation rather than the results. Utilities and rate-base growth provide a credible foundation for the gas-focused remainder. AmeriGas volume declines, softer midstream activity and rising leverage keep the near-term numbers less convincing than the long-term targets. Investors are now underwriting a transformation, and its success depends on whether AmeriGas can actually return to growth before Global LPG stands on its own.
Read our earnings preview for UGI Corporation: https://www.earningswhispers.com/article/UGI/23142
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-19 | |
| Nov-18 | |
| Nov-18 | |
| Nov-18 | |
| Nov-18 | |
| Nov-18 | |
| Nov-10 | |
| Oct-15 | |
| Sep-15 | |
| Aug-18 | |
| Aug-18 |
KKR Makes $9 Billion Takeover Bid for Natural Gas and Electricity Distributor
UGI +9.40%
The Wall Street Journal
|
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-06 |
