Walmart Raises Its Outlook Again, But A Whisper Miss And Normalizing Profit Growth Test A Stock That Ran Hard Into The Print
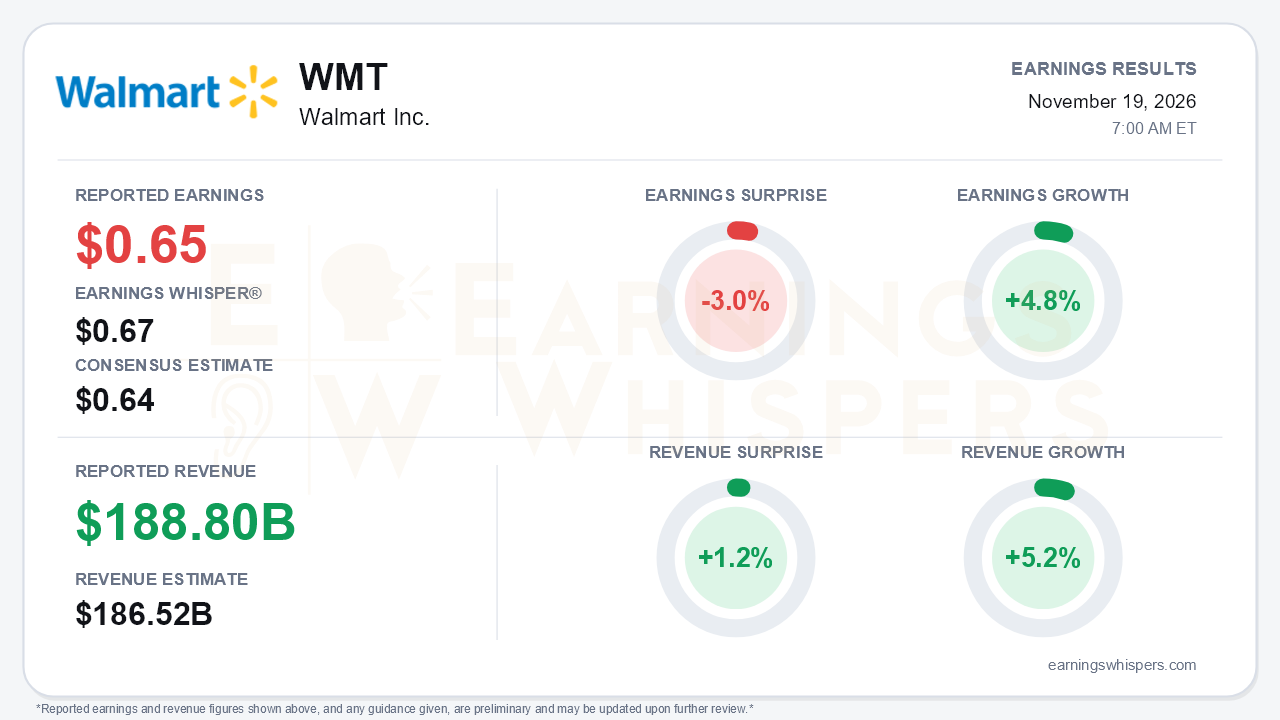
Walmart delivered a fiscal third quarter that management can fairly call a beat, while investors who had rallied the stock into the report could reasonably call it a letdown. Adjusted EPS of $0.65 topped the $0.64 consensus but fell short of the $0.67 Earnings Whisper number, a 3.0% miss against the expectation that mattered most. Revenue was stronger. Sales of $188.80 billion beat the $186.52 billion consensus by 1.2% and grew 5.2% year over year. Earnings grew 4.8%, slightly slower than sales. That is the central tension: the top line and full-year outlook keep improving, but earnings leverage on that growth was thinner than buyers had come to expect.
The quality of the quarter rewards a careful read. The headline 16.0% operating income increase is the flattering number. On an adjusted, constant-currency basis, operating income rose 5.5%. That is the better gauge of underlying profitability, and it is a sharp step down from the 17.4% pace in the second quarter. The call analysis attributes roughly 750 basis points of that Q2 figure to tariff refunds, which Walmart is now reinvesting in price. GAAP EPS was $0.62. The adjusted figure excludes a $0.03 net loss on equity and other investments. Beneath that, the mix story remains attractive. Gross profit rate rose 28 basis points, led by Walmart U.S. Global advertising grew 25%, with U.S. advertising up 37%. Membership fee revenue rose 17%. These higher-margin streams keep giving Walmart room to invest in price without sacrificing the profit trajectory.
Against its own guidance, the quarter was clean. Constant-currency sales growth of 4.4% beat the 3% to 3.75% range management set in August. Adjusted operating income growth of 5.5% cleared a 2% to 4% guide, even after absorbing the tariff-refund price reinvestment. Walmart raised its full-year sales and profit outlook for a second consecutive quarter. In Q2 it had already lifted sales growth to 4% to 5% in constant currency, operating income growth to 7% to 8.5%, and EPS to $2.80 to $2.87. The available call material did not include the specific new ranges, so the size of this latest raise cannot be judged. Management's tone has shifted from "performing how we expect" in Q1 to "even more bullish" in Q2 to "strategy is working" now. It cited strong market share, unit and transaction trends, and explicitly expects a strong holiday season.
The deceleration in eCommerce gives bears legitimate ammunition. Global eCommerce growth slowed from 26% in Q1 to 23% in Q2 and 17% in Q3. Part of the latest drop reflects the timing of Flipkart's Big Billion Days. Walmart U.S. eCommerce was essentially steady at 23% versus 24% in Q2. Sam's Club U.S. eCommerce accelerated to 30% from 26%. Domestic digital momentum therefore looks intact, and the global slowdown appears driven more by international timing than by fading demand. Inventory is worth monitoring. It rose 8.1%, outpacing sales growth, which management attributed to strategic initiatives, seasonal timing and cost inflation. Headwinds flagged in Q2 also linger: more than $2 billion in incremental fuel costs, a pressured lower-income consumer, and a roughly 125-basis-point pharmacy pricing drag on the U.S. comp. Q3 commentary did not update them.
On the catalyst side, the new $120-a-year bundle of Walmart+ and Sam's Club Plus is a meaningful bid to deepen membership economics. Management framed it against about $400 of separate memberships and called early results very encouraging. Expanded agentic-commerce capabilities for the Sparky assistant position Walmart's store and inventory network for AI-driven shopping. Walmart also issued $6.5 billion in long-term debt at what it called favorable rates.
The market setup is more complicated than the revenue beat implies. Shares closed at $127.36 ahead of the report, up 19.7% from the $106.38 open after the August release. The stock sat 7.0% above its 200-day moving average and only 3.4% below its inter-earnings high of $131.82, set November 5. A stock priced near its highs, after nearly a 25% climb off the August low, needed a clear earnings beat, and the whisper shortfall denied it one. Investor sentiment reflects that caution. The reading remained positive but weakened from 0.13 to 0.04, drifting toward neutral even as the price rose. Earnings Whispers price, momentum and AVWAP trend readings remain positive, while sequential growth is neutral. That mix fits a business with strong momentum whose growth rates are normalizing.
The bottom line is that Walmart's fundamental story remains credible. Sales are outrunning guidance, high-margin advertising and membership revenue are compounding, and management has raised its outlook twice in a row. However, profit growth is normalizing from a tariff-aided Q2, global eCommerce is decelerating, and EPS fell short of the whisper. For a stock that entered the report near its highs with cooling sentiment, the burden now shifts to holiday execution to justify the run.
Read our earnings preview for Walmart Inc.: https://www.earningswhispers.com/article/WMT/23170
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 17 min | |
| 19 min | |
| 26 min | |
| 44 min | |
| 54 min | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 3 hours |
Stock Market Today: Dow Rises As Walmart Falls On Earnings; Anthropic IPO To Debut (Live Coverage)
WMT
Investor's Business Daily
|
| 3 hours | |
| 3 hours |
