Williams-Sonoma Falls Short Of The Whisper As Margin Gains Run Into Slowing Comps
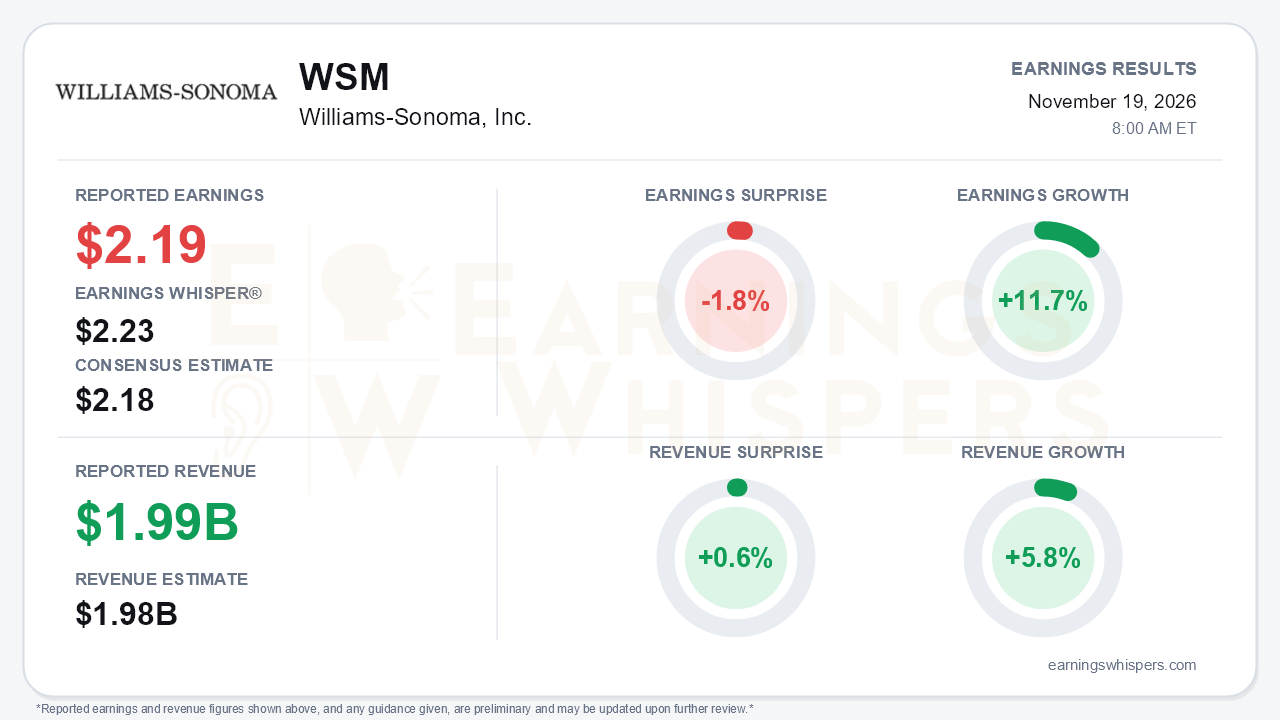
Williams-Sonoma delivered fiscal third-quarter non-GAAP earnings of $2.19 per share, a penny above the $2.18 consensus but short of the $2.23 Earnings Whisper number, a 1.8% miss against the expectation that mattered most for a stock priced for momentum. Revenue of $1.991 billion beat the $1.98 billion consensus by 0.6% and grew 5.8% year over year. Adjusted earnings grew 11.7%, a clear acceleration from roughly 5% growth in the second quarter. Management also reiterated full-year guidance. The central tension is that profitability improved while demand cooled. Margin expansion drove the quarter, but comparable sales decelerated across most of the portfolio, and the cost and macro backdrop described on the call got worse.
The quality of the earnings deserves a closer look, starting with the GAAP-to-non-GAAP gap. GAAP diluted EPS of $2.38, up 21.4%, includes $29.3 million of recognized IEEPA tariff refunds worth $0.19 per share. That benefit added 140 basis points to GAAP gross margin. Excluding the refunds, gross margin was 46.2%, up just 10 basis points. That small gain still marks a real turn from a 160-basis-point decline in the second quarter. Merchandise margin rose 20 basis points on full-price selling after falling 230 basis points in Q2, and occupancy leverage added 40 basis points. Higher oil prices pushed supply-chain costs up and took 50 basis points back. Employment leverage trimmed the non-GAAP SG&A rate by 30 basis points. Non-GAAP operating margin reached 17.4%, up 40 basis points, which management called the largest year-over-year expansion of the tariff cycle. The company has now collected substantially all of its $197.8 million refund claim, so the GAAP tailwind is close to exhausted. Inventory rose 7.3%, slightly ahead of sales, and the company returned $253 million through buybacks and dividends.
The top line is where the story softens. Total comp slowed to 5.1% from 6.2% in Q2. Pottery Barn, the largest brand, fell to a 1.8% comp from 5.1%. Management described that slowdown as deliberate, the result of pulling back markdowns, and plans the same discipline for Q4. That framing is credible given the merchandise-margin recovery, but it means the company is trading volume for margin at its biggest brand. Other brands also slowed:
- Williams Sonoma eased to 6.8% from 7.6%.
- Kids and Teen slipped to 2.9% from 3.5%.
- Retail comp dropped sharply to 1.5% from 5.5%.
There were genuine bright spots. E-commerce comp of 6.8% accelerated for a fourth straight quarter, B2B grew 15%, and West Elm improved to a 7.0% comp. Every brand and channel still posted positive comps, but the overall pace is slowing.
The forward picture carries more risk than the reaffirmed guidance suggests. Diesel is up more than 60% year over year, cost roughly 75 basis points in Q3, and could add up to $60 million in incremental cost this year. The CFO flagged that higher oil prices or more expediting from Middle East shipping disruptions and port congestion could move guidance. Management said the housing market has gotten worse. The long-term algorithm of mid-to-high single-digit growth and mid-to-high-teens margins was dropped from the written release, though management reaffirmed it verbally, and executives avoided FY27 commentary. Guidance also leaves little room for error. Year-to-date non-GAAP operating margin stands at 17.0%, against a full-year target of 17.8% to 18.2%. That target relies on a strong holiday quarter, aided by lower tariff costs that should largely offset lapping a roughly 160-basis-point shrink benefit. Catalysts include:
- the Pottery Barn x Four Sixes Ranch collaboration launching around December 9;
- AI room-planning tools;
- new West Elm and GreenRow stores;
- a full-year interest income outlook raised to about $30 million from $25 million.
The market setup is more demanding than the modest headline miss implies. Shares entered the report at $260.09, up 16.1% from the open after the August report and about 19.5% above the 200-day moving average. The stock sat 5.2% below its 52-week high of $274.45, set on November 5 during this inter-earnings period, and well off its September low of $216.68. Investor sentiment was essentially unchanged and firmly positive at about 0.70. Earnings Whispers trend signals were uniformly positive heading into the print, consistent with a stock that had already priced in continued execution. Against that backdrop, a whisper miss paired with decelerating comps gives bears legitimate ammunition, even though the margin story improved.
The bottom line is that Williams-Sonoma's third quarter was better on profitability than on demand. Underlying margins turned up, earnings growth accelerated, and the company's full-price discipline is showing up in merchandise margin. However, comps slowed at Pottery Barn and in retail, fuel and freight costs are climbing, and housing has weakened. The reaffirmed outlook now depends on a strong holiday quarter. For a stock trading near its highs on positive sentiment, falling short of the whisper while demand cools makes this a quarter of consolidation rather than a new leg up.
Read our earnings preview for Williams-Sonoma, Inc.: https://www.earningswhispers.com/article/WSM/23195
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 45 min | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| 8 hours | |
| 9 hours | |
| 12 hours | |
| Nov-18 | |
| Nov-16 | |
| Nov-15 | |
| Nov-12 | |
| Nov-12 | |
| Nov-05 | |
| Oct-26 | |
| Oct-23 |
