Construction Partners Misses As Wet Weather And Diesel Break The Margin Story, Though Its FY27 Growth Guide Holds
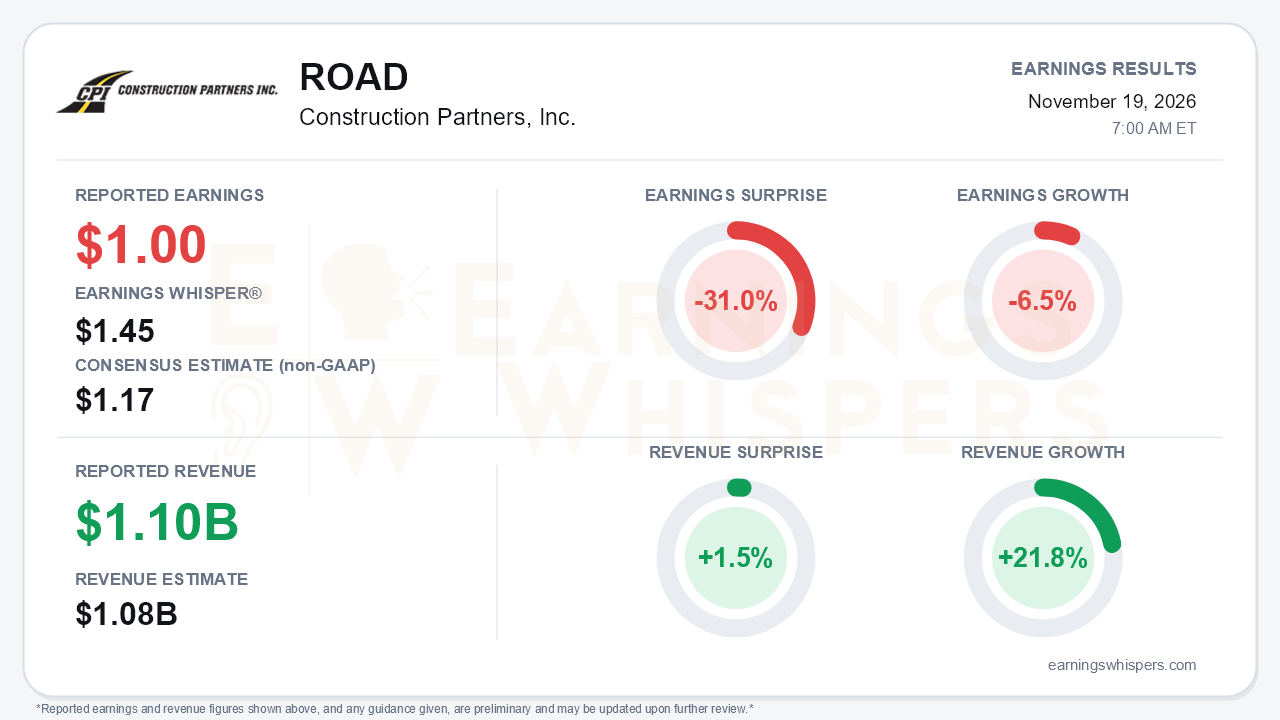
Construction Partners delivered a top-line beat and a profit miss in its fiscal fourth quarter. The miss broke the margin-expansion narrative that had carried the stock through most of 2026. Fourth-quarter earnings were $1.00 per share. That was below the $1.17 consensus and well short of the $1.45 Earnings Whisper number, a 31.0% shortfall. Earnings fell 6.5% from a year ago. Revenue was a record $1.096 billion, up 21.8% year over year and 1.5% above consensus. Note the basis: the $1.00 is GAAP diluted EPS, while consensus was set on a non-GAAP basis. The gap was too wide, though, to explain away as an accounting artifact. CPI is still growing volume, but it converted far less of that volume into profit than investors had been told to expect.
The quality problem is visible in the income statement. Fourth-quarter gross profit rose only about 7%, to $170.0 million, on 22% revenue growth. G&A climbed to $68.7 million from $57.3 million, and net interest expense rose to $28.7 million from $25.4 million. Net income was essentially flat at $56.2 million. The full-year comparison is harsher:
- Adjusted EBITDA came in at $523.5 million, against the $559-569 million guided as recently as the third quarter.
- Adjusted EBITDA margin was 14.2%, versus guidance of 15.35-15.46% and down from 15.1% in fiscal 2025.
- Net income was $142.1 million, against a $165-168 million target.
The headline 31% annual revenue growth and 40% net income growth flatter a year in which profitability was guided up three times and then fell sharply short. CPI had pre-announced preliminary ranges in early November, so the miss itself was not news on report day. That is consistent with shares setting a 52-week low of $74.51 on November 5.
Management blamed the shortfall primarily on a very wet July and early August. A roughly 40% diesel spike beginning in mid-August was the secondary cause. The more consequential change is in the forward framing.
- **Margin outlook:** The fiscal 2027 outlook calls for a 14.0-14.5% adjusted EBITDA margin. That is below the roughly 15.4% fiscal 2026 target management carried all year, and it abandons the 30-40 basis point annual expansion cadence cited at the third quarter. Management now says margins will fluctuate.
- **Acquisition mix:** Recently acquired businesses carry lower-margin backlog, a return to CPI's typical deal dilution after the accretive Lone Star and Durwood Green transactions.
- **Backlog:** Backlog slipped to $3.29 billion from the $3.36 billion record at the third quarter, though it remains above the $3.03 billion of a year ago. Next-twelve-month coverage dipped to 75-80% from 80-85%.
- **Cash conversion:** Conversion ran about 66% of EBITDA, against the 75-85% guided all year.
- **Leverage:** Leverage rose to 3.24x from 3.17x. The roughly 2.5x target once promised by late 2026 was missed, with no new date given.
The call still preserved a credible growth story. The fiscal 2027 guide calls for $4.175-4.275 billion in revenue and $585-620 million in adjusted EBITDA, roughly 15% growth in both, with 6-8% organic growth. Acquired revenue carrying into fiscal 2027 is now $280-300 million, double the roughly $140 million cited last quarter. Three deals closed in the first weeks of the new fiscal year, adding $65 million of backlog and $100-110 million of expected revenue. Those deals also brought vertical-integration assets: a fourth liquid asphalt terminal and an aggregates rail terminal. Operating cash flow rose 18% to $344 million, and capex is budgeted up to $210-230 million.
Management's margin-recovery thesis rests on the second half of fiscal 2027. It expects two drivers to rebuild margins, as happened in 2022:
- burning off lower-margin acquired backlog;
- passing elevated diesel costs through project pricing.
Texas data center work and discounted winter-fill asphalt purchases add optionality. The risks are real, however. The federal funding tone turned noticeably more cautious. Last quarter, management pointed to committee momentum behind the Build America 250 Act; after an election surprise, it now leans on continuing-resolution history. Bears have legitimate ammunition in a leveraged roll-up whose deleveraging timeline has slipped and whose margin guidance was just reset lower.
The market had largely priced this in before the report. Shares closed at $78.05 heading into the release. That is 29.2% below the $110.20 open after the August report, 36.8% under the August 12 high of $123.46, and 28.6% below the 200-day moving average. The stock sat just 4.8% above its November low. Investor sentiment deteriorated meaningfully, from roughly neutral at -0.04 to a clearly negative -0.34. That shift reflects a credibility hit rather than a collapse in demand. Earnings Whispers price and AVWAP trend readings remain negative, though momentum has turned positive off the lows.
The bottom line is that CPI's revenue engine and acquisition machine are intact, but the quarter replaced a steady margin-expansion story with a 'trust us on the second half' story. With leverage elevated, cash conversion weak and federal funding less certain, the burden of proof now sits on management to show diesel recovery and backlog mix can lift margins back toward prior targets. The shares' steep discount reflects that skepticism, but it does not resolve it.
Read our earnings preview for Construction Partners, Inc.: https://www.earningswhispers.com/article/ROAD/23167
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 6 hours | |
| 9 hours | |
| 10 hours | |
| 11 hours | |
| Nov-11 | |
| Nov-06 | |
| Nov-05 | |
| Nov-04 | |
| Oct-19 | |
| Oct-05 | |
| Sep-29 | |
| Sep-21 | |
| Aug-31 | |
| Aug-28 |
