Helmerich & Payne Beats As North America Strengthens, But A $610 Million Saudi Write-Down Lowers The International Outlook
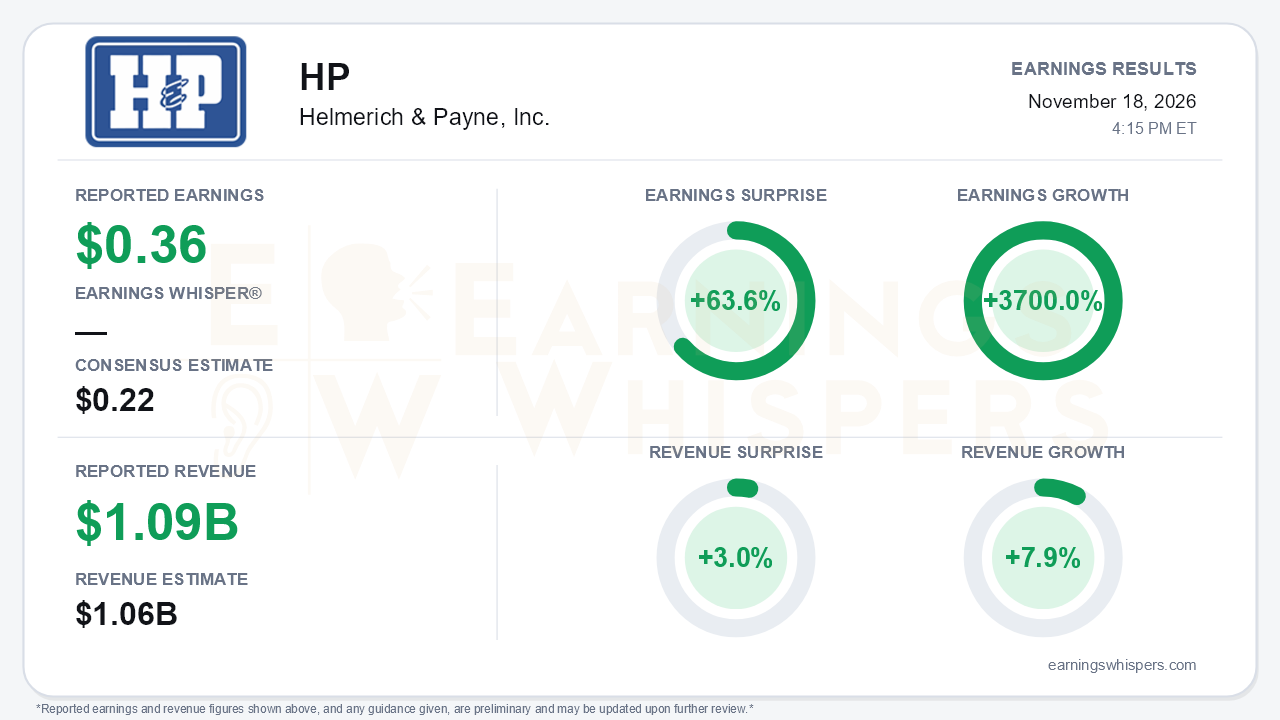
Helmerich & Payne closed fiscal 2026 with a clean operating beat. Its Saudi conventional fleet, however, carried a very different message. Adjusted earnings of $0.36 per share topped the $0.22 consensus by 63.6%. Revenue of $1.092 billion beat the $1.06 billion estimate by 3.0% and grew 7.9% year over year. Earnings grew 3,700.0% from a year-ago quarter that barely registered on an adjusted basis. More telling is the sequential swing: from an adjusted loss of $0.11 per share in the June quarter to a solid profit. On a GAAP basis, H&P lost $4.91 per share. A $610 million non-cash impairment, mostly tied to Middle East assets, accounted for $5.20 of that loss. That is the central tension: the operating engine is accelerating while part of the international asset base is being written down.
The quality of the beat holds up better than the GAAP figure suggests. Adjusted EBITDA reached $269 million, up 14% sequentially. That continues a climb from $178 million in fiscal Q2 and $236 million in Q3. Management said direct margins landed at or above the high end of guidance in every segment. Two caveats deserve mention. Full-year adjusted EBITDA of $913 million was still slightly below fiscal 2025's $934 million, even though management said it beat its start-of-year expectations. And the Offshore beat leaned on performance bonuses that are not assumed to repeat.
North America Solutions is the clearest improvement. Average rigs rose from 136 in fiscal Q2 to 142 in Q3 and 151 in Q4. Direct margin climbed to $259 million, above the $245-255 million guide issued last quarter. Margin per day held near $18,700 despite five reactivations, which suggests pricing discipline survived the ramp. The call also marked a shift in customer mix. Last quarter, rig additions were led by private operators while public operators churned. Now public operators are adding rigs, including a multi-rig contract running into 2028 at improved day rates. Super-spec utilization is roughly 95%. Management guided fiscal Q1 direct margin to $265-275 million and fiscal 2027 rigs to 145-155. The expanded FlexRobotics deployment to nine ExxonMobil rigs adds a technology angle to a cycle otherwise driven by pricing. Management's tone moved from cautious earlier in the year to "constructive," citing mid-single-digit 2027 upstream spending growth.
International results are where bears have legitimate ammunition. Segment direct margin did rise to $42 million, from $31 million in Q3 and $11.5 million in Q2. Argentina is moving toward 15 rigs, with talks about sending more, and Kuwait awarded two five-year contracts starting in 2028. But the Saudi picture reversed sharply. Last quarter, management spoke of 22 rigs with reactivations pending. Now it expects 19 in fiscal Q1 and warns of further declines. The 30-rig T-Series group took a $529 million impairment, and available international rigs dropped to 95 from 137 a year ago. Guidance calls for 55-65 rigs in fiscal Q1 and 50-60 for fiscal 2027, down from the 60-70 guided for Q4. Oman and Kuwait contract roll-offs create a trough in fiscal Q2 and Q3. Management does not expect to regain the long-promised $45 million quarterly margin run-rate until fiscal Q4.
The balance sheet story is steady rather than dramatic. Fiscal 2026 free cash flow was $254 million, and management expects fiscal 2027 to exceed that despite two headwinds. Capex rises to $320-360 million from $287 million, and cash taxes are guided to $180-220 million. Fourth-quarter free cash flow was only $46 million as reported. H&P retired its acquisition term loan early and plans to retire its 2027 notes. It is targeting roughly 1x net debt to adjusted EBITDA by calendar year-end 2027. Discussion of expanded shareholder returns has been pushed to 2028.
Investor sentiment shifted meaningfully. It rose from essentially neutral at 0.02 after the prior report to a moderately positive 0.31, reflecting growing confidence in the North American recovery. The stock has not followed. Shares were at $35.15 on the report date, down about 1.0% from the open after the August report, and roughly 6.3% below the $37.53 200-day moving average. The anchored-VWAP trend reading remains negative, consistent with a market that has not yet rewarded the operating rebound.
The bottom line is that H&P delivered a stronger quarter than its GAAP loss implies, and North America now has real momentum behind it. That includes rising rig counts, firmer pricing, public-operator demand, and higher margin guidance. The Saudi impairment and the reduced international rig outlook mean the consolidated growth story will run through a mid-year international trough. Offshore is also likely to flatten without bonuses. Investors are more optimistic than they were three months ago. The stock's position below its 200-day average shows the market still wants proof that North American strength can outrun the Middle East reset.
Read our earnings preview for Helmerich & Payne, Inc.: https://www.earningswhispers.com/article/HP/23136
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-18 | |
| Nov-18 | |
| Nov-18 | |
| Nov-18 | |
| Nov-10 | |
| Oct-14 | |
| Oct-07 | |
| Oct-07 | |
| Aug-20 | |
| Aug-05 | |
| Aug-05 | |
| Jul-20 | |
| Jul-15 | |
| May-26 |
