Copa Beats As Fares Outrun Fuel, But A Second Margin Cut Keeps Earnings Growth Flat
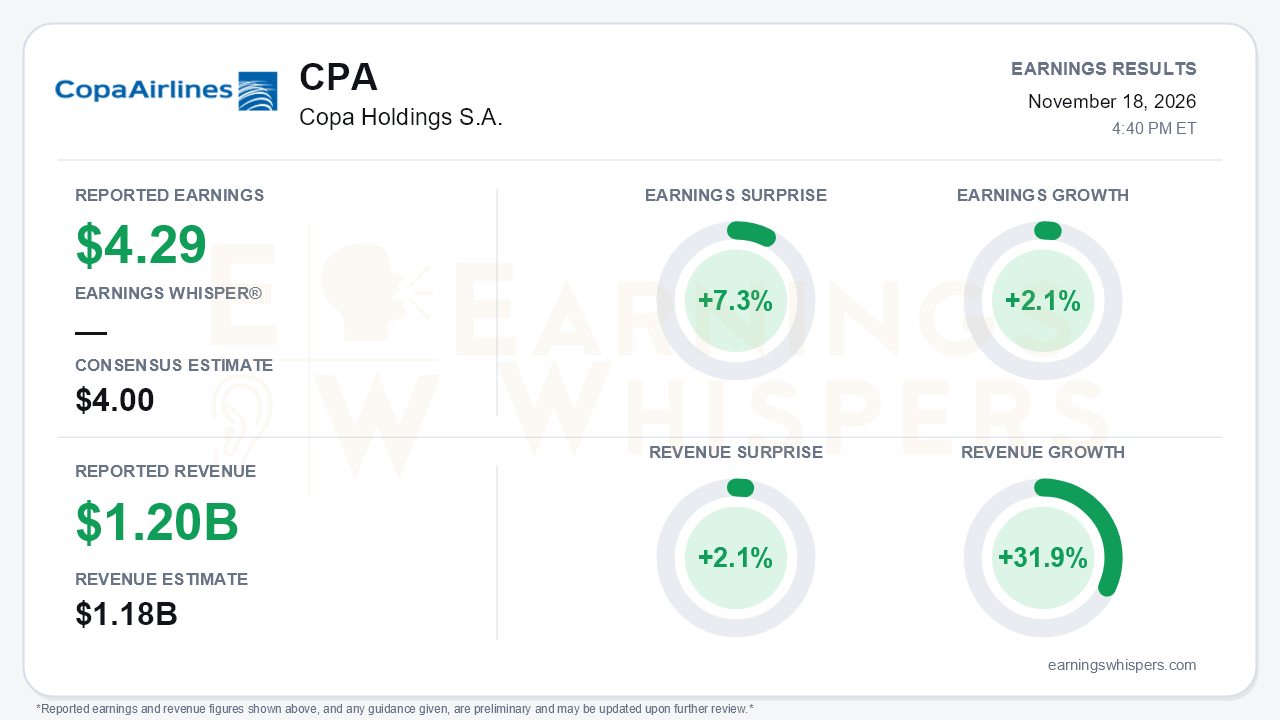
Copa Holdings beat third-quarter expectations, but the bigger story is that rising fares are only just keeping pace with rising fuel costs. The carrier earned $4.29 per share against a $4.00 consensus, a 7.3% surprise. Revenue of $1.204 billion topped the $1.18 billion estimate by 2.1% and grew 31.9% year over year. Yet earnings grew just 2.1% (the company cites 2.2% on its basic EPS calculation). Revenue up nearly a third and profit up 2% is the central tension. Management also cut full-year operating margin guidance for the second straight quarter, to 16-17%. The beat demonstrates pricing power, not earnings expansion.
The quality of the quarter is better than the flat EPS suggests, but it deserves scrutiny.
- **Fuel:** The average price per gallon rose 61.5% to $3.94, and fuel expense jumped 83.6% to $434.7 million.
- **Margins:** Operating margin compressed to 18.6% from 23.2%, and net margin fell 4.4 points to 14.6%.
- **Profit:** Operating profit still rose 5.7%. Pretax profit gained only 0.9% because non-operating expense roughly doubled, including a $5.7 million currency loss.
- **Share count:** A 0.8% lower share count helped EPS outgrow net profit, which rose 1.4%.
Sequentially, though, the picture is much stronger. Operating margin recovered from 8.7% in the second quarter. Copa recaptured roughly 86% of the fuel increase through fares, versus about 40% last quarter. Cost discipline outside fuel held: ex-fuel CASM was 5.7 cents, up only 1.1%.
The call preserved a credible demand story, and unit revenue is accelerating sharply.
- **Unit revenue:** RASM rose 13.5%, after gains of 7.9% in the second quarter and 2.7% in the first. Yield climbed 13.8%.
- **Capacity:** Load factor reached 88.7% even as capacity grew 16.3%.
- **Demand:** Management described demand as strong across all regions, with no weak performers and Brazil solid.
- **Raised assumptions:** The full-year RASM assumption rose to 12.3-12.4 cents from about 12.0. The load factor assumption rose to 87.5%, and 2026 capacity growth was narrowed to about 14.5%.
- **Pricing durability:** Management argued fares should prove sticky if fuel retreats, since they sit only about 5% above 2019 levels in nominal terms. With the fourth quarter mostly booked, any fuel relief would flow to margin.
That is the bull case's best argument: the revenue engine has been reset higher, and fuel is the variable.
The guidance math shows why bears have legitimate ammunition.
- **Margin trajectory:** Full-year operating margin guidance now sits at 16-17%, down from 17-19% in August and an original 22-24%.
- **Fuel:** The fuel assumption rose to $3.90 per gallon from $3.60.
- **Currencies:** The ex-fuel CASM assumption moved up to 5.8 cents. Stronger Latin American currencies, chiefly the Colombian peso, are inflating the 15-20% of costs incurred locally. Adjusted ex-fuel CASM rose about 1.7%.
- **Earthquake:** The outlook absorbs an estimated $12-14 million hit from an October earthquake. The release attributes the disruption to runway inspections at Panama's Tocumen hub, which led to about 295 cancellations. The call analysis references a different airport. Either way, the cost is embedded in guidance.
The first look at 2027 is mixed.
- **Growth slows:** Capacity growth decelerates to 8-9% from about 14.5%.
- **Costs hold:** Ex-fuel CASM is targeted at 5.7-5.8 cents.
- **Catalysts:** Twelve 737 MAX 8 deliveries are planned. The hub moves from six to eight connecting banks in March 2027. Seat densification is now complete, and Starlink rollout continues.
- **Boeing risk:** Boeing holding production at rate 47 through the first half of 2027 introduces delivery-delay risk. Management says this would affect year-end fleet count more than 2027 capacity.
The balance sheet remains a clear strength. Liquidity is about $1.6 billion, net debt to EBITDA improved to 0.8x, and a $1.71 quarterly dividend was ratified. No shares were repurchased in the quarter, leaving about $59 million authorized.
Investor expectations cooled heading into the print. Earnings Whispers sentiment slipped from modestly positive (0.10) to modestly negative (-0.15). That is a meaningful shift in direction, though not an extreme reading. The stock reflects the same caution. At $133.33, shares are 6.4% below the $142.49 open following the August report and sit almost exactly on their 200-day moving average of $133.49. The market has neither rewarded the RASM acceleration nor capitulated on the margin cuts. The internal trend readings are mixed, with price trend positive while AVWAP remains negative.
The bottom line is that Copa delivered a clean beat built on genuinely accelerating pricing and demand. However, fuel and currency costs are absorbing nearly all of that top-line strength, and the full-year margin target has now been cut twice. With growth slowing in 2027 and sentiment turning negative, the debate shifts to whether sticky fares can convert any fuel relief into real earnings growth. That outcome is plausible but not yet visible in the guidance.
Read our earnings preview for Copa Holdings S.A.: https://www.earningswhispers.com/article/CPA/23135
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Nov-18 | |
| Nov-18 | |
| Nov-12 | |
| Nov-10 | |
| Oct-15 | |
| Oct-08 | |
| Sep-10 | |
| Aug-31 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-14 | |
| Jul-08 |
