Star Bulk Misses A High Bar As Dry Bulk Earnings Plateau And Management Turns Cautious On 2027
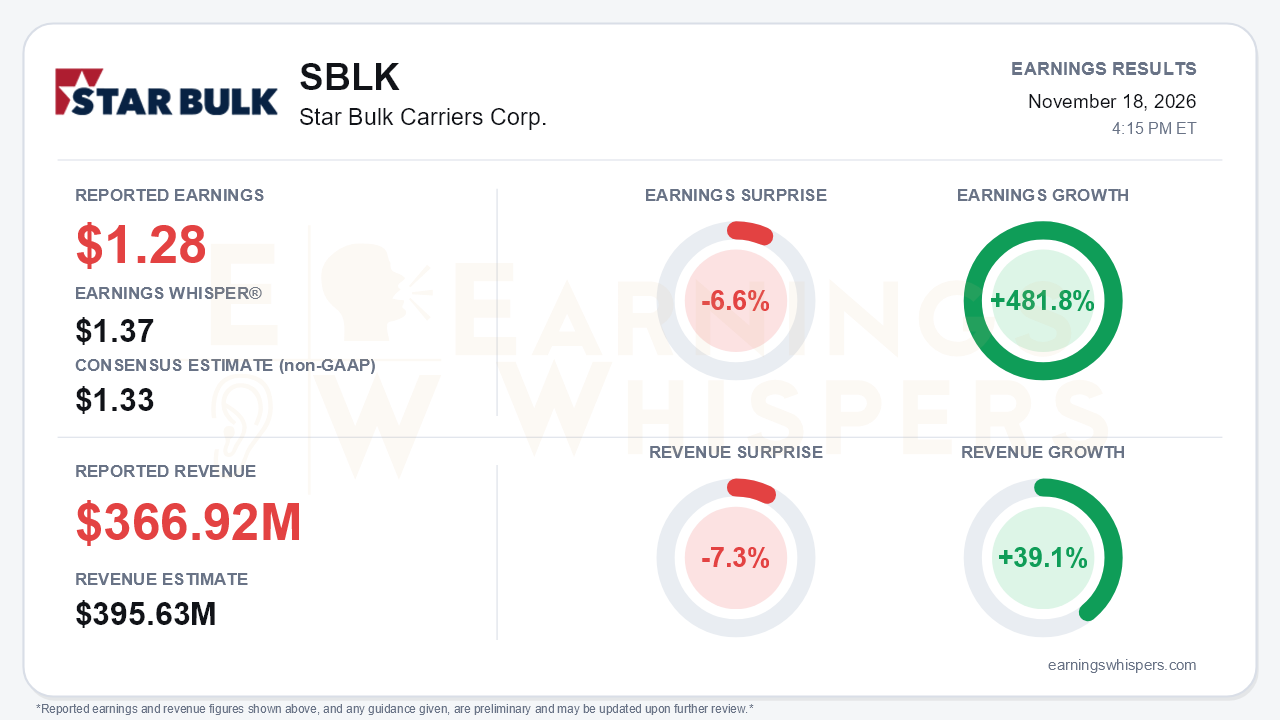
Star Bulk Carriers delivered one of its strongest quarters of the cycle and still fell short of what the market had priced in. Adjusted earnings of $1.28 per share missed the $1.33 consensus by 6.6% and came in well below the $1.37 Earnings Whisper number. Revenue of $366.92 million missed the $395.63 million consensus by 7.3%. On a year-over-year basis the numbers are striking: earnings grew 481.8% and revenue grew 39.1% against a weak third quarter of 2025. Sequentially, though, the story is very different. Adjusted EPS rose only modestly from $1.21 in Q2, after jumping from $0.52 in Q1. The steep part of the earnings recovery appears to be over. That is the central tension: record-in-cycle profits, a higher dividend, and a pristine balance sheet, set against forward indicators that have stopped improving.
The composition of the quarter reinforces that read. Revenue growth came entirely from rates. The fleet averaged 134.8 vessels versus 141.4 a year earlier, and the fleet-wide TCE rose to $24,616 per day from $16,634. However, that figure was barely above Q2's $24,486, so the rate tailwind that powered 2026 has flattened. Some of the year-over-year earnings leverage also came from items that do not compound:
- Dry docking expense fell to $17.1 million from $28.1 million because fewer vessels went through surveys.
- Interest costs dropped to $12.5 million from $17.7 million as debt and borrowing rates declined.
The GAAP figures tell the same story. Net income of $141.9 million was slightly below Q2's $144.9 million, and GAAP EPS was $1.26 against the adjusted $1.28. The small gap reflects a $4.1 million gain on vessel sales that was excluded from adjusted results, partly offset by share-based compensation that was added back. Cost discipline remains a genuine strength. Adjusted daily opex was steady at $5,171, which management pegged at 16-25% below peers, and daily cash G&A fell to $1,260.
The conference call preserved the near-term story but softened the outlook beyond it. Q4 is 75% fixed at $25,713 per day, above Q3's realized rate, so another solid quarter looks reasonably well underwritten. Beyond year-end, management's own markers slipped:
- The next-12-month freight futures curve the company uses eased to about $21,000 per day from about $22,000 last quarter. That ends a progression that had run from $18,500 to $20,500 to $22,000.
- Implied free cash flow per share slipped to roughly $4.0 from $4.1.
- Third-quarter dry bulk export volumes fell 1.5% year over year after first-half growth above 3%. Coal fell 5.7%, grain fell 4.9%, and fertilizer fell 18.5%.
- 2027 demand growth is projected at just 1.6%.
The tone shift was explicit. Earlier in the year management described the next 18 months as very positive; the CEO now expects 2027 to be "decent, maybe not as good as 2026."
Supply is where bears have the most legitimate ammunition. Newbuild contracting is at a 13-year high, and the orderbook has climbed to 15.7% of the fleet from 13.2% in Q1. Management expects 2027 fleet growth of 4.3% against ton-mile growth of 3.3%, an explicit supply-demand gap. On the other side are real supports:
- Guinea bauxite exports rose 35% year over year, and the Simandou iron ore ramp is lengthening Capesize voyages.
- U.S.-China port fees have been suspended to January 10, 2027, although that suspension has a defined expiry and is not a permanent resolution.
Capital allocation remains simple and shareholder-focused. The dividend rose to $1.00 from $0.90, the 23rd consecutive payout, and nine-month dividends now total $2.40. Cash of $766 million leaves net debt at just $275 million, below the fleet's demolition value. The eight-ship Kamsarmax newbuild program is complete and fully financed, and the Hermes partnership monetized 35% of two of those vessels for about $24.6 million. Management noted that high asset prices are limiting deployment beyond dividends. That is disciplined, but it also means growth from here depends on rates rather than fleet expansion.
Investor expectations have already cooled considerably. Earnings Whispers sentiment swung from a modestly positive 0.198 at the prior report to -0.147, a meaningful shift into negative territory. As of the report date, the shares were $26.65, down 9.7% from the $29.50 open after the August report. That also puts them below the $28.27 per-share price of the September Athens offering. The stock is sitting almost exactly on its 200-day moving average of $26.85, 0.7% below it. AVWAP readings are negative while the price trend is neutral, consistent with a stock that has drifted rather than collapsed. The market had begun discounting a peak before this report confirmed the plateau.
The bottom line is that Star Bulk's quarter was strong in absolute terms but disappointing against a high bar. Sequential growth has stalled, and the forward rate curve, demand data and supply outlook all moved the wrong way. The dividend, the Q4 bookings and the balance sheet give shareholders a cushion. Still, the investment case has shifted from riding an improving cycle to collecting cash from a cycle that management itself now expects to soften in 2027.
Read our earnings preview for Star Bulk Carriers Corp.: https://www.earningswhispers.com/article/SBLK/23141
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-19 | |
| Nov-18 | |
| Nov-18 | |
| Nov-10 | |
| Nov-10 | |
| Nov-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-01 | |
| Sep-22 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-11 | |
| Sep-11 |
