Youdao Stays Profitable, But Q3 Revenue Turns Lower In All Three Segments
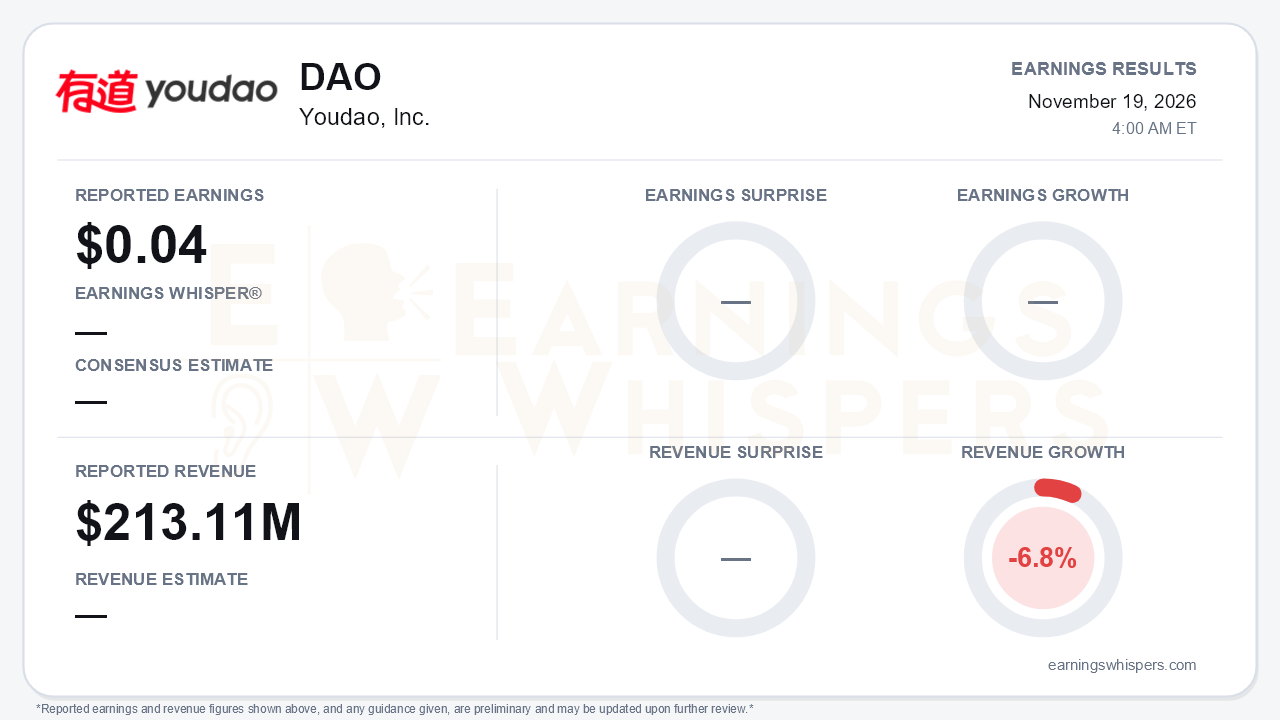
Youdao's third quarter showed a company protecting profitability while its top line reversed. The company reported GAAP earnings of $0.04 per ADS on revenue of $213.11 million. On a normalized basis, revenue fell 6.8% year over year. In local currency the decline was steeper: RMB revenue fell 12.3% to RMB1.43 billion. The gap appears to reflect dollar translation, and the RMB figure better describes the operating trend. No consensus estimate was available, so the quarter cannot be framed as a beat or a miss. The more important story is the trajectory. Revenue growth slowed from +16.8% in Q4 2025 to +3.8% in Q1 and +3.5% in Q2, then turned to -12.3% in Q3. Learning services, smart devices and online marketing all declined.
Profit improved on the surface. GAAP net income attributable to shareholders was RMB33.4 million, compared with essentially zero a year ago. Non-GAAP EPS was RMB0.38, up from RMB0.08. Operating income rose 19.2% to RMB33.7 million, and operating margin widened to 2.4% from 1.7%. The quality of that improvement deserves scrutiny, however.
Operating profit fell sharply from Q2's record RMB111.5 million. The year-over-year gain came mainly from cost cuts:
- Sales and marketing expense fell 13.4%, largely because device marketing was scaled back.
- R&D expense fell 7.4% on lower headcount.
- Interest expense dropped to RMB9.5 million from RMB15.4 million.
Below the operating line, other factors flattered the result. A RMB10.1 million loss attributable to noncontrolling interests lifted shareholder net income well above consolidated net income of RMB23.3 million. A near-zero tax charge helped as well.
Margins were the bright spot, and management leaned on them. Online marketing gross margin rose to 29.6%, up from 28.7% in Q2 and 25.4% a year ago. Learning services gross margin improved to 59.7% from 58.5%. Smart-device gross margin recovered to 41.0%, meeting management's earlier target of more than 40% for the second half. Even so, it remains well below last year's 50.3% because of higher bill-of-materials costs.
The revenue side is where the setup weakened:
- **Learning services** swung from +20.9% growth in Q2 to a 5.2% decline. Management attributed this to summer enrollment pulling demand forward. That explanation is plausible, but it puts pressure on the roughly double-digit full-year segment growth management outlined earlier.
- **AI subscriptions** grew more than 20%, down from more than 70% in Q1 and more than 80% in Q4 2025.
- **Contract liabilities**, a forward indicator for learning revenue, fell to RMB771.8 million from RMB835.1 million in Q2.
- **Online marketing** fell 8.8%, its second straight decline. Management cited a tough gaming comparison and a deliberate focus on higher-ROI clients.
- **Smart devices** dropped 40.9% on weaker demand.
Management's tone shifted from Q2's language of record results and solid momentum to a promise that the business "will return to growth in the near future."
The catalyst list is long but early-stage:
- Euler, an AI math tutor, launched with physics to follow.
- Lobster AI passed 1 million users and released a second version.
- Hi-Echo sales more than doubled for a third straight quarter.
- Youdao became an inaugural partner in YouTube's Creator Support Program, and its Yoda influencer-marketing agent is in trials.
- Ad revenue from AI apps, short drama, financial services and auto advertisers each grew more than 50%.
These are real signs of product activity. None yet offsets the contraction in the core segments.
The balance sheet is the risk bears will emphasize. Cash and investments fell to RMB599.8 million from RMB849.3 million at the end of Q2. Q3 operating cash outflow widened to RMB89 million. The release continues to include going-concern language that depends on financial support from NetEase. Youdao still carries a RMB748 million short-term loan from NetEase and has a shareholders' deficit.
There are offsets. Nine-month operating cash flow was positive at RMB152.1 million, compared with an outflow a year earlier, and roughly RMB230 million of parent loans were repaid. Nine-month operating income of RMB202.7 million is also ahead of last year's RMB161.1 million. That supports management's statement that it remains confident in meeting full-year objectives for operating profit and cash flow.
Market context is limited. Investor sentiment readings and a current share price were not available for this report. Shares opened at $16.85 after the August report. The 200-day moving average stands at $13.62, which gives a reference point for how much of the prior optimism may still be in the stock as investors absorb a quarter that challenged the growth narrative.
The bottom line is that Youdao delivered profitability without growth. Expanding margins and cost discipline kept earnings positive, but revenue declined in every segment and AI subscription growth slowed sharply. Q4 now needs to show that the learning-services weakness was timing rather than demand, and that the full-year profit and cash-flow commitment holds.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 13 hours | |
| 18 hours | |
| 18 hours | |
| Nov-05 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-19 | |
| Aug-06 | |
| May-21 | |
| May-21 | |
| May-21 | |
| May-07 | |
| Apr-15 |
