Keysight's Record Quarter Beats Forecasts And Orders Keep Outrunning Supply, But The Stock Still Trades 27% Below Its October High
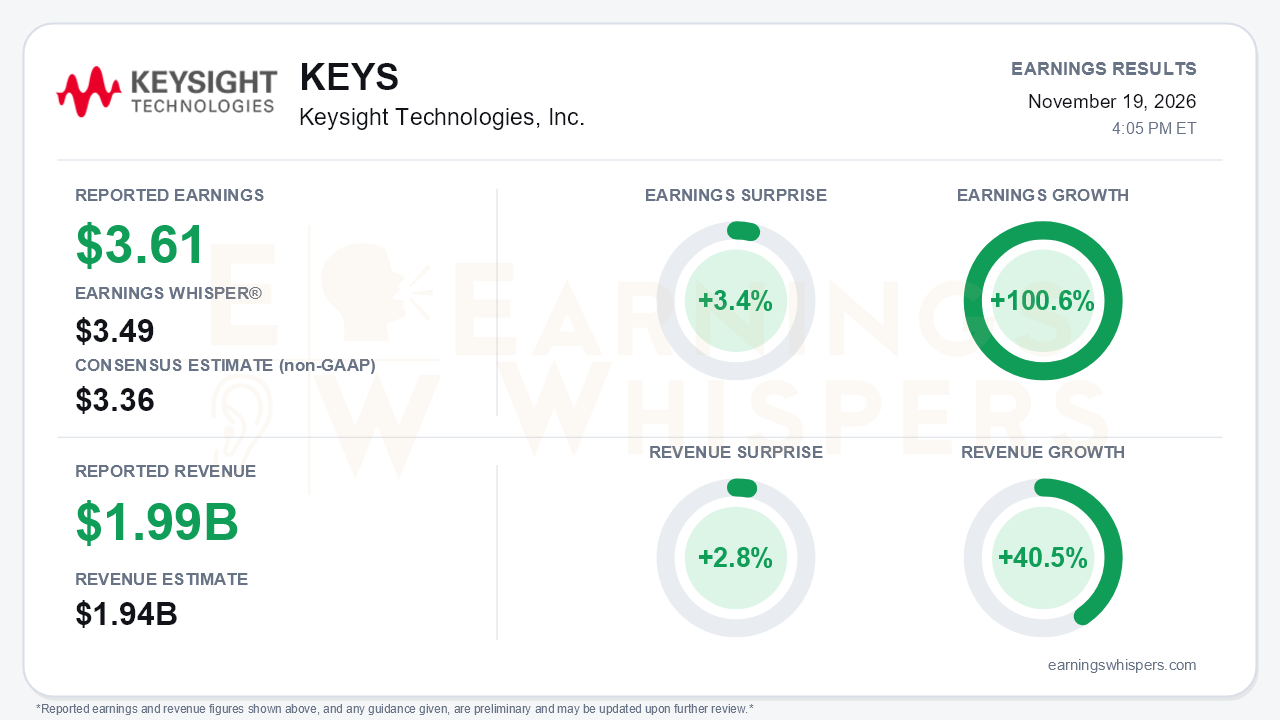
Keysight closed fiscal 2026 with a decisive beat and a fourth quarter that accelerated rather than plateaued. Non-GAAP earnings of $3.61 per share topped the $3.36 consensus by 3.4% and cleared the $3.49 Earnings Whisper number. Revenue of $1.994 billion beat the $1.94 billion consensus by 2.8%. Earnings grew 100.6% year over year on revenue growth of 40.5%. Results also cleared management's own guidance range of $3.34 to $3.40 per share and $1.93 to $1.95 billion in revenue. The central takeaway is that demand is not what limits Keysight's growth. Supply is. Orders hit a record $2.339 billion, up 53% and roughly $345 million ahead of revenue, and management said backlog has stretched $200 million to $300 million beyond normal growth because of constraints in a dozen to two dozen AI-related products.
The quality of the quarter holds up better than many high-growth beats. Commercial communications revenue jumped 73% to $1.145 billion, with wireline growing at a triple-digit pace. The Communications Solutions Group's operating margin widened from 27% to 37%. The Electronic Industrial Solutions Group was not left behind: it grew 16% and expanded its margin from 25% to 32%. GAAP earnings rose to $2.82 from $1.35, and the prior-year GAAP figure had been flattered by a $75 million investment gain. That means the improvement is not just an artifact of non-GAAP adjustments. Free cash flow more than doubled to $465 million, and cash reached $2.92 billion. The flags are modest. Some of the fiscal 2026 gross margin came from a one-time IEEPA tariff refund worth about 110 basis points, which will not recur. Receivables also swelled by $327 million for the year as revenue ramped.
The call showed momentum building quarter by quarter. Management raised its fiscal 2026 growth outlook at every stop, from just above 20% to the high 20s, then 32%, before finishing at roughly 33%. Non-GAAP operating margin climbed from 27.4% in the first quarter to 35.8% in the fourth. Several other indicators moved the same way:
- AI bookings were about 2.5 times the prior year, and the AI customer count nearly doubled.
- The 6G business doubled.
- Aerospace and defense posted record bookings.
- Automotive returned to growth.
- Acquired businesses reached the full $100 million in cost synergies, and their operating margin rose from 11% to 32%.
For fiscal 2027, management offered a 20% base-case growth outlook and guided to incremental operating margins in the mid-to-upper 40s, above its 40% long-term model. It also cited silicon photonics and co-packaged optics as emerging catalysts, with meaningful activity expected in 2027 and a larger inflection in 2028.
The guidance carries both a promise and a discrepancy. The press release guides first-quarter revenue to $2.04 billion to $2.06 billion and non-GAAP EPS to $3.63 to $3.69. That is consistent with the roughly 28% year-over-year growth cited on the call, and it was guided above estimates. The call analysis, however, records a $2.4 billion to $2.6 billion revenue figure. That range does not reconcile with the 28% growth rate or with the EPS guide, so the release figure appears to be the reliable one. Read that way, first-quarter EPS guidance is essentially flat with the fourth quarter. Management also expects orders to decline mid-single digits sequentially on seasonality, and the tariff tailwind disappears. Bears have legitimate ammunition beyond that:
- The software and services mix fell to about 33% from 40% in the first quarter as hardware outgrew it.
- Aerospace and defense revenue grew only 7% despite record orders.
- Acquisition revenue of $370 million slipped slightly below the $375 million target.
- The CFO is transitioning, from Neil Dougherty to Jason Kary.
- Capex rises to about $275 million from roughly $200 million to address the capacity constraints.
The market setup is more complicated than the surprise implies. Shares closed at $286.30 before the report, down 18% from the $349 open after the August release. That leaves them 10.8% below the 200-day moving average and 26.6% below the 52-week high of $389.93 set on October 6. The stock had rebounded 11% from its November 5 low of $257.93. Investor sentiment was essentially unchanged at a moderately positive 0.36. Expectations had cooled through the price rather than through investor attitude. Momentum and sequential-growth readings are positive, while price and AVWAP trends remain negative, which captures the gap between the business and the stock.
The bottom line is that Keysight delivered an accelerating quarter with record orders, expanding margins, and a credible 20% growth framework for fiscal 2027. Its biggest constraint is shipping capacity, not customer demand. The open questions are whether flat sequential EPS guidance, the lost tariff benefit, a falling software mix, and a CFO change justify the stock's deep pullback from October, or whether that drawdown has already priced in more caution than the fundamentals warrant.
Read our earnings preview for Keysight Technologies, Inc.: https://www.earningswhispers.com/article/KEYS/23181
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 7 hours | |
| 17 hours | |
| 18 hours | |
| Nov-17 | |
| Nov-12 | |
| Nov-11 | |
| Nov-10 | |
| Nov-09 | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-29 | |
| Oct-22 | |
| Oct-22 |
