Gap Inc. Beats On Cost Discipline, But A Third Straight Guidance Cut Shows A Weaker Holiday Setup
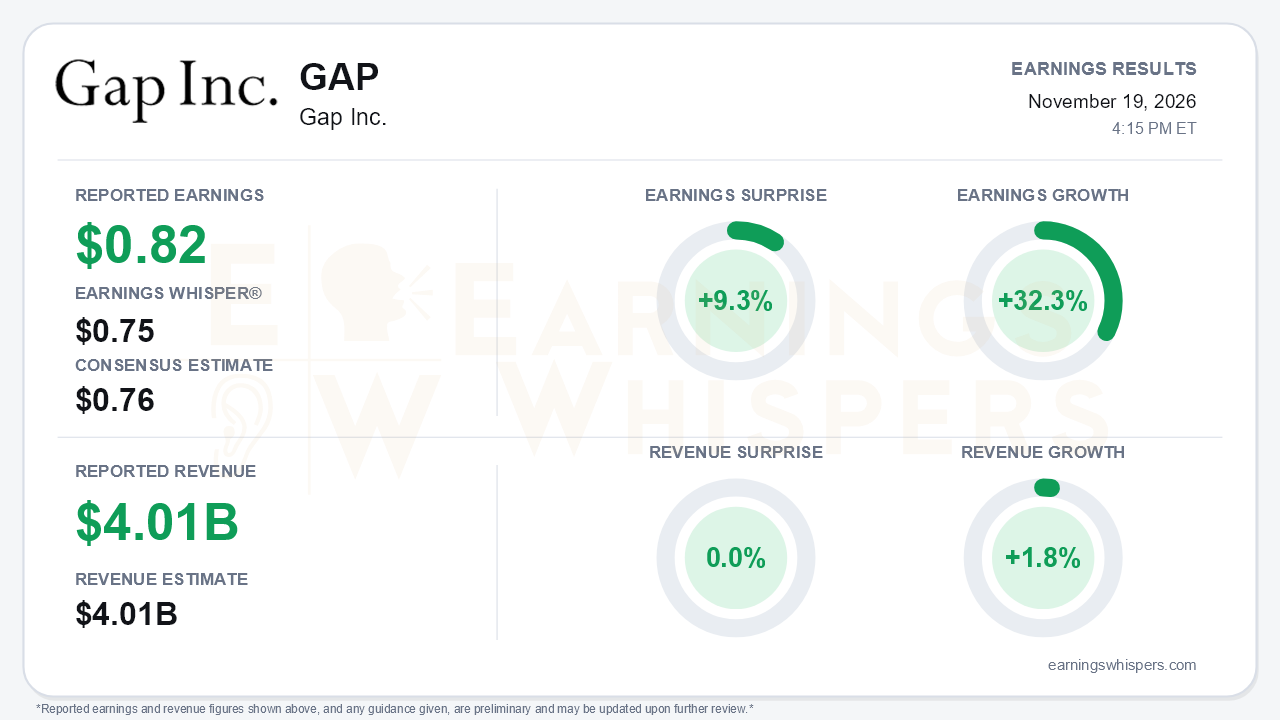
Gap Inc. delivered a clean-looking third-quarter beat. The guidance cut that came with it is more telling. Adjusted earnings of $0.82 per share topped the $0.76 consensus and the $0.75 Earnings Whisper number by 9.3%, and grew 32.3% year over year. Revenue of $4.011 billion matched the $4.01 billion consensus and rose 1.8%, a reversal from the roughly 2% decline in the second quarter. Management then cut its full-year outlook for the third consecutive time. It now expects roughly flat sales, an adjusted operating margin of about 7.2% and adjusted EPS of $2.29 to $2.34, down from $2.35 to $2.45. That is the central tension: a profit beat in the quarter that ended, and a weaker outlook for the quarter that matters most.
The quality of the beat deserves scrutiny. Gross margin did not drive it. Adjusted gross margin was flat at 42.4%, short of the 25 to 75 basis points of expansion management had guided after the second quarter. Merchandise margin rose 40 basis points on an adjusted basis. Strength at the Gap brand and lower tariff rates did the work, partly offset by planned price cuts and heavier promotions at Old Navy and Athleta. Occupancy costs also deleveraged 40 basis points. The 130-basis-point improvement in adjusted operating margin, to 9.8%, came from operating-expense leverage. Management attributed part of that leverage to a lower incentive-compensation accrual, which could become a headwind in 2027. Some franchise revenue was also pulled forward from the fourth quarter. GAAP EPS of $0.86 included tariff refunds and related interest income, which management excludes from adjusted results.
Beneath the consolidated flat comparable sales, the brand portfolio is diverging.
- **Gap:** Comparable sales rose 9%, the brand's 12th straight positive quarter, and management guided to high-single-digit growth again in the fourth quarter.
- **Old Navy:** Comparable sales improved to flat from -4% in the second quarter, against a demanding +6% comparison. Management credited better fall product and marketing, including Old Navy Sport and nationwide beauty.
- **Banana Republic:** Comparable sales flipped to -3% from +3%, as the women's fall assortment missed and demand for cold-weather categories arrived late.
- **Athleta:** Comparable sales worsened to -15%, from -12% in the second quarter and -11% in the first. Management now calls the brand a turnaround, with fourth-quarter trends even more challenged.
The company named Ashley Kechter, formerly of Vuori and Fabletics, as Athleta's president and CEO, and a comprehensive business review is underway.
The forward picture is where bears have legitimate ammunition. Management said apparel demand decelerated in October and early November during the warmest October in a decade. It also shifted its language from a "resilient" consumer earlier in the year to a "more pressured" one.
Fourth-quarter guidance reflects that shift:
- Sales flat to down 1%.
- Old Navy comparable sales down 1% to 2%.
- Underlying merchandise margin down about 50 basis points on promotions, with roughly 100 basis points of expense leverage partly offsetting.
The cut is also less flattering than it looks. The updated outlook already includes about $46 million, roughly 30 basis points of margin, of incremental tariff relief from lower assumed rates. Without that cushion, the reduction in underlying expectations would have been larger. Full-year adjusted operating margin is now expected to fall below fiscal 2025's 7.3%, a sharp retreat from the 2% to 3% sales growth envisioned at the start of the year. Management did say trends improved once temperatures cooled, which leaves some holiday upside if that improvement holds.
The balance sheet gives management room to absorb a soft season:
- Cash and short-term investments of $3.0 billion.
- Year-to-date free cash flow of $815 million.
- Inventory down 6%.
- $788 million returned to shareholders so far this year.
Much of that cash cushion is not operational, however. It includes about $536 million of tariff refunds and $263 million from a legal settlement.
The market had already priced in much of the disappointment. Shares closed at $19.84 before the report, down 19.6% from the open following the August release. That leaves the stock about 12.9% below its 200-day moving average and just 3.1% above the inter-earnings low of $19.25 set two days before results. The quarter's high of $25.80 came the session after the prior report, so the entire post-August rally has unwound. Investor sentiment improved modestly ahead of the report, moving from slightly negative to roughly neutral. That is a sign of tempered rather than enthusiastic expectations. Price and AVWAP trend readings remain negative, while sequential growth reads positive, a split that mirrors the gap between the quarter's results and the outlook.
The bottom line is that Gap Inc. delivered a credible quarter built on cost discipline, the Gap brand's sustained strength and a visible stabilization at Old Navy. The repeated guidance cuts, deepening trouble at Athleta and Banana Republic, and a more cautious read on the consumer limit how much the beat changes the story. With the stock already near its lows, holiday execution and the durability of the post-weather improvement will decide whether the reset expectations prove conservative or still too high.
Read our earnings preview for Gap Inc.: https://www.earningswhispers.com/article/GAP/23177
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 4 hours | |
| 5 hours |
Gap Cuts Outlook After Warm Fall Weather Weighs on Sales
GAP -5.29% GAP +3.61% AH
The Wall Street Journal
|
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 8 hours | |
| 18 hours | |
| 19 hours | |
| 19 hours | |
| Nov-17 | |
| Nov-11 | |
| Nov-10 | |
| Nov-10 |
