RLX Technology's European Acquisition Drives 80% Revenue Growth, But Margins Are Diluted And Operating Profit Shrinks
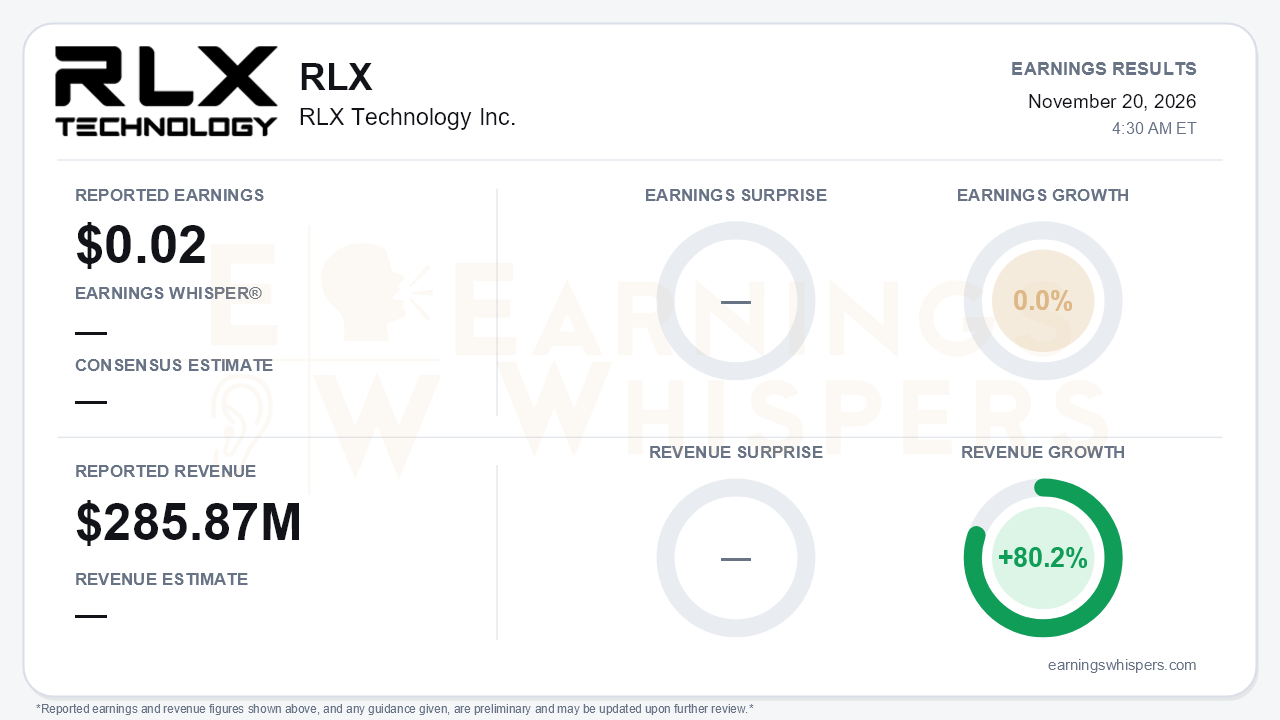
RLX Technology reported third-quarter earnings of $0.02 per share on revenue of $285.87 million. Revenue grew 80.2% year over year, and earnings were flat at 0.0% growth. There was no consensus estimate or Earnings Whisper number to measure the quarter against, so the assessment rests on the quality of the results. That quality is the central issue. Nearly all of the top-line jump came from consolidating a Western European distribution business acquired in July. That deal turned RLX into a much larger but structurally lower-margin company. The flat dollar EPS hides a decline in local currency. GAAP diluted earnings per ADS fell to RMB0.123 from RMB0.157, and non-GAAP diluted EPS dropped to RMB0.175 from RMB0.221.
The company reports in renminbi. On that basis, net revenue rose 69.7% to RMB1.92 billion, and revenue nearly doubled from the second quarter's RMB1.01 billion. Currency translation explains the gap with the 80.2% dollar-based growth figure. International markets now produce 86.5% of sales. The cost of that scale is visible throughout the income statement:
- Gross margin fell to 23.3% from 31.2% a year ago, and from roughly 35% in the second quarter. Gross profit rose only 26.7%.
- Operating expenses jumped to RMB407.1 million from RMB259.3 million.
- General and administrative costs more than doubled to RMB185.9 million, driven by salaries and legal and consulting fees.
- GAAP operating income collapsed to RMB39.5 million from RMB93.3 million a year ago and RMB130.4 million last quarter.
- Non-GAAP operating income fell to RMB143.8 million from RMB187.8 million. That puts the non-GAAP operating margin near 7.5%, versus more than 16% a year ago.
The bottom-line figures depend heavily on other sources of income. Net interest income of RMB96.8 million exceeded GAAP operating income. That interest stream itself is shrinking from RMB139.7 million a year ago as cash goes to dividends and M&A. A RMB13.6 million loss attributable to noncontrolling interests also lifted attributable net income above consolidated net income. That loss suggests the acquired unit was unprofitable at the minority-holder level this quarter.
The balance sheet shows how much the business model has changed. Since year-end:
- Inventories have nearly quadrupled to RMB1.13 billion.
- Receivables have more than tripled to RMB651.6 million.
- Payables have more than doubled.
- Goodwill and intangibles have grown to a combined RMB1.33 billion.
The deal also created RMB249.6 million of mezzanine equity, tied to put and call options over the remaining minority stake. Operating cash flow recovered to RMB40.0 million from an outflow of RMB63.2 million in the second quarter, which the CFO called a healthy sequential rebound. That is still far below the RMB357.5 million generated a year earlier, and year-to-date operating cash flow remains negative. Total financial assets slipped to RMB13.48 billion from RMB13.88 billion in June. That is still a large cushion, but it is steadily eroding.
The conference-call record adds a complication. The available transcript, though labeled third quarter, appears to repeat the first-quarter call. It cites first-quarter revenue of RMB1.59 billion and is introduced as the first-quarter call. It therefore contains no verifiable commentary on these results, so management's forward view must be pieced together from the press release and the prior call. On the second-quarter call, management guided mainland China sales to be broadly flat for the year. It also warned that gross margin would settle back and that the distribution business would dilute margin percentage. Both warnings proved accurate. The prior call also showed that the strong first quarter was inflated by a pull-forward ahead of April's export tax rebate cancellation, which reversed in the second quarter. Organic growth was already slowing before the acquisition reset the comparisons.
Going forward, management says it is lifting the European platform's margins through supply chain optimization and capital deployment. That is now the most important variable in the story. The October UK excise duty is a two-sided factor. Management frames UK regulation as a share-gain tailwind, but the CFO also flagged transitional working-capital needs tied to the duty, which could weigh on near-term cash flow. Heat-not-burn remains on hold, and there is no U.S. entry.
Market context is thin. No current sentiment reading or post-report price was available. Shares opened at $1.85 after the August report, below the 200-day moving average of $1.98. That suggests the stock entered this period without much market confidence in the strategic pivot.
The bottom line is that RLX bought growth, and the quarter shows the price. Revenue scale and international reach expanded sharply, but margins, operating profit, and per-share earnings in local currency all moved backward. Interest income from a shrinking cash pile is carrying a growing share of earnings. Bulls can point to a transformed route-to-market and a still-large balance sheet. Bears have legitimate ammunition in the margin dilution, the working-capital build, and soft organic trends in China. The thesis now depends on whether management can actually raise European margins.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 48 min | |
| 4 hours | |
| Nov-10 | |
| Aug-20 | |
| Aug-17 | |
| Aug-14 | |
| Aug-05 | |
| May-20 | |
| May-20 | |
| May-11 | |
| Apr-23 | |
| Mar-13 | |
| Mar-13 | |
| Mar-03 | |
| Dec-31 |
