Bending Spoons Crushes Adjusted Estimates And Lifts 2026 Outlook, But 3% Organic Growth Shows How Much Rides On The Deal Machine
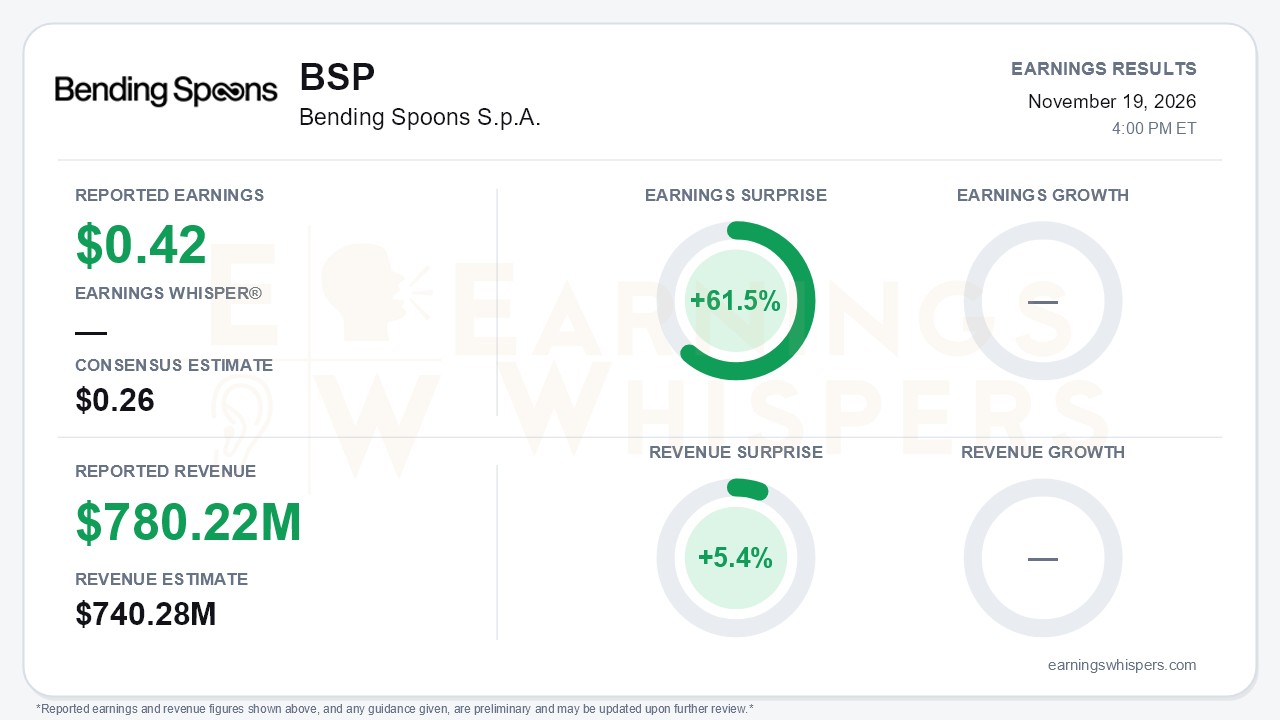
Bending Spoons (NASDAQ: BSP) delivered a large headline beat in its third quarter. Adjusted earnings were $0.42 per share against a $0.26 consensus, a 61.5% surprise. Revenue of $780.22 million topped the $740.28 million estimate by 5.4%. Management also raised full-year guidance well above the prior ranges. Underneath, though, this is a company growing almost entirely through acquisition. Organic revenue growth was just 3%, and GAAP diluted EPS slipped 3% year over year to $0.13. That gap between the acquisition-fueled headline and the modest core is the central tension of the quarter.
The quality of the beat deserves scrutiny. Revenue rose 125% year over year, but the company attributes that primarily to the businesses it has bought since mid-2025: Airtable, AOL, Eventbrite, Harvest, MileIQ, Tractive and Vimeo. Airtable alone contributed $38 million after closing on September 4, and the company's prior Q3 guidance of $733 million to $745 million excluded Airtable. Strip out that contribution and revenue lands near the top of the original range rather than far above it. Adjusted operating income of $424 million cleared the $380 million to $400 million guide more convincingly. The adjusted operating margin held at 54%, consistent with the prior quarter.
On a GAAP basis, the picture is far less flattering. Operating margin fell to 22% from 37% a year ago. The drivers were $189 million of acquired-intangible amortization, which included a $65 million catch-up charge for prior periods, plus about $62 million of reorganization, transaction and other charges. Interest expense jumped to $107 million from $41 million. Pre-tax income nearly halved to $47 million. Net income only grew because of a $43 million tax benefit that included a $57 million valuation-allowance release tied to Vimeo. Diluted share count rose 10%. Adjusted EPS also eased sequentially from the $0.46 reported for Q2.
A caveat about the call record: the conference-call material available for this quarter appears to duplicate the August Q2 call nearly word for word, and it contains no Q3 figures. The call therefore offers no reliable read on how management characterized this quarter, and any trend observations rest on the press release. The comparison with the prior call is still instructive.
- **Organic growth:** In Q2, organic growth had slowed to 3% from 6% in Q1. Q3 held at 3%, which is stabilization rather than reacceleration.
- **Sources of growth:** Tractive and WeTransfer led, partly offset by continued Remini declines. The prior call had tied Remini's weakness to AI commoditization.
- **Q4 outlook:** The Q4 guide implies 5% organic growth at the midpoint. If delivered, that would be the first real pickup in the core in several quarters.
- **Full-year guidance:** The 2026 range is now $3.07 billion to $3.09 billion in revenue, up from $2.78 billion to $2.82 billion, and $1.58 billion to $1.60 billion in adjusted operating income, up from $1.46 billion to $1.51 billion. Management attributes the raise both to a stronger outlook for existing businesses and to Airtable and Miro.
The forward story is dominated by capital deployment. After quarter-end, the company:
- closed Miro for $1.36 billion;
- agreed to buy Mailchimp from Intuit for $3.68 billion, its largest deal to date;
- raised $330 million from Berkshire Hathaway for 10 million shares, roughly $33 per share;
- agreed to a $1.30 billion placement at about $40 per share;
- added roughly $3.6 billion of new notes and term-loan add-ons.
Leverage improved to 2.1x from 2.4x last quarter, helped by IPO proceeds. However, that ratio relies on pro forma adjusted EBITDA that includes expected cost savings, and the new borrowing will push interest costs higher. Bulls can point to operating evidence that the playbook works. Tractive cut $10 million of annualized marketing waste, Vimeo is avoiding more than $7 million in hosting costs, and engineers are producing more than four times as many pull requests per engineer. Bears have legitimate ammunition in rising dilution, heavier debt service and integration capacity, which management itself flagged last quarter as a potential brake on deal pace.
Investor sentiment improved modestly, moving from slightly negative at -0.016 to slightly positive at 0.069. That is a shift toward neutral-to-constructive, not a surge of enthusiasm. The stock tells a cooler story. At $41.70, shares are down 11% from the open after the August report, though they remain about 5% above the 200-day moving average of $39.70. The AVWAP trend reading remains negative, consistent with a post-IPO stock that has struggled to hold earlier gains. The new private placement priced close to the current quote, which offers little evidence of a premium bid for fresh equity.
The bottom line is that Bending Spoons delivered a decisive beat on the metrics it emphasizes, and it raised guidance credibly. But the quarter is mainly a demonstration of acquisition scale, not organic acceleration. The adjusted numbers capture the margin discipline of the model, while the GAAP numbers capture its costs in amortization, interest and dilution. With Mailchimp and Miro now added, the next few quarters will test whether the implied 5% organic pickup materializes and whether integration keeps pace with a rapidly expanding, debt-funded portfolio.
Read our earnings preview for Bending Spoons S.p.A.: https://www.earningswhispers.com/article/BSP/23197
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-20 | |
| Nov-20 | |
| Nov-20 | |
| Nov-20 | |
| Nov-20 | |
| Nov-20 | |
| Nov-20 | |
| Nov-20 | |
| Nov-20 | |
| Nov-20 | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 |
