Matthews Beats Low Bar As Memorialization Shines, But New CEO Resets Timelines And Withholds Guidance
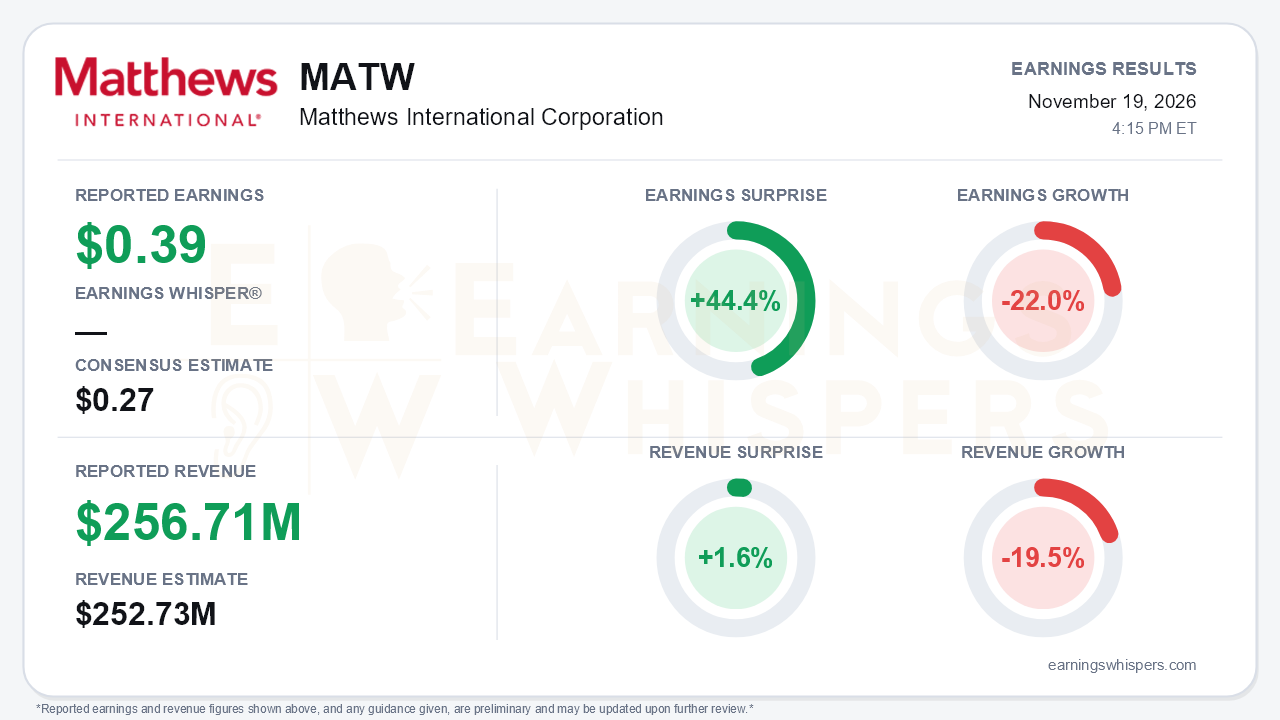
Matthews International delivered a clean-looking fiscal fourth-quarter beat that does little to resolve the bigger questions. Non-GAAP EPS of $0.39 topped the $0.27 consensus by 44.4%, and revenue of $256.71 million edged past the $252.73 million estimate by 1.6%. Both figures still fell sharply from a year ago: earnings were down 22.0% and revenue down 19.5%, largely because of divestitures. On a GAAP basis, the net loss narrowed to $0.62 per share from $0.88. The central tension is that the retained core, led by Memorialization, is performing well. Meanwhile, the growth stories meant to carry the next leg (Axion, the dry battery electrode business and the Propelis exit) all slipped further out. A new CEO used his first call to decline FY2027 guidance.
The quality of the beat deserves scrutiny. The gap between a $19.5 million GAAP loss and $12.3 million of adjusted net income was bridged by several add-backs:
- $0.34 per share of strategic initiative and other charges, including $9.9 million of Tesla litigation costs.
- $0.31 per share of Propelis amortization and other items.
- $0.18 per share of divestiture-related items.
Propelis also contributed $12.7 million of adjusted EBITDA, up from $7.4 million a year ago. That figure is reported on a one-quarter lag and reflects April through June. Excluding it, consolidated adjusted EBITDA of $46.5 million looks thinner. Still, the 18.1% adjusted EBITDA margin was up from 16.2%, and corporate costs fell roughly $2 million.
Beneath the headline, the operating picture splits cleanly in two. Memorialization grew sales to $214.6 million from $209.7 million and adjusted EBITDA to $47.0 million from $45.1 million. That capped a record year with roughly $177 million of segment EBITDA, ahead of the approximately $175 million target set in Q3. Orders and backlog are up, notably in cremation equipment, where a redesigned cremator line just launched. Industrial Technologies is the problem:
- Segment sales fell to $42.1 million from $93.0 million after the warehouse automation sale.
- Adjusted EBITDA swung to a $3.1 million loss from an $11.0 million profit, bringing the full-year loss to $16.3 million.
- Product identification was the bright spot, growing 14% and remaining profitable.
Sequentially, the quarter looked better. Consolidated adjusted EBITDA rose from $35.0 million in Q3, with every segment improving.
The forward-looking changes are where bears have legitimate ammunition:
- **Axion:** Meaningful revenue has been pushed to FY2028. In Q2, management had pointed to a more meaningful contribution next year.
- **Tesla dispute:** It is again framed as delaying customer capital commitments for the DBE technology, after Q3 commentary suggested the company was largely past that.
- **Propelis:** Synergy capture is slower, and the exit is now described as "in market in 2027," dependent on partners.
- **Full-year results:** FY2026 adjusted EBITDA of $161.5 million landed at the top of the reduced $158-162 million range but about $18.5 million short of the original "at least $180 million."
- **Cash flow:** Full-year operating cash flow was negative $58 million, versus negative $23.6 million a year earlier. Q4 did turn positive, but management had promised positive cash flow in both Q3 and Q4.
- **Debt:** Gross debt rose sequentially to $610.4 million from $567 million, even though it is down $100 million year over year and interest expense fell.
The catalysts are real but early. MioDio DBE mass-production testing began on schedule with multiple customers. New thermal inkjet and laser products drew Fortune 100 consumer-goods evaluations. Management cited adjacent bronze and aluminum casting opportunities and an ERP simplification aimed at corporate costs. The dividend rose to $0.26 from $0.255, the 33rd consecutive annual increase. CEO Michael Whitehead's "focus, simplify, drive" agenda points toward a leaner core. His continued review of strategic alternatives, which could include exiting or restructuring the engineering business, means the portfolio may look different again within a year.
Investors were already leaning skeptical, and that view hardened. Earnings Whispers sentiment fell from -0.24 to -0.52, a meaningful deterioration deeper into negative territory. The stock tells a similar story. At $19.37, shares are down 19.3% from the $24.00 open following the August report and sit about 20% below the 200-day moving average of $24.24. Price and AVWAP trend readings both remain negative. The market has been discounting the Industrial Technologies drag and the cash burn well before this report, and the beat gave it little new reason to change course.
The bottom line is that Matthews beat a modest bar on the strength of a record Memorialization business and a lagged Propelis contribution. However, the quarter shifted the investment debate toward execution credibility. Another round of pushed-out timelines, weak annual cash generation, higher sequential debt and no FY2027 guidance leave investors waiting for the new CEO's comprehensive plan on the next call. Until then, the steady core is carrying a portfolio whose growth options keep moving further into the future.
Read our earnings preview for Matthews International Corporation: https://www.earningswhispers.com/article/MATW/23182
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-20 | |
| Nov-19 | |
| Nov-18 | |
| Nov-11 | |
| Oct-30 | |
| Oct-01 | |
| Sep-17 | |
| Sep-04 | |
| Aug-21 | |
| Aug-11 | |
| Aug-10 | |
| Aug-06 | |
| Aug-06 | |
| Aug-04 | |
| Jul-29 |
