BJ's Wholesale Beats By A Wide Margin, But A Litigation Windfall Flatters A Quarter Of Real Traffic Gains
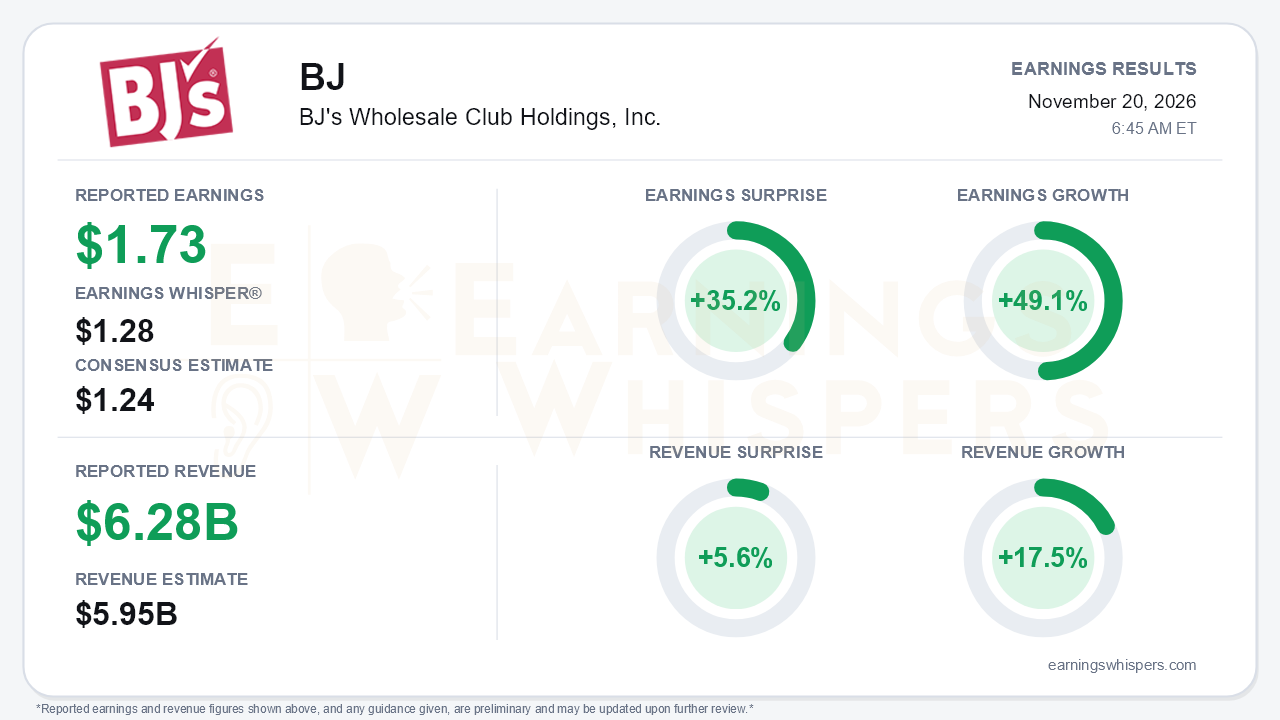
BJ's Wholesale Club delivered one of the larger upside surprises in its recent history. Fiscal third-quarter earnings came in at $1.73 per share, 35.2% above the $1.24 consensus and well ahead of the $1.28 Earnings Whisper number. Earnings grew 49.1% year over year. Revenue of $6.283 billion rose 17.5% and topped expectations by 5.6%, and management raised full-year guidance for the third time this year. The central tension is the quality of the beat. The quarter included roughly $240 million of pre-tax benefit, net of legal fees, from an interchange-fee litigation settlement. Adjusted EPS does not strip that out. Reported and adjusted EPS are identical at $1.73. Underneath sits a genuinely improving traffic story, but much of the earnings magnitude is not repeatable.
The income statement makes the distortion visible. Gross profit rose only about 1%, to $1.02 billion from $1.01 billion. Merchandise gross margin fell roughly 170 basis points, driven by the 42nd birthday promotion. Operating income still jumped 43.7%. The reason is that SG&A actually fell to $696.1 million from $788.2 million, because the settlement ran through that line. Management said it reinvested about $150 million of the windfall: roughly $95 million in SG&A and about $56 million in promotional margin. By rough math, that leaves something near $90 million of net pre-tax help, plus sale-leaseback gains. Revenue growth is also flattered. Total comparable sales rose 13.5%, but only 4.1% excluding gasoline. A roughly 4% lower diluted share count added a further lift to per-share growth.
The operating trends, however, are real and accelerating. Merchandise comps excluding gas improved from 1.5% in the first quarter to 3.1% in the second and 4.1% in the third, and traffic drove most of the gain. Comp traffic rose about 6% during the six-week birthday event, its best reading since 2020. General merchandise comps accelerated to 9.1% from 5.3%, and digitally enabled comps climbed to 38% from 30%. Comp gallons rose 10.6% against an industry decline of roughly 5%, and management cited unit outperformance versus the market of more than 500 basis points. Membership fee income grew 9.5% to $138.4 million. October brought more than 200,000 sign-ups, about 40% above the monthly average, and management raised its exit-rate growth target for fee income to about 7.5% from 6%. Membership is expected to pass 9 million in the fourth quarter.
The guidance raise deserves careful reading. Adjusted EPS guidance moved to $5.10-$5.30 from $4.60-$4.80, a $0.50 increase that roughly mirrors the size of the third-quarter beat rather than signaling a materially stronger fourth quarter. The ex-gas comp guide rose to 2.5%-3.0% from 2%-3%. With year-to-date comps at 2.9%, that range implies fourth-quarter growth at or below the recent pace. That is consistent with management's acknowledgment that the promotion likely pulled forward demand, especially in general merchandise. Other near-term drags management flagged:
- warm fall weather slowing winter apparel sales;
- $6 diesel;
- rising medical costs, with management raising the possibility of price increases.
The bigger risk is fiscal 2027. Next year must lap the settlement, first-half tariff refunds and unusually strong fuel profits, and management conceded the base will be difficult. It is also an open question how well the discounted members signed during the event will renew. Management is explicitly steering investors toward margin dollars rather than margin rate. The company says the rate was roughly flat excluding promotions, but bears have legitimate ammunition on that shift.
The longer-term catalysts remain credible:
- a roughly 20% SKU rationalization with further waves planned into the first half of fiscal 2027;
- higher Express Pay adoption;
- a club pipeline at the top of the 25-30 range for 2027-28, including the Bronx.
Year-to-date adjusted free cash flow reached $455 million versus $141 million. That figure was helped by payables timing, sale-leaseback proceeds and a purchase-option assignment. Buybacks slowed sharply to $35.6 million from $207 million in the first quarter.
The market had already anticipated a good quarter. Shares entered the report at $110.75, up 17.8% since the opening after the August release. That left them 15.8% above the 200-day moving average and just 2.3% below the 52-week high of $113.35 set on November 5. Most Earnings Whispers trend signals were positive heading in. Investor sentiment, by contrast, stayed negative and slipped slightly, to -0.22 from -0.19. That suggests investors were skeptical even as price advanced, and that skepticism maps neatly onto the windfall-versus-sustainability debate.
The bottom line is that BJ's delivered a quarter with two layers. The headline beat was magnified by a one-time legal settlement, a gasoline-inflated top line and a shrinking share count. Beneath that, traffic, membership and digital engagement are clearly improving. With the stock priced near its highs, the debate now shifts to whether the new members and traffic gains can carry earnings through a difficult fiscal 2027 comparison once the windfall is gone.
Read our earnings preview for BJ's Wholesale Club Holdings, Inc.: https://www.earningswhispers.com/article/BJ/23196
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 31 min | |
| 1 hour | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| 6 hours | |
| 7 hours | |
| Nov-18 | |
| Nov-17 | |
| Nov-16 | |
| Nov-15 | |
| Nov-06 | |
| Nov-05 | |
| Oct-30 |
