WeRide Posts Record Revenue And A 43% Gross Margin, But Flat Losses And Shrinking Cash Keep A Halved Stock On The Defensive
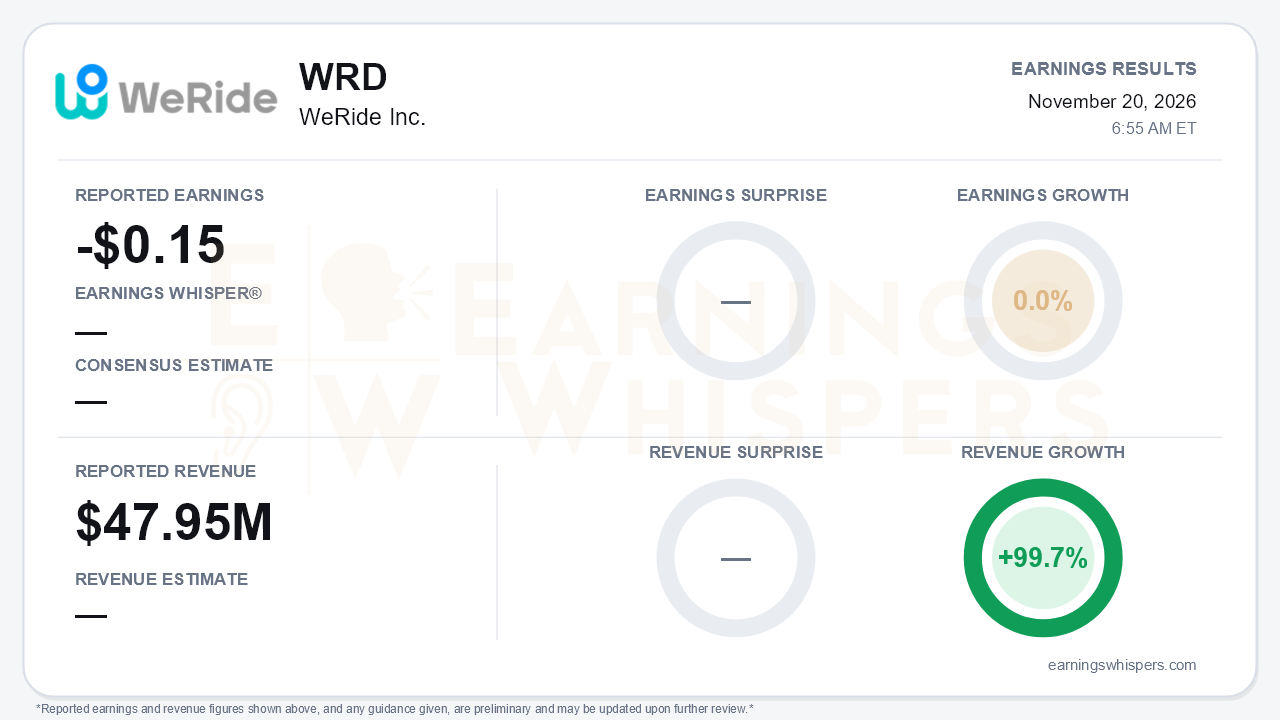
WeRide's third quarter was its strongest operating quarter to date, but the earnings line barely moved. The company lost $0.15 per ADS, with earnings growth of 0.0% year over year. Revenue was $47.95 million, up 99.7% in dollar terms. In its own reporting currency, WeRide put revenue growth at 88.0% to RMB321.5 million; the gap likely reflects translating RMB results into dollars. No consensus estimate was available, so the debate is about trajectory rather than a beat or miss. That trajectory is the central tension. The top line and gross margin are inflecting sharply, while the bottom line and cash balance tell a slower, costlier story.
The revenue and margin progress is real. Revenue climbed 38.8% sequentially, and Robotaxi revenue topped RMB100 million for the first time, up 204%. More than 90% of Robotaxi revenue came from overseas. Gross margin reached 43.0%, up from 37.5% in Q2, roughly 35% in Q1 and 28% in Q4'25. Overseas revenue, which carries higher margins, rose 171.5% to 45.7% of the total.
Below gross profit, the quality of the improvement deserves scrutiny. The reported loss of RMB310.0 million was essentially unchanged from RMB307.3 million a year ago. It looks better against Q2's RMB401 million, but administrative expense collapsed to RMB13.9 million from RMB100.4 million, largely because of a share-based compensation reversal tied to employee departures. R&D rose 47% to RMB465.3 million, and that was after a change extending the useful lives of IDC equipment, which lowered depreciation. Stripping out stock compensation and fair-value items, the adjusted loss widened to RMB336.5 million from RMB275.6 million a year earlier and was flat sequentially. EBITDA improved by just 2.9%. Gross profit more than doubled, but spending absorbed nearly all of it.
The call nonetheless preserved a credible growth story and added firm numbers. Management guided to its first explicit full-year figure: at least RMB1.1 billion in 2026 revenue, more than 60% growth and reportedly above Street expectations. With nine-month revenue at RMB667.4 million, that implies a fourth quarter of roughly RMB433 million or more, another substantial sequential step-up. Several operating catalysts support that outlook:
- Guangzhou reached positive unit economics.
- Management cited roughly 3,000 Robotaxis under binding contracts pending permits.
- The Middle East fleet is targeted at 800 to 1,000 vehicles by year-end, up from about 600, and is expected to roughly double in 2027.
- Spain granted its first national L4 passenger permit, with a Madrid launch targeted by year-end.
- L2++/L3 cumulative deliveries jumped from about 30,000 to more than 100,000, hitting the full-year target early, alongside 10 new design wins.
- The Jingshuo AI infrastructure unit nearly doubled revenue and cited several billion RMB of framework orders.
Bears still have legitimate ammunition, and most of it is on the balance sheet. Cash reserves fell to about RMB4.7 billion from RMB5.4 billion in Q2, RMB6.22 billion in Q1 and RMB7.13 billion at the end of 2025. Management attributed the roughly RMB700 million quarterly decline to working-capital timing. The balance sheet is consistent with that explanation but does not make it comforting. Since year-end, receivables rose to RMB588 million from RMB462 million and inventories to RMB501 million from RMB321 million, while short-term bank loans nearly doubled to RMB614 million.
Management guided 2027 cash burn to about RMB1 billion, claimed more than four years of runway, reiterated a first positive free-cash-flow quarter in 2028, and ruled out equity issuance at current valuations after more than $95 million of buybacks. Other cautions are worth noting:
- Management warned that the gross-margin mix benefit can vary quarter to quarter.
- Guangzhou daily orders per vehicle were flat at 21.
- L2++ pricing pressure from Chinese OEMs is intensifying.
- European competition from Waymo and other Chinese players is growing.
- Executive lockups expired on November 5.
The market had already rendered a harsh verdict heading into the print. Shares fell 47.9% from the $6.27 open after the August report to $3.27. They sit 47.6% below the 200-day moving average and just 2% above a $3.20 low set on November 19, which was also a 52-week low. That is nearly half the $6.49 inter-earnings high reached in late August. Investor sentiment deteriorated sharply, falling from -0.15 to -0.62. The Earnings Whispers trend readings lean negative on price and AVWAP, with momentum the lone positive. This was a stock being sold aggressively into a quarter that turned out to be operationally strong.
The bottom line is that WeRide delivered the operating evidence its bulls wanted: accelerating revenue, a fourth consecutive gross-margin increase, a first full-year guide above expectations, and a profitable Robotaxi city. What it has not yet shown is operating leverage. Adjusted losses are flat, the reported improvement leans on a stock-compensation reversal, and cash keeps falling. With the stock pinned near its lows and sentiment deeply negative, expectations are low. To change the setup, the fourth quarter likely needs to show that revenue scale is finally slowing cash consumption, not just raising gross profit.
Read our earnings preview for WeRide Inc.: https://www.earningswhispers.com/article/WRD/23198
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-20 | |
| Nov-20 | |
| Nov-20 | |
| Nov-20 | |
| Nov-15 | |
| Nov-09 | |
| Nov-02 | |
| Oct-29 |
WeRide launches global insurance programme with Allianz and Ping An
WRD -3.54%
Life Insurance International
|
| Oct-27 | |
| Oct-23 | |
| Oct-13 | |
| Sep-25 | |
| Sep-24 | |
| Sep-23 | |
| Sep-17 |
