Heidmar's First Quarter With Q-Shipping Tests Whether Fleet Growth Can Outrun Rising Overhead
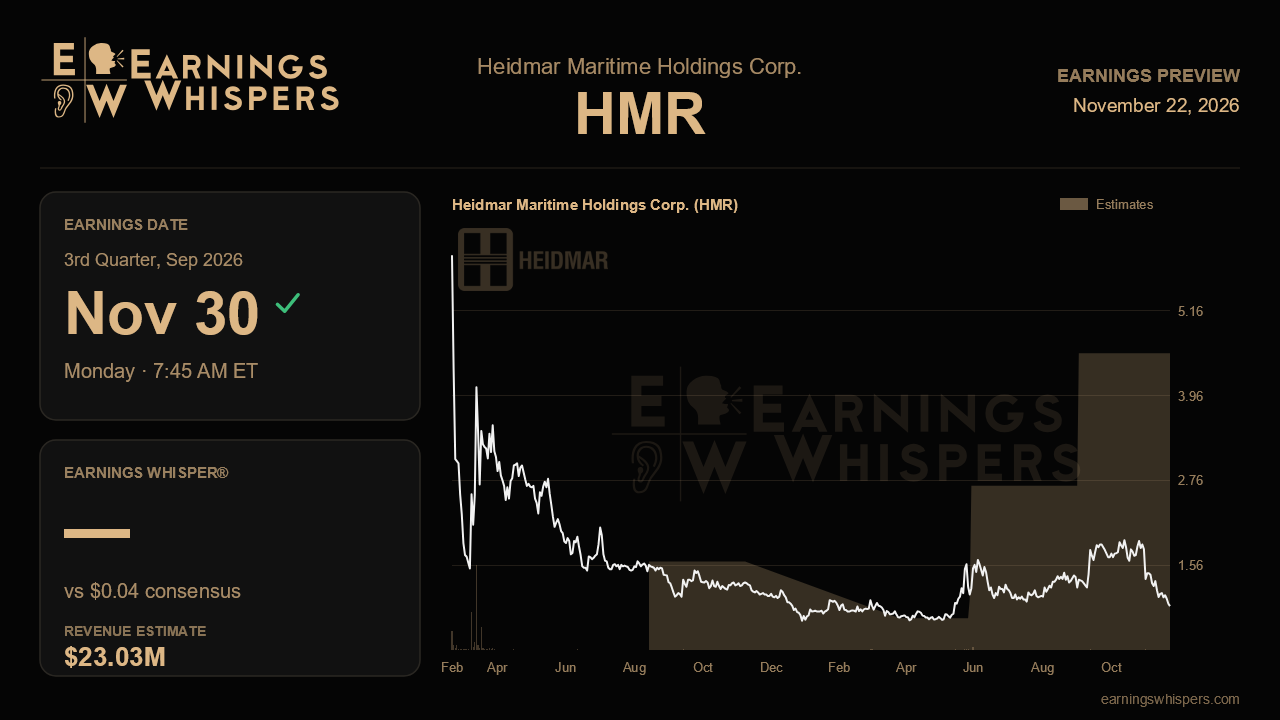
Heidmar Maritime Holdings heads into its third-quarter report with a business that looks healthier than its share price suggests. Over the first half of 2026 the commercial manager added 15 vessels to its platform, closed a small acquisition that brought in nine more, and strung together consecutive profitable quarters after a messy end to 2025. Yet the stock has fallen almost 30% since the last report and now trades below $1. The quarter ending in September is the first to include Q-Shipping, which makes it an early read on whether the company's asset-light growth story is turning into durable earnings or merely bigger revenue.
The Street expects earnings of $0.04 per share on revenue of about $23.0 million. That would mark growth of roughly 33% in profit and 47% in sales from the year-ago quarter, when Heidmar earned $0.03 on $15.6 million. The comparison that deserves more attention, though, is sequential. Revenue reached $29.0 million last quarter, so consensus implies a meaningful step down even as the managed fleet expanded. That gap likely reflects the opportunistic charter-in book, which management itself describes as lumpy from quarter to quarter. Flat EPS on lower revenue would suggest the higher-quality fee stream is carrying more of the load, which is the outcome bulls should prefer. Management has not issued formal guidance to measure the consensus against.
The prior call laid out a clear narrative: more ships under commercial management should drive fee revenue faster than costs, creating operating leverage. Validation this quarter would come in the form of management-fee revenue that visibly reflects both the first-half fleet additions and the Q-Shipping vessels, which management said would be accretive immediately. The weak point is overhead. General and administrative expense jumped from $3.6 million in the first quarter to $5.6 million in the second, largely on cash bonuses, undercutting earlier talk of roughly $13.5 million in cash G&A for the full year. If G&A stays near second-quarter levels, that annual figure becomes difficult to reach, and the operating-leverage argument weakens. A return toward the first-quarter run rate would go a long way toward restoring confidence.
Earnings quality is the other test. Last quarter's $2.2 million in net income looked strong against a prior-year period weighed down by discontinued operations, but continuing operations were close to breakeven. Investors should look for profit that comes from the core platform rather than from favorable comparisons or a good stretch in the proprietary book. Cash, which rose to $28.7 million at midyear, is a useful cross-check on whether reported earnings are turning into real money. Management also leaned on a strong rate backdrop, pointing to Middle East disruptions, sanctioned tonnage and longer trade routes, and suggested rates could climb further into the fourth quarter and early next year. Commentary that reaffirms that view would support fee revenue, which is tied to spot market strength.
The market is not paying for any of this optimism yet. Sentiment has slipped from mildly bullish before the last report to essentially neutral, and the stock has trailed the S&P 500 by about 20 percentage points. At $0.98, shares sit well below the 200-day moving average of $1.21 and just above the post-earnings low of $0.95, after peaking at $2.02. Trading back under $1 also brings up the listing-compliance problem the company resolved only in June.
Ultimately, the report needs to show that adding two dozen vessels in under two quarters produces fee income that grows faster than the people and bonuses required to manage them. If that happens, the low expectations built into the stock could work in Heidmar's favor. If overhead keeps rising alongside the fleet, the flywheel will look more like a treadmill.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Nov-11 | |
| Oct-13 | |
| Sep-01 | |
| Sep-01 | |
| Aug-26 | |
| Aug-16 | |
| Jul-07 | |
| Jun-15 | |
| Jun-04 | |
| Jun-02 | |
| Jun-01 | |
| May-26 | |
| May-20 | |
| May-19 |
