Embecta's Rally Faces A Test: Can Cost Cuts Keep Masking Soft U.S. Demand?
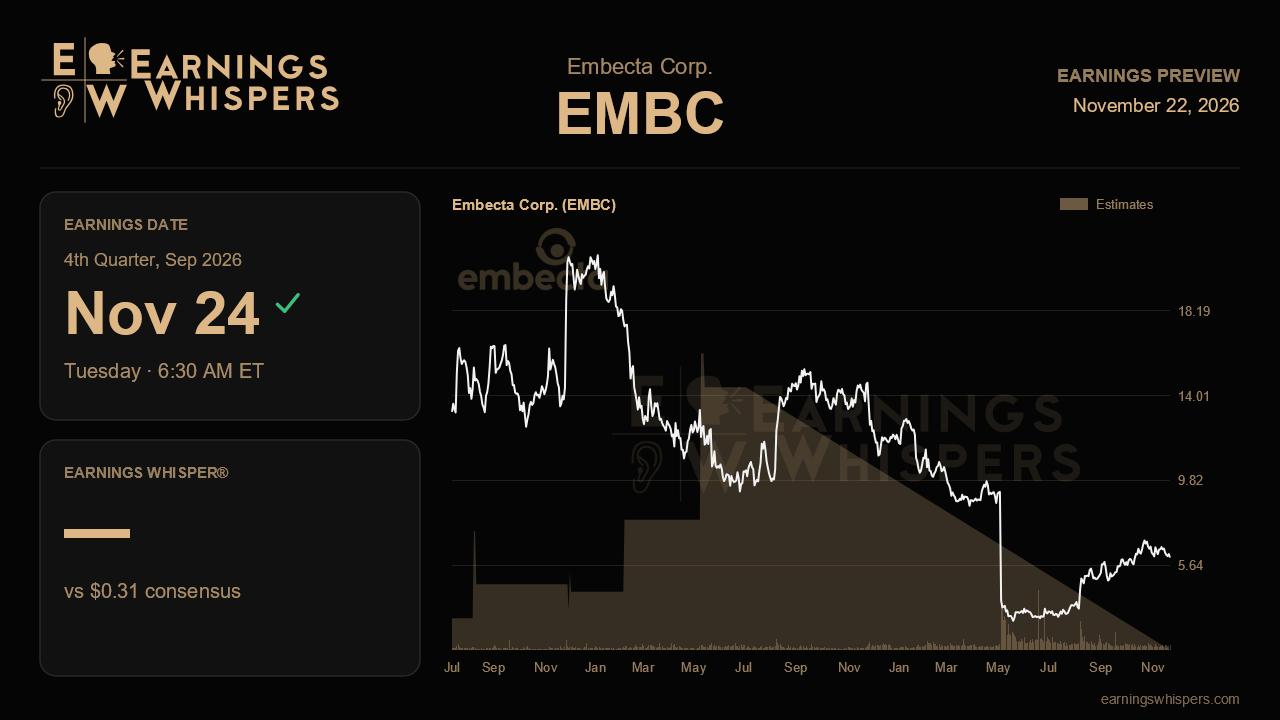
Embecta enters its fiscal fourth-quarter report with a stock that has behaved as though the worst is over. Shares have climbed about 45% since the last report while the S&P 500 fell roughly 10%, a gap of nearly 56 percentage points. That rebound followed a quarter in which management converted a bruising spring guidance cut into a raise on margins and earnings. The open question for the November 24 release is whether that recovery rests on durable footing or mostly on cost discipline layered over a still-shrinking U.S. business.
The Street's bar looks deliberately modest. Consensus calls for EPS of $0.31, down about 38% from $0.50 a year ago and a sharp step back from the $0.56 posted last quarter. On the top line, management's full-year framework implied fourth-quarter revenue of roughly $270 million, slightly below where analysts were sitting at the time. That figure would edge past the $264 million reported a year earlier, but the comparison now includes the Owen Mumford acquisition. Organic trends deserve more scrutiny than the headline number. Given the steep sequential drop baked into EPS estimates, a print near last quarter's level would stand out. Investors should also pay close attention to whether the company lands inside its raised full-year EPS range of $1.80 to $1.90 and its 23.5% to 24% adjusted operating margin target.
The previous call drew a clear line between what is improving and what is not. The improvements came largely from management's own actions: an operating expense review launched in the spring, a lower tax rate of about 27%, and faster debt paydown. The company had repaid $128 million through nine months and lifted its target to at least $150 million, leaving net leverage at 3.7 times after the acquisition. Those levers are within the company's control, so meeting the margin and deleveraging targets should be the minimum expectation. The harder evidence will come from demand. U.S. revenue fell nearly 25% last quarter, adjusted gross margin slid to 58.2% from 67.2% a year earlier, and insulin pen prescriptions declined a bit faster than in the prior quarter. Management also trimmed the high end of its organic revenue outlook because U.S. customer and payer mix was eroding net pricing.
What would validate the turnaround story? First, confirmation that U.S. pen needle share remained stable, as described last quarter, rather than resuming the concentrated losses flagged in the spring. Second, signs that gross margin has stopped compressing. Third, continued international strength after constant-currency growth of nearly 10%. The newer growth avenues also need early proof points. These include generic GLP-1 co-pack launches spreading from India into Canada, Brazil and South Africa, a coming U.S. Zepbound small-pack launch, and the ADAPTUS auto-injector platform now housed in a dedicated Pharma Services unit. No one should expect material revenue from these yet. Still, commentary on uptake, pipeline and partner interest will shape whether they can eventually offset the core decline. Renewed weakness in China, deeper payer mix erosion, or slow progress under the new North American commercial leadership would challenge the narrative.
Sentiment has warmed only slightly, moving from a clearly bearish reading before the last report to roughly neutral now. That suggests the rally reflects relief more than conviction. Technically, the stock at about $6.02 sits just below its 200-day moving average and around 13% under its post-earnings high of $6.90. It has given back some ground without breaking down, and it still trades well above the prior quarter's range.
The central issue is whether Embecta can show that its U.S. franchise has truly stabilized. Cost cuts and debt reduction rescued the earnings outlook last quarter, but they cannot repeat indefinitely. If organic U.S. trends and gross margin show even modest improvement while new catalysts gain traction, the rebound has a foundation. If they do not, the stock's sharp outperformance will look ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-20 | |
| Aug-31 | |
| Aug-13 | |
| Aug-11 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Jul-27 | |
| Jul-27 | |
| Jul-23 | |
| Jul-21 | |
| Jun-25 | |
| Jun-18 |
