Altria Delivers 7.2% EPS Growth in 1H25 Despite Sales Headwinds
Altria Group, Inc. (MO) delivered a notable earnings performance in the first half of 2025, achieving 7.2% adjusted earnings per share (EPS) growth despite ongoing sales pressure. Adjusted EPS rose to $2.67 compared to $2.49 in the same period last year, primarily driven by elevated adjusted operating companies income (“OCI”), fewer shares outstanding and a lower adjusted tax rate, partially offset by lower income from its equity investment in ABI and higher financing costs. For the second quarter alone, adjusted EPS was $1.44, up 8.3% from $1.33 in the second quarter of 2024.
The top line faced challenges, with net revenues slipping 3.6% year over year to $11.4 billion in the first half, reflecting weakness in the smokeable products segment. Still, Altria’s ability to expand margins and capture pricing power proved decisive. Smokeable products’ adjusted OCI climbed 3.5% in the half, with adjusted OCI margins increased 3.5 percentage points to 64.5%. The improvement was fueled by elevated pricing, lower per-unit settlement charges and cost efficiencies, which helped offset the impact of reduced shipment volumes.
Share repurchases also played a role in enhancing EPS growth. Altria repurchased 10.4 million shares in the first half, reducing share count while maintaining its capital return commitments. Combined with $3.5 billion in dividend payouts, shareholder return exceeded $4 billion in just six months.
In short, Altria showed that earnings resilience can outpace volume pressures. The company’s ability to grow adjusted EPS in the face of falling revenues underscores the strength of its margin management and disciplined capital allocation. While sales headwinds persist, the first-half results highlight a balance of pricing, efficiency and shareholder returns driving the bottom line.
How Altria Compares With PM and TPB
Philip Morris International Inc. (PM) posted strong second-quarter 2025 results, with adjusted EPS climbing 20.1% year over year to $1.91, aided by robust pricing in heated tobacco and higher volumes in smoke-free products. Additionally, Philip Morris benefited from margin resilience and its reduced reliance on traditional cigarettes, which supported double-digit earnings expansion despite currency headwinds. Looking ahead, Philip Morris remains firmly positioned around its smoke-free transformation strategy.
Turning Point Brands, Inc. (TPB) also demonstrated earnings momentum, reporting adjusted EPS of 98 cents in the second quarter of 2025, up from 89 cents last year. Turning Point Brands saw this surge fueled by a nearly 8x jump in Modern Oral sales, now accounting for more than a quarter of revenues. Moreover, Turning Point Brands raised its full-year guidance for nicotine pouch sales, signaling continued confidence in category growth.
MO’s Price Performance, Valuation & Estimates
Shares of Altria have gained 7.2% in the past three months against the industry’s decline of 2.8%.
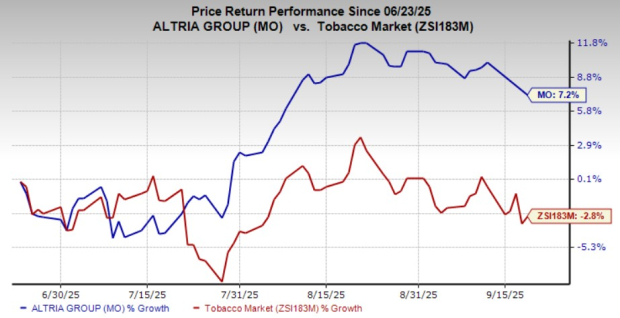
Image Source: Zacks Investment Research
From a valuation standpoint, MO trades at a forward price-to-earnings ratio of 11.6X, down from the industry’s average of 14.95X.
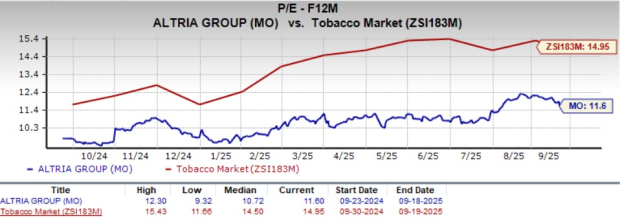
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for MO’s 2025 and 2026 earnings implies year-over-year growth of 5.3% and 2.9%, respectively.
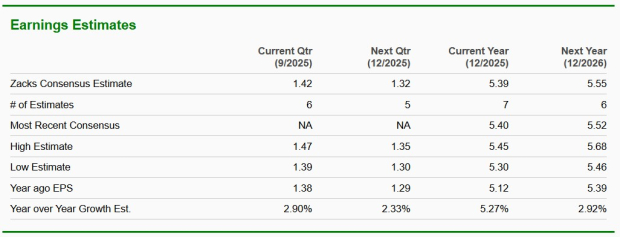
Image Source: Zacks Investment Research
Altria currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Altria Group, Inc. (MO): Free Stock Analysis Report
Philip Morris International Inc. (PM): Free Stock Analysis Report
Turning Point Brands, Inc. (TPB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Sep-09 |
Philip Morris Expands Zyn Nicotine Pouch Lineup, Adds More Pouches Per Can
PM
The Wall Street Journal
|
| Sep-08 | |
| Sep-04 | |
| Sep-04 | |
| Sep-03 | |
| Sep-01 | |
| Aug-31 | |
| Aug-28 | |
| Aug-27 | |
| Aug-26 | |
| Aug-25 | |
| Aug-24 |
