3 Reasons to Avoid MODG and 1 Stock to Buy Instead

The past six months have been a windfall for Topgolf Callaway’s shareholders. The company’s stock price has jumped 57.4%, hitting $14.14 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Topgolf Callaway, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Topgolf Callaway Will Underperform?
We’re glad investors have benefited from the price increase, but we're sitting this one out for now. Here are three reasons why MODG doesn't excite us and a stock we'd rather own.
1. Declining Constant Currency Revenue, Demand Takes a Hit
Investors interested in Leisure Facilities companies should track constant currency revenue in addition to reported revenue. This metric excludes currency movements, which are outside of Topgolf Callaway’s control and are not indicative of underlying demand.
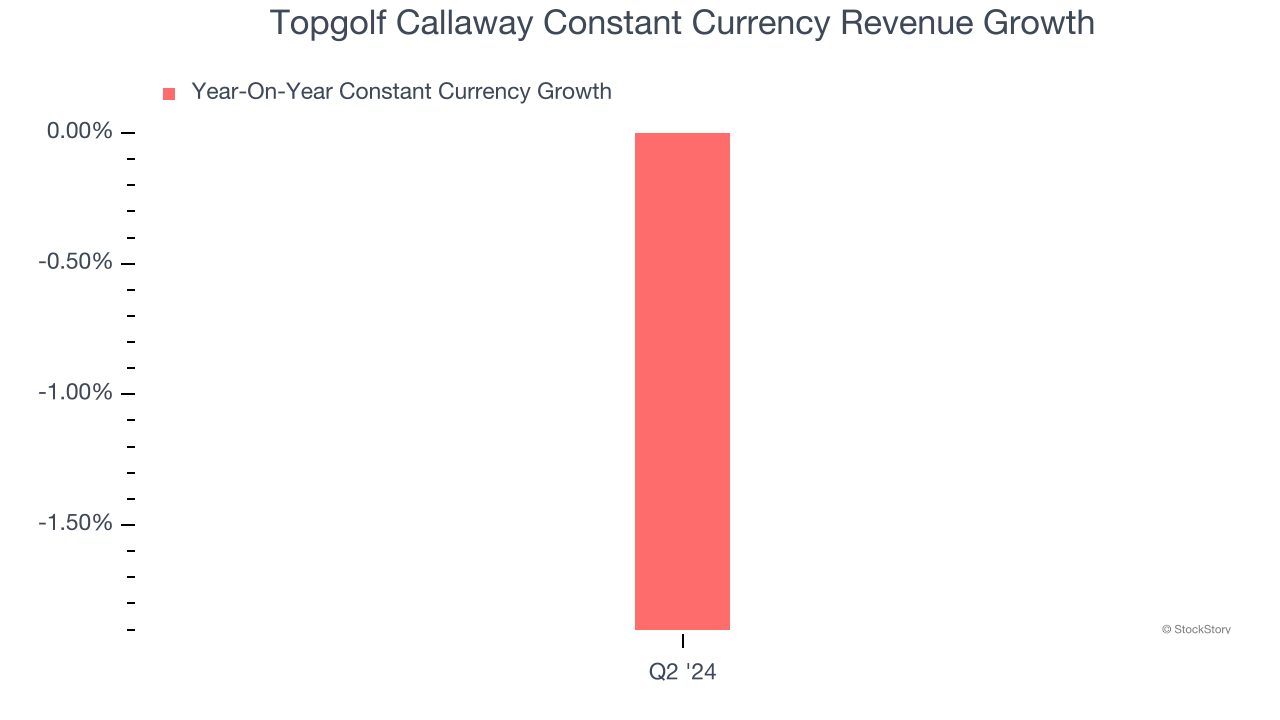
Over the last two years, Topgolf Callaway’s constant currency revenue averaged 1.9% year-on-year declines. This performance was underwhelming and implies there may be increasing competition or market saturation. It also suggests Topgolf Callaway might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability.
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
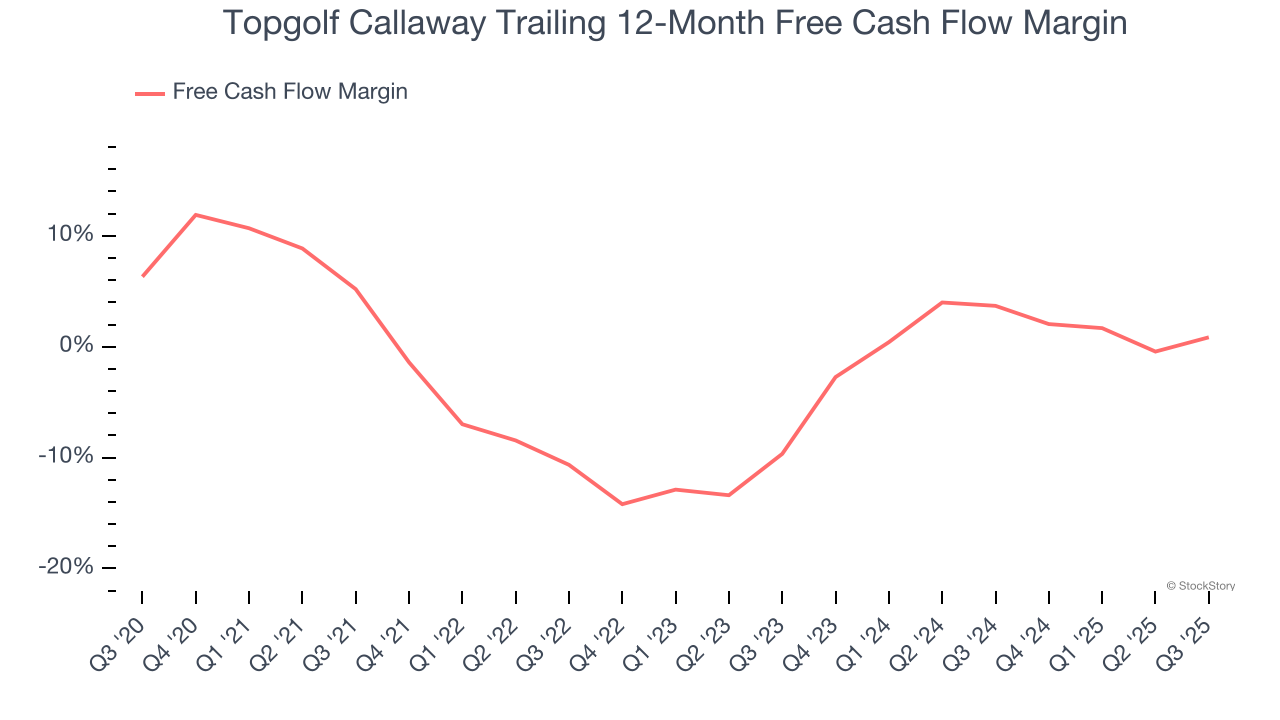
Topgolf Callaway has shown poor cash profitability over the last two years, giving the company limited opportunities to return capital to shareholders. Its free cash flow margin averaged 2.3%, lousy for a consumer discretionary business.
3. New Investments Fail to Bear Fruit as ROIC Declines
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
We like to invest in businesses with high returns, but the trend in a company’s ROIC is what often surprises the market and moves the stock price. Unfortunately, Topgolf Callaway’s ROIC has decreased significantly over the last few years. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Topgolf Callaway, we’ll be cheering from the sidelines. After the recent surge, the stock trades at 50.7× forward P/E (or $14.14 per share). This multiple tells us a lot of good news is priced in - we think there are better opportunities elsewhere. We’d suggest looking at the most dominant software business in the world.
High-Quality Stocks for All Market Conditions
Your portfolio can’t afford to be based on yesterday’s story. The risk in a handful of heavily crowded stocks is rising daily.
The names generating the next wave of massive growth are right here in our Top 5 Growth Stocks for this month. This is a curated list of our High Quality stocks that have generated a market-beating return of 244% over the last five years (as of June 30, 2025).
Stocks that have made our list include now familiar names such as Nvidia (+1,326% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+782% five-year return). Find your next big winner with StockStory today.
Mentioned In This Article
Latest News
| Jan-13 | |
| Jan-12 | |
| Jan-09 |
Here's Why Tapasya Fund Sold Topgolf Callaway (MODG)
Insider Monkey
|
| Jan-07 | |
| Jan-07 | |
| Jan-06 | |
| Jan-06 | |
| Jan-06 | |
| Jan-05 | |
| Jan-02 | |
| Dec-30 | |
| Dec-26 | |
| Dec-22 | |
| Dec-16 | |
| Dec-15 |
3 Unpopular Stocks That Fall Short
StockStory
|
