Qualys (QLYS): Buy, Sell, or Hold Post Q3 Earnings?
Qualys has been treading water for the past six months, recording a small loss of 3.5% while holding steady at $134.57. The stock also fell short of the S&P 500’s 10% gain during that period.
Is there a buying opportunity in Qualys, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Qualys Not Exciting?
We're swiping left on Qualys for now. Here are three reasons why QLYS doesn't excite us and a stock we'd rather own.
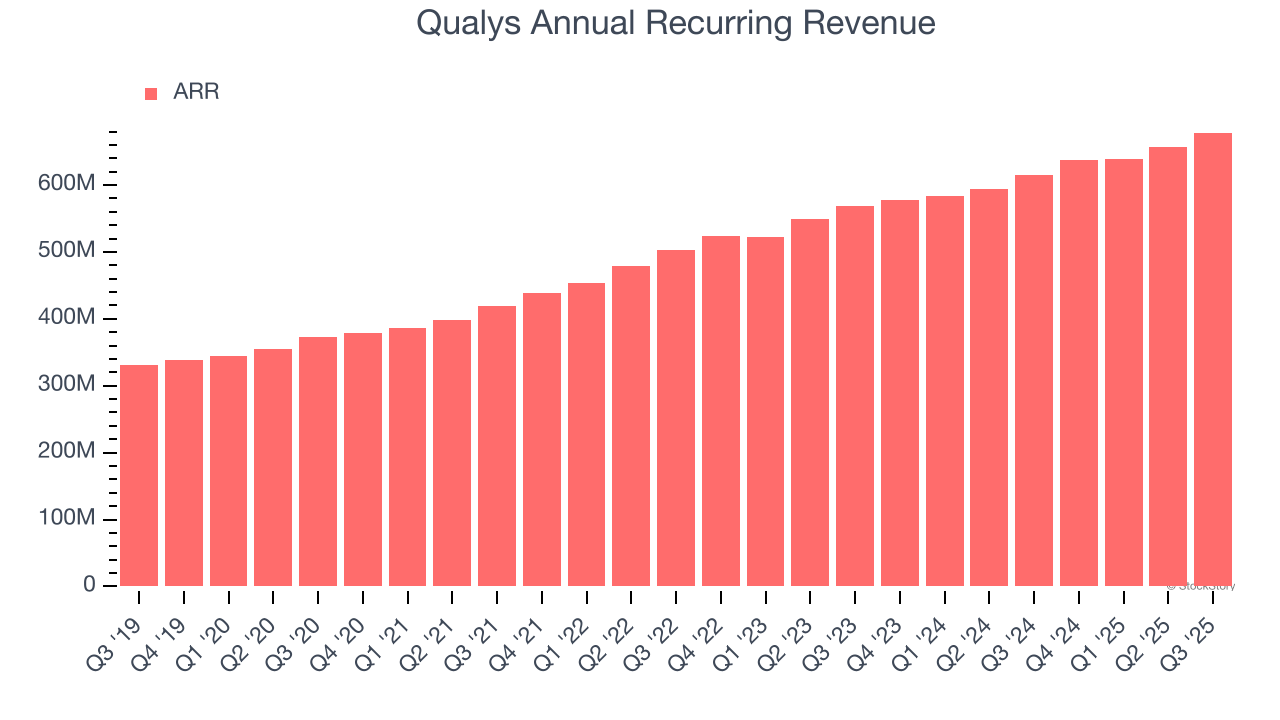
1. Weak ARR Points to Soft Demand
While reported revenue for a software company can include low-margin items like implementation fees, annual recurring revenue (ARR) is a sum of the next 12 months of contracted revenue purely from software subscriptions, or the high-margin, predictable revenue streams that make SaaS businesses so valuable.
Qualys’s ARR came in at $678.4 million in Q3, and over the last four quarters, its year-on-year growth averaged 10.1%. This performance was underwhelming and suggests that increasing competition is causing challenges in securing longer-term commitments.
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Qualys’s revenue to rise by 8.1%, a slight deceleration versus its 13.1% annualized growth for the past five years. This projection is underwhelming and suggests its products and services will see some demand headwinds.
3. Operating Margin Rising, Profits Up
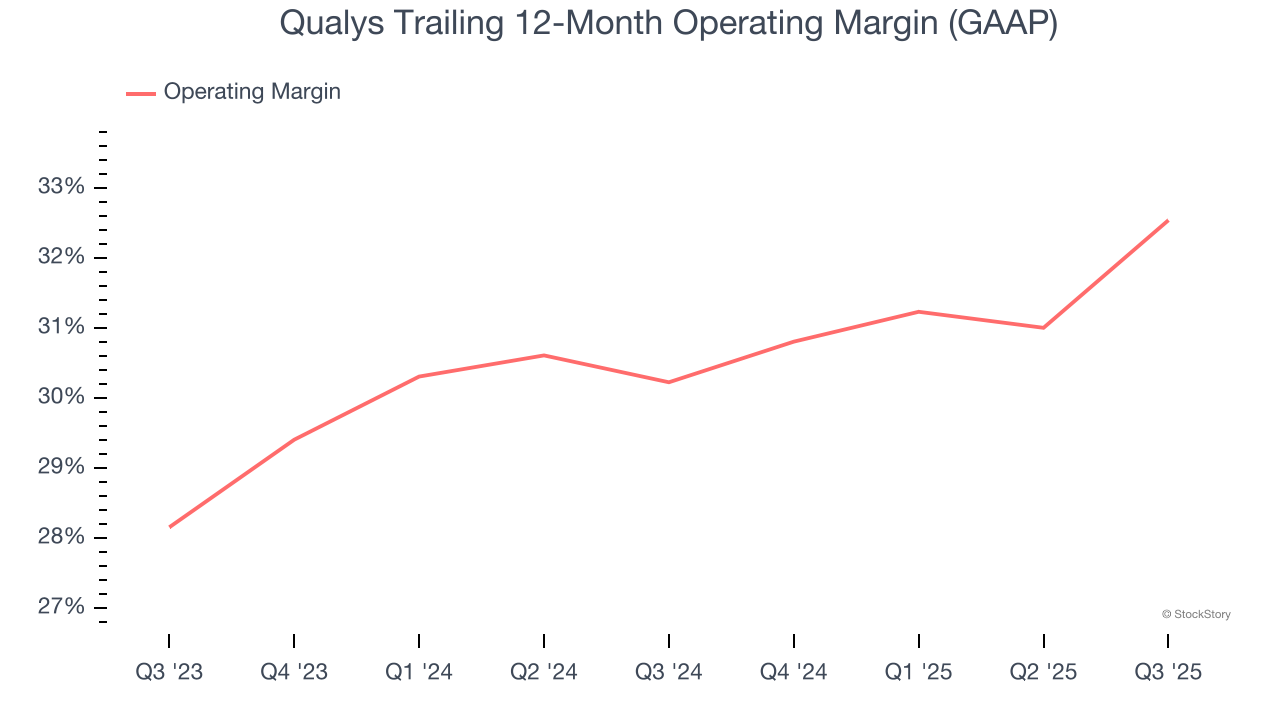
Many software businesses adjust their profits for stock-based compensation (SBC), but we prioritize GAAP operating margin because SBC is a real expense used to attract and retain engineering and sales talent. This metric shows how much revenue remains after accounting for all core expenses – everything from the cost of goods sold to sales and R&D.
Looking at the trend in its profitability, Qualys’s operating margin rose by 2.3 percentage points over the last two years, as its sales growth gave it operating leverage. Its operating margin for the trailing 12 months was 32.5%.
Final Judgment
Qualys isn’t a terrible business, but it doesn’t pass our bar. With its shares lagging the market recently, the stock trades at 6.9× forward price-to-sales (or $134.57 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We're fairly confident there are better stocks to buy right now. We’d suggest looking at a top digital advertising platform riding the creator economy.
High-Quality Stocks for All Market Conditions
If your portfolio success hinges on just 4 stocks, your wealth is built on fragile ground. You have a small window to secure high-quality assets before the market widens and these prices disappear.
Don’t wait for the next volatility shock. Check out our Top 9 Market-Beating Stocks. This is a curated list of our High Quality stocks that have generated a market-beating return of 244% over the last five years (as of June 30, 2025).
Stocks that have made our list include now familiar names such as Nvidia (+1,326% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+354% five-year return). Find your next big winner with StockStory today.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 |
Qualys Earnings Beat. Cybersecurity Stock Falls On Revenue Outlook.
QLYS +6.33% QLYS -13.51%
Investor's Business Daily
|
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-06 |
Nvidia Partner CoreWeave Ready To Report Q3 As AI Stocks Crumble; Nebius, Qualys Also Due
QLYS
Investor's Business Daily
|
| Nov-04 | |
| Nov-02 | |
| Oct-26 | |
| Oct-24 |
SharkNinja Leads 5 Stocks Near Buy Points With Strong Sector Tailwinds
QLYS
Investor's Business Daily
|
| Oct-15 | |
| Oct-14 |
