Qualys Must Turn AI-Driven Pipeline Into Billings To Justify Its Sharp Rally
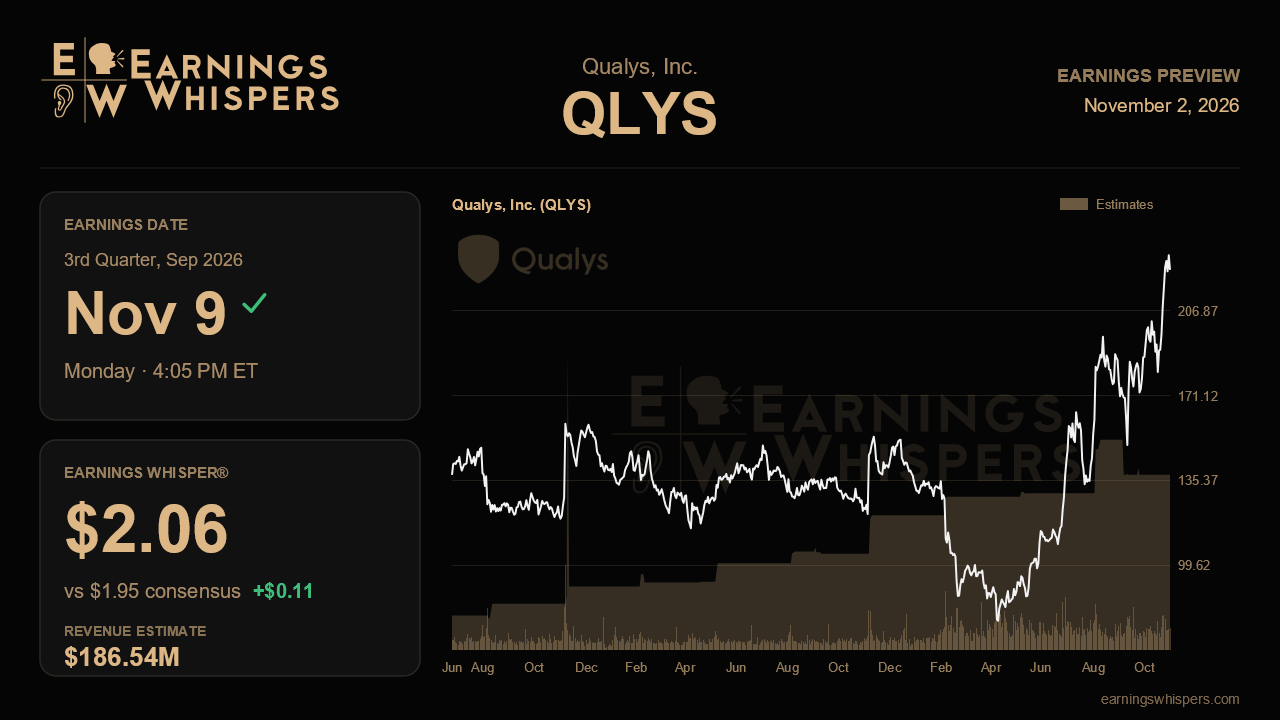
Qualys enters its third-quarter report with something it lacked for most of the past year: momentum. After a long run of steady 10% growth and cautious guidance, the security software company delivered a clean beat-and-raise last quarter. Revenue growth ticked up to 11%, billings accelerated, and management talked openly about growth picking up again over the long term. The stock has responded in kind. The question now is whether the AI-fueled demand management described is moving from proofs of concept into signed contracts, or whether the rally has run ahead of the evidence.
The Street expects non-GAAP earnings of $1.95 per share on revenue of $186.5 million, comfortably above the $1.39 earned a year ago. Both figures sit squarely inside management's guidance of $1.91 to $1.98 and $185.5 million to $187.5 million, with the revenue estimate right at the midpoint and EPS leaning toward the upper half. The Earnings Whisper of $2.06 is the more telling number. It sits meaningfully above consensus and above the top of the company's own range, which suggests buyers are counting on Qualys to keep beating its own conservative targets. Note too that expected revenue growth of 9.8% is a touch below last quarter's 11%, so a merely in-line print would read as a pause rather than a continuation of the acceleration story.
The operating details will matter more than the headline beat. Last-twelve-month current billings growth jumped to 10% from 8.5%, yet management guided second-half billings growth to just 7% to 8%, explicitly assuming no improvement in the broader renewal base. Anything better than that would be the clearest sign that the threat environment created by Mythos, the AI-driven exploit wave, is converting into real spending. Net dollar expansion, which climbed to 105% from a trough of 103%, is another gauge; holding or improving that figure would confirm customers are buying more rather than simply renewing. The count of customers spending more than $500,000, which grew 8% to 229 after years of 4% to 5% growth, offers a read on whether large enterprises are consolidating on the platform.
The newer product story faces its own test. Enterprise TruRisk Management and cloud asset management rose to 12% of total bookings, but their share of new bookings and the cohort's 107% expansion rate were flat sequentially, meaning the adoption inflection is promising but unproven. Evidence that the Black Hat launches, including scanless detection, autonomous zero-day remediation and Total AI 2.0, are winning deals would help. So would more upsells like the low-seven-figure and six-figure QFlex wins cited last quarter, along with progress in the federal pipeline built on FedRAMP High certification. Management should also show that the departure of the executive running the TruRisk business, now backfilled internally, has not disrupted execution. Margins look less of a swing factor, with EBITDA near 46% as sales and marketing spending grows.
Expectations have clearly shifted. Sentiment has swung from mildly bearish before the last report to mildly bullish now, and the stock has gained 13% since then while the S&P 500 slipped 2.6%. At $224, shares trade far above the 200-day moving average near $135 and about 5% below their post-earnings high of $235.55, after a range that sits well above the prior quarter's. That leaves less room for a cautious outlook than there was three months ago.
With full-year guidance already raised twice, to $732 million to $738 million in revenue and $7.74 to $7.88 in EPS, another raise is likely the minimum the market wants. The narrative stays intact if billings and expansion rates beat management's deliberately low bar and the AI-driven pipeline shows up in closed business. If the company simply meets its range and repeats that demand remains early, a stock priced for re-acceleration may find the bar set higher than the quarter can clear.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-26 | |
| Oct-24 |
SharkNinja Leads 5 Stocks Near Buy Points With Strong Sector Tailwinds
QLYS
Investor's Business Daily
|
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-07 | |
| Sep-14 | |
| Sep-11 | |
| Sep-11 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 |
