Qualys Beats And Raises Again, But An ~8% Q4 Billings Guide Caps The Reacceleration Story
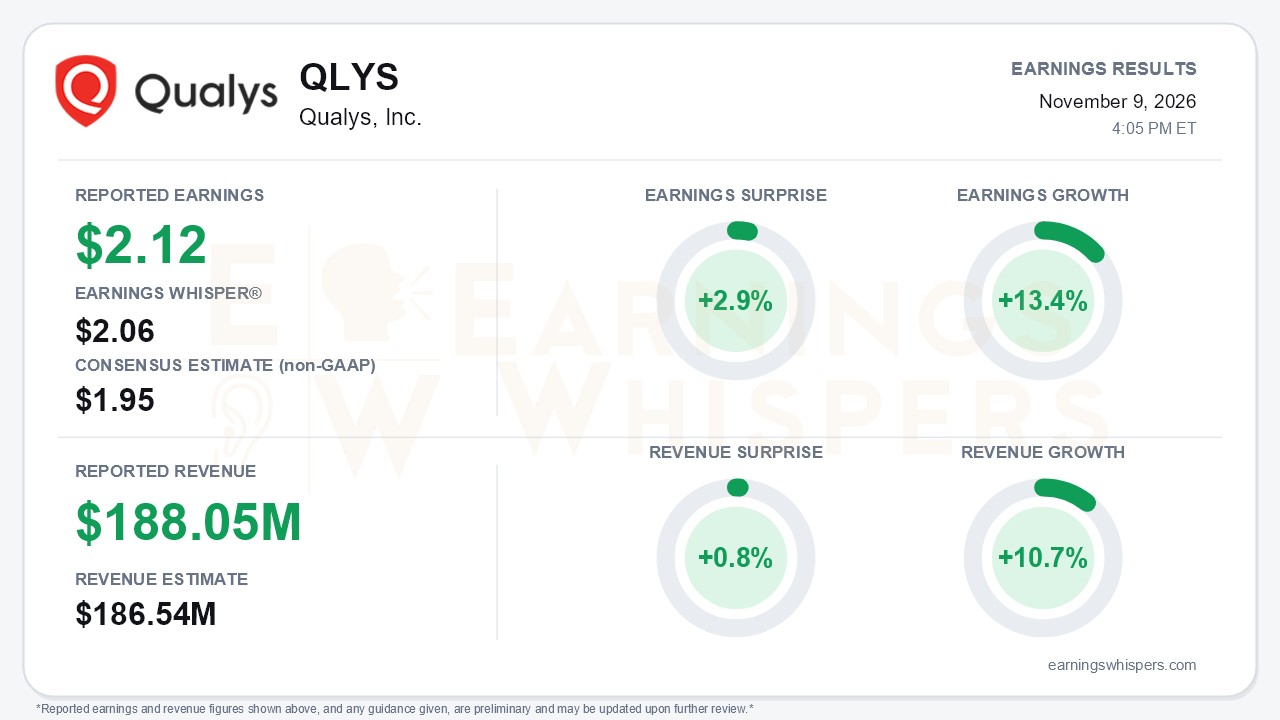
Qualys delivered another clean beat-and-raise in the third quarter, but management also made clear that it is not ready to promise faster growth. The cybersecurity vendor earned $2.12 per share on a non-GAAP basis, ahead of the $1.95 consensus and 2.9% above the $2.06 Earnings Whisper number. Revenue of $188.05 million topped the $186.54 million consensus by 0.8%. Earnings grew 13.4% year over year, while revenue rose 10.7%. Full-year guidance moved higher again, with revenue now expected at $736.9-$738.9 million and non-GAAP EPS at $8.07-$8.14, up from $7.74-$7.88. The central tension is that full-year numbers keep rising while the Q4 billings outlook and management's own commentary point to a business settling back toward high-single-digit growth.
The quality of the beat deserves some scrutiny. Non-GAAP net income rose 11%, but per-share earnings grew faster because diluted shares fell to 35.3 million from 36.3 million. That decline reflects $185.6 million of repurchases through nine months. Profitability was solid rather than expanding. GAAP operating margin held at 35%, but non-GAAP operating margin slipped to 46% from 47%, and adjusted EBITDA margin eased to 48% from 49%. Sales and marketing spending grew about 17%, faster than revenue, as the company leans into its partner-first strategy. Cash generation remained a standout, with Q3 operating cash flow up 13% to $101.8 million. Calculated current billings grew 14% to $211.9 million, well above revenue growth.
The call explains why that billings strength may not carry forward. Management called Q3 an unprecedented federal quarter. Highlights included a new low-seven-figure agency win spanning seven modules and a seven-figure expansion at an existing agency, helped by CISA's BOD 26-04 72-hour remediation mandate. The billings beat came mainly from those lumpy federal new-logo deals. Billings growth also slowed from 16% in Q2 to 14% in Q3, and Q4 is guided to roughly 8%. The CFO explicitly said not to expect near-term revenue acceleration. The implied 9-10% Q4 revenue growth fits that message, as does Q3's slight dip to 10.7% from 11% in Q2, which management attributed to linearity. Sales cycles, close rates and win rates have not improved. Management described AI-driven vulnerability demand, including interest following Mythos, as pipeline-building rather than near-term spending.
Beneath the surface, the operating picture is mixed but improving in the areas that matter most for durability:
- **Large customers:** Accounts above $500,000 reached 243, up 15%, compared with 8% growth in Q2 and 4% at the end of fiscal 2025.
- **Product traction:** Patch management rose to 18% of new bookings. Patch deployments are up 47% since April, and 60% of patches are now autonomous, compared with 30% a year ago.
- **Pricing:** QFlex customers lifted average annual bookings by more than 20% in the program's first full quarter after general availability.
- **Retention:** The ETM/CSAM cohort net dollar retention rose to 108%.
Bears still have legitimate ammunition. Overall net dollar retention stalled at 105%, and direct revenue declined 2%. Channel mix rose to 55%, which may help explain the direct weakness.
The forward story rests on monetizing new products into an installed base of more than 10,000 organizations. These include TruRisk Eliminate 2.0 with the TrueConfidence remediation engine, InstaScan, the TotalAI governance features, and the Dynatrace partnership. Management is also showing restraint on spending. It trimmed the opex growth outlook to low double digits and lifted the full-year EBITDA margin guide to 46%. That supports earnings even if top-line growth stays near 10%.
The market setup is more complicated than the surprise implies. Investor sentiment improved meaningfully, moving from mildly negative (-0.13) after the August report to slightly positive (0.08). Shares have been volatile. The stock fell to an inter-earnings low of $149.13 in September, then rallied to a 52-week high of $235.55 on October 30. It entered the report at $190.41, about 19% below that peak and 4% below the open after the prior report. The stock still sits nearly 40% above its 200-day moving average, and the Earnings Whispers trend signals are uniformly positive. However, the quick retreat from late-October highs suggests investors had already priced in some reacceleration hopes that management has now tempered.
The bottom line is that Qualys continues to execute: it beats, raises guidance, protects margins and generates abundant cash. The quarter's upside, however, came largely from federal deals that may not repeat, and management explicitly discouraged expectations of faster growth. Large-customer growth, patch-management adoption and QFlex give the story real substance. Until billings and net retention show sustained improvement, Qualys looks more like a reliable compounder in the 10% range than a reaccelerating growth story.
Read our earnings preview for Qualys, Inc.: https://www.earningswhispers.com/article/QLYS/22664
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 |
Qualys Earnings Beat. Cybersecurity Stock Falls On Revenue Outlook.
QLYS +6.33% QLYS -5.14%
Investor's Business Daily
|
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-06 |
Nvidia Partner CoreWeave Ready To Report Q3 As AI Stocks Crumble; Nebius, Qualys Also Due
QLYS
Investor's Business Daily
|
| Nov-04 | |
| Nov-02 | |
| Oct-26 | |
| Oct-24 |
SharkNinja Leads 5 Stocks Near Buy Points With Strong Sector Tailwinds
QLYS
Investor's Business Daily
|
| Oct-15 | |
| Oct-14 | |
| Oct-13 |
