Lindblad Expeditions (LIND): Buy, Sell, or Hold Post Q3 Earnings?
What a fantastic six months it’s been for Lindblad Expeditions. Shares of the company have skyrocketed 47.9%, setting a new 52-week high of $20.70. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Lindblad Expeditions, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think Lindblad Expeditions Will Underperform?
We’re glad investors have benefited from the price increase, but we're sitting this one out for now. Here are three reasons there are better opportunities than LIND and a stock we'd rather own.
1. Long-Term Revenue Growth Disappoints
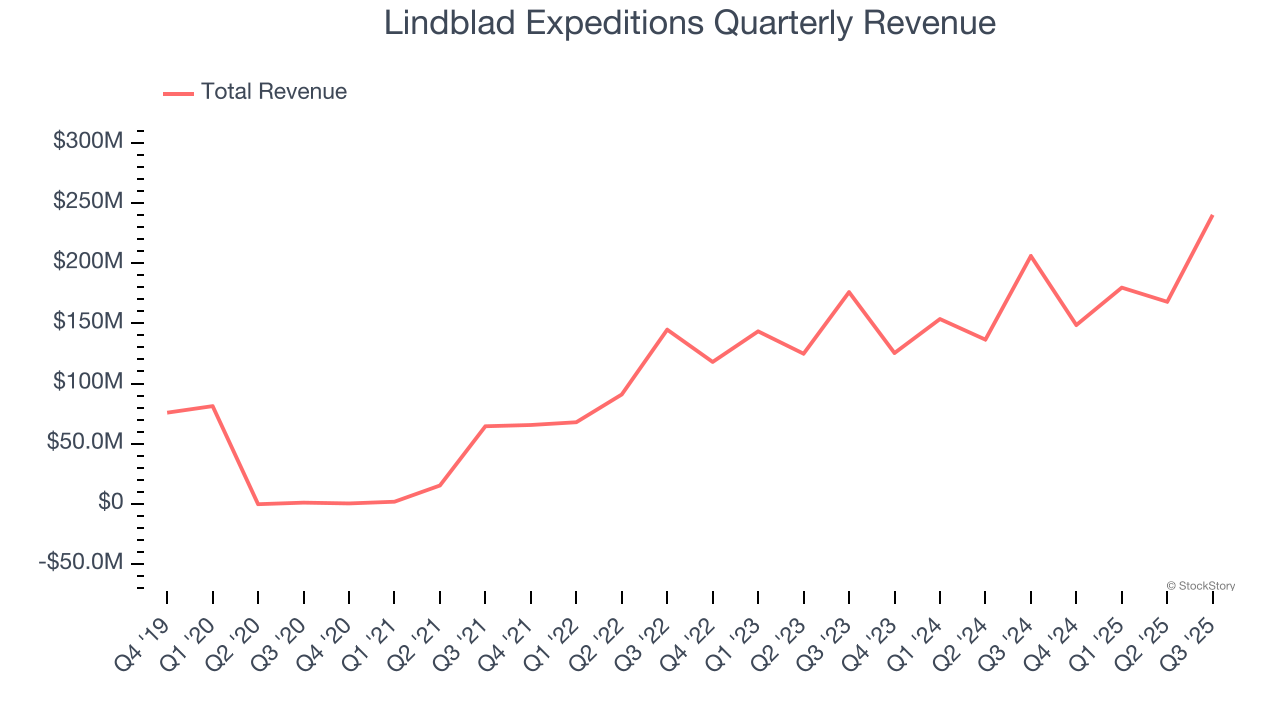
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Lindblad Expeditions grew its sales at a 36.1% compounded annual growth rate. Although this growth is acceptable on an absolute basis, it fell slightly short of our standards for the consumer discretionary sector, which enjoys a number of secular tailwinds.
2. Weak Operating Margin Could Cause Trouble
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
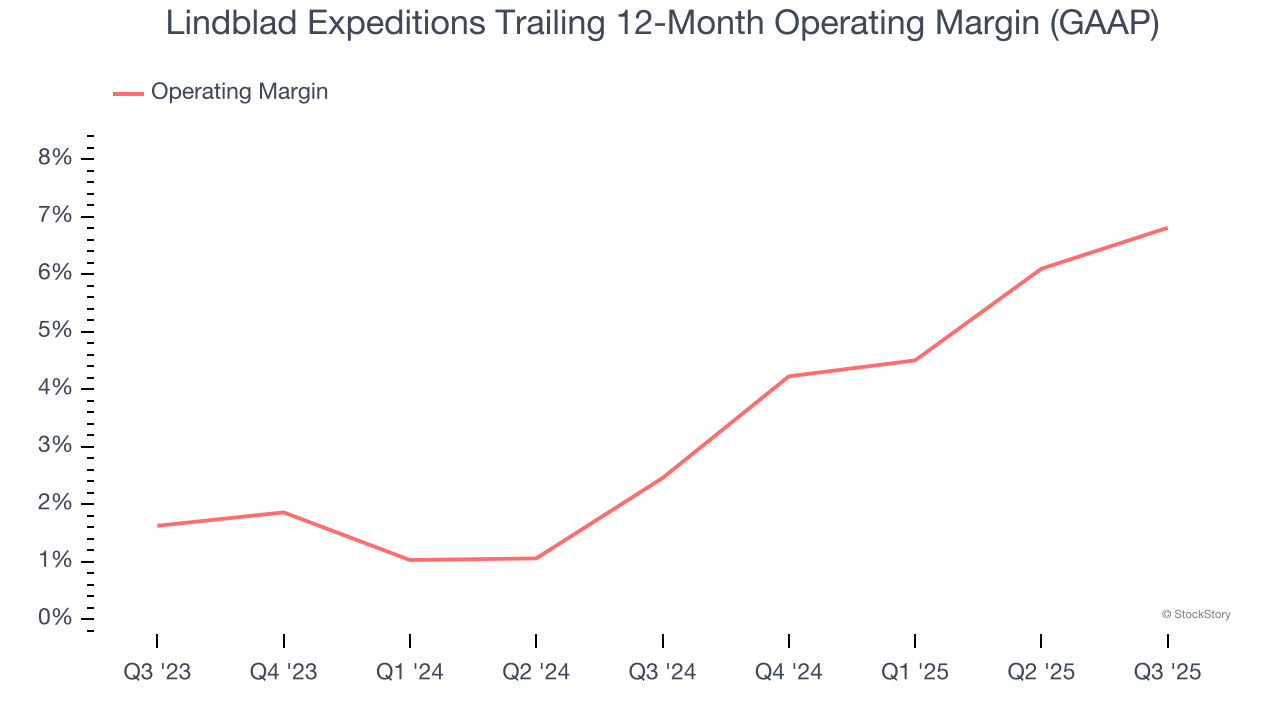
Lindblad Expeditions’s operating margin has risen over the last 12 months and averaged 4.8% over the last two years. The company’s higher efficiency is a breath of fresh air, but its suboptimal cost structure means it still sports inadequate profitability for a consumer discretionary business.
3. Free Cash Flow Projections Disappoint
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Over the next year, analysts’ consensus estimates show they’re expecting Lindblad Expeditions’s free cash flow margin of 7.1% for the last 12 months to remain the same.
Final Judgment
Lindblad Expeditions falls short of our quality standards. Following the recent surge, the stock trades at 286.3× forward P/E (or $20.70 per share). This valuation tells us a lot of optimism is priced in - we think there are better stocks to buy right now. Let us point you toward a safe-and-steady industrials business benefiting from an upgrade cycle.
Stocks We Like More Than Lindblad Expeditions
If your portfolio success hinges on just 4 stocks, your wealth is built on fragile ground. You have a small window to secure high-quality assets before the market widens and these prices disappear.
Don’t wait for the next volatility shock. Check out our Top 6 Stocks for this week. This is a curated list of our High Quality stocks that have generated a market-beating return of 244% over the last five years (as of June 30, 2025).
Stocks that have made our list include now familiar names such as Nvidia (+1,326% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+354% five-year return). Find your next big winner with StockStory today.
Mentioned In This Article
Latest News
| Sep-15 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 | |
| Jul-20 | |
| Jul-18 | |
| May-05 | |
| Apr-29 | |
| Apr-28 | |
| Feb-27 | |
| Feb-26 | |
| Feb-26 | |
| Feb-26 | |
| Feb-26 |
