Enerpac's Year-End Report Tests Whether Its Middle East Drag Has Bottomed Before SFE
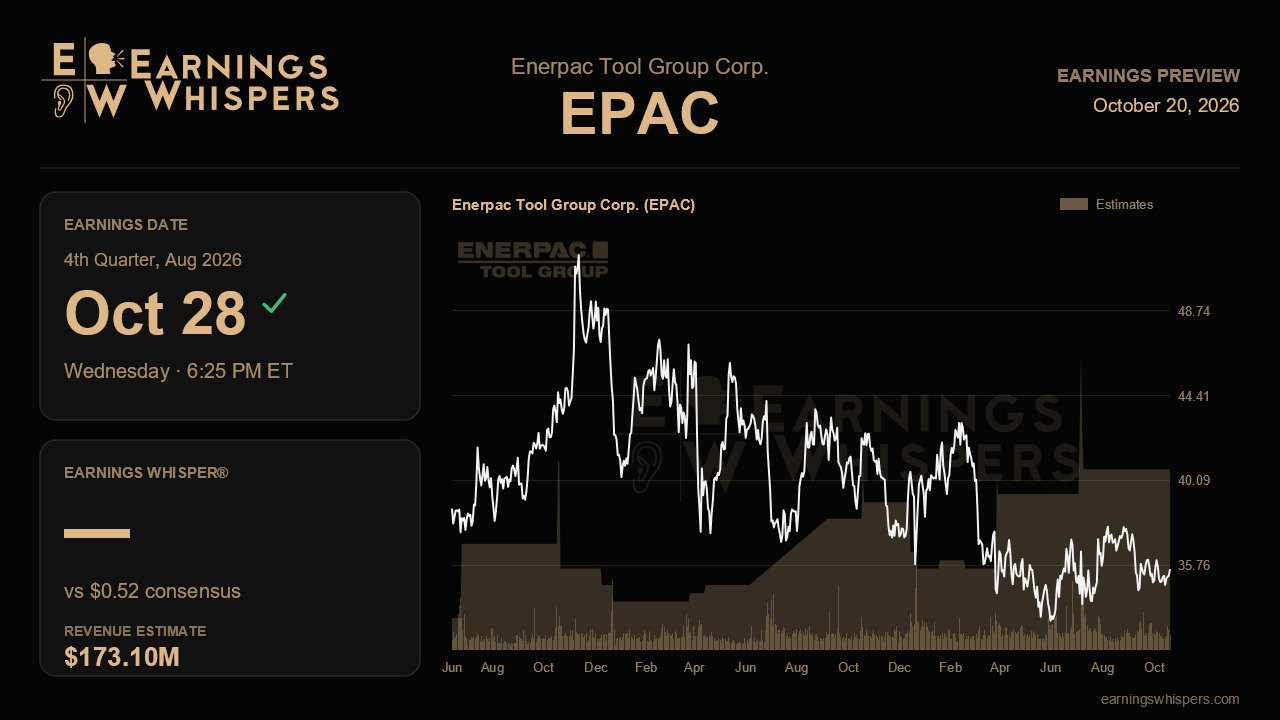
Enerpac Tool Group heads into its fiscal fourth-quarter report with two very different stories competing for attention. One is a shrinking near-term outlook, trimmed for a third straight quarter as the Middle East conflict dragged on longer than management expected. The other is the roughly $472 million agreement to buy SFE Group, a deal that would add about $170 million of sales at premium margins and widen the company's addressable market to around $5.5 billion. When Enerpac reports after the close on October 28, the market will be judging whether the core business is stable enough to carry that ambition.
The Street is looking for earnings of $0.52 a share on revenue of $173.1 million. That works out to flat profit on revenue growth of about 3.3%, a modest bar that already absorbs plenty of caution. Sequentially, the comparison looks worse than it is. Third-quarter EPS of $0.60 was flattered by a $6 million tariff refund that management said would not repeat. The full-year picture is less forgiving. Guidance now calls for adjusted EPS of $1.84 to $1.89, down from $1.85 to $1.92 last quarter and $1.85 to $2.00 earlier in the year. The consensus of $1.89 sits right at the top of that range. Revenue expectations of about $641 million fall near the midpoint of the $635 million to $645 million outlook. In other words, analysts are not assuming further erosion, so another soft service quarter would leave little room.
Service is the swing factor. Industrial Tools & Services service revenue fell 8% organically in the third quarter. That was a clear improvement from declines of 17% and 26% in the prior two quarters, helped by the five-year UK North Sea contract starting to contribute. Management warned of a roughly $3 million project delay tied to the Middle East and flagged a similar hit in the fourth quarter, with no normalization until the first half of fiscal 2027. A narrower service decline despite that headwind would support the claim that the worst is passing. A setback would suggest the conflict is causing broader damage than one deferred project.
The product side needs to keep doing the heavy lifting. Product sales grew 5% organically last quarter, in line with the mid-single-digit pace of recent quarters. Americas product rose 10% on power generation, heavy lifting and data center demand, and Cortland has been growing in the mid-20% range. Growth from those areas would confirm that the demand engine is intact. The catch is that heavy lifting carries lower margins, so stronger volume could still pressure gross margin, particularly without the tariff refund. Any further softening in Asia-Pacific, where refinery shutdown delays and inflation-driven purchase deferrals left sales flat, would add to the strain. The free cash flow target of $100 million to $110 million also deserves attention, given that net leverage is expected to jump to about 2.8 times after SFE closes.
Sentiment has cooled noticeably, with bearish readings deepening to 23.7% from 10.2% ahead of the last report. The stock has slipped 1.7% since then while the S&P 500 gained 3.1%. At $35.23, shares sit below their 200-day moving average of $36.76 and in the lower half of their post-earnings range of $32.81 to $38.00. That is not a crowd braced for good news, which lowers the hurdle somewhat for a clean quarter.
Ultimately, this report needs to show that the guidance cuts have run their course. If Enerpac lands its fourth quarter inside the range, shows service still recovering and offers a credible bridge into fiscal 2027 with SFE, the acquisition story can take center stage. Another reset would keep investors focused on the core business rather than the deal.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Oct-08 | |
| Jul-27 | |
| Jul-23 | |
| Jul-10 | |
| Jul-09 | |
| Jul-09 | |
| Jul-08 | |
| Jul-07 | |
| Jul-07 | |
| Jul-07 | |
| Jun-24 | |
| May-27 | |
| May-04 |
