Enerpac Tool Group Beats On Accelerating Sales, But Margin Erosion Keeps The EPS Beat Thin Heading Into The SFE Era
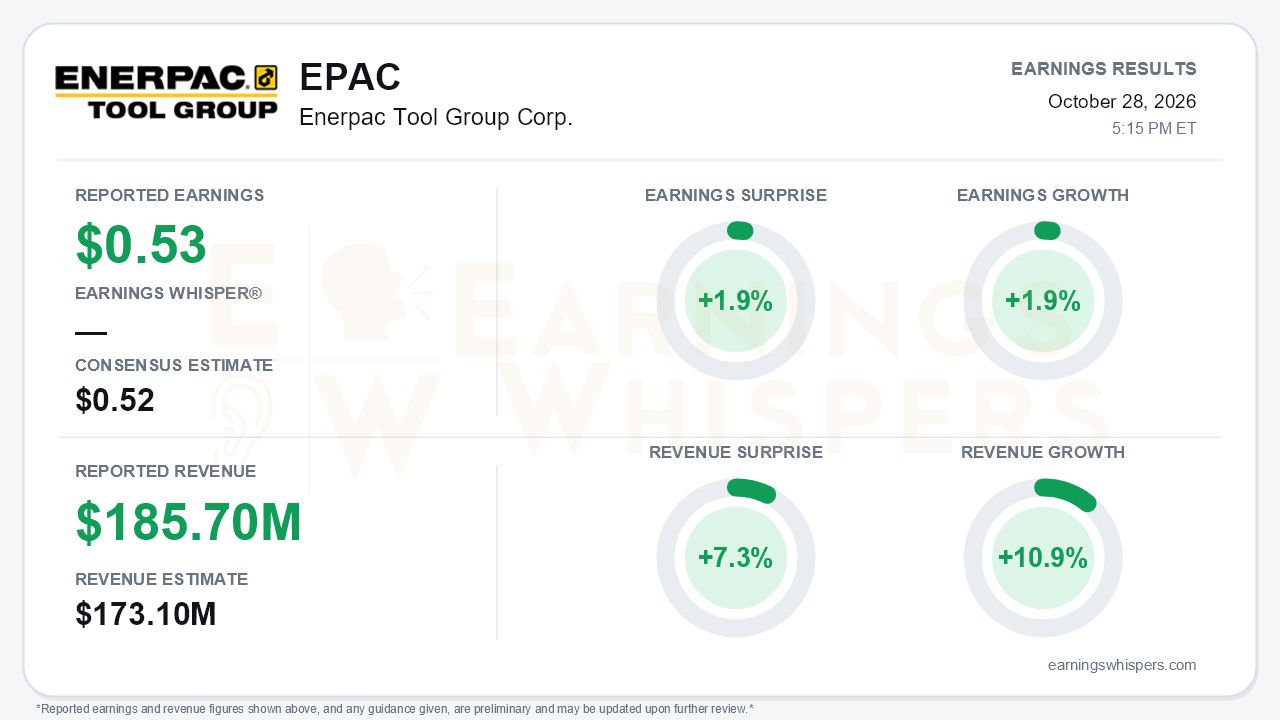
Enerpac Tool Group (NYSE: EPAC) closed fiscal 2026 with a quarter whose headline and underlying earnings tell different stories. Adjusted earnings of $0.53 per share topped the $0.52 consensus by 1.9% and rose 1.9% year over year. Revenue of $185.7 million beat the $173.1 million consensus by a much wider 7.3% and grew 10.9%. That gap is the central tension. Revenue growth accelerated sharply, from -1% in the first quarter to 6% in each of the middle two quarters and 11% in the fourth. Earnings barely moved, because margins absorbed most of the extra volume. Adjusted EPS growth also decelerated sharply from the third quarter, when adjusted EPS rose to $0.60 from $0.51.
The quality of the beat deserves scrutiny. On a GAAP basis, diluted EPS fell to $0.47 from $0.52, and net margin slipped to 13.1% from 16.8%. Gross margin contracted to 47.0% from 50.1%. Adjusted SG&A climbed to $47.3 million from $41.8 million, and corporate costs widened. Adjusted EBITDA actually declined to $42.1 million from $44.5 million despite $18 million of additional sales, and the margin compressed to 22.6% from 26.5%. Management attributed the squeeze to:
- lower-margin heavy lifting technology mix;
- higher incentive compensation;
- investment in its Propel growth strategy.
M&A charges of $4.1 million tied to the SFE deal explain the gap between GAAP and adjusted results. Cash generation was unambiguously strong. Free cash flow reached $120 million, up 30% and above the $100 million to $110 million guidance range held all year. That cash funded $81 million of buybacks and still left net leverage at just 0.1x.
Beneath the margin pressure, the demand picture improved materially. Organic sales rose 10%, with Industrial Tools & Services product sales up 11%. Service sales grew 9% organically after declines of 26%, 17%, and 8% in the first three quarters. That turnaround included the first EMEA service growth of the year. Americas IT&S organic growth reached 24%, up from 6% in the third quarter, driven by data center construction, power generation, defense, and reshoring. All three regions posted double-digit order growth. Full-year organic growth came in at 4%. That figure beat a guide that had been trimmed repeatedly to 1%-2% by the third quarter, and record revenue of $652 million cleared the earlier $635 million to $650 million range.
The forward setup now hinges on SFE Group, acquired for roughly $472 million and closed on the day of the report. The fiscal 2027 outlook, which includes about 10 months of SFE, calls for:
- net sales of $825 million to $845 million;
- organic growth of 4% to 6%;
- adjusted EBITDA of $195 million to $205 million, roughly a 24% margin at the midpoint;
- adjusted EPS of $2.00 to $2.15, a double-digit increase at the midpoint from fiscal 2026's $1.87.
Leverage at close came in near 2.3x, below the 2.8x previously estimated, and the year-one target was lowered to about 2.0x. Bears still have legitimate ammunition, though. Management signaled that first-year SFE accretion will likely fall short of the roughly $0.20 analysts had modeled because of interest and reinvestment. The deal also brings $10 million to $14 million of integration costs and moves the balance sheet from essentially net-cash to meaningful leverage. Europe, roughly 40% of the business, remains sluggish, and Middle East conflict clouds service visibility. Investors should also remember that fiscal 2026 EBITDA and EPS guidance had been cut midyear, so margin delivery remains a credibility question.
Investor sentiment has soured noticeably. It moved from slightly negative at -0.10 after the July report to a clearly negative -0.37. Price action has been flat. Shares sat at $35.70 on the report date, essentially unchanged from the $35.82 opening after the prior release and about 2.5% below the 200-day moving average of $36.62. The Earnings Whispers trend readings are modestly constructive, with AVWAP positive while price trend is neutral. The market has been unwilling to reward improving demand while margins slide and the SFE deal adds integration risk. The November 4 Investor Day, where Propel's multi-year targets will be unveiled, is the next opportunity to address that skepticism.
The bottom line is that Enerpac delivered the top-line acceleration and service recovery that skeptics doubted, along with standout cash flow. However, a revenue beat of this size produced only a one-penny EPS beat and a lower EBITDA margin. Fiscal 2027 guidance offers a credible double-digit earnings growth path. Whether that materializes depends on margin recovery and on SFE integration proceeding without the accretion shortfall widening, and the souring sentiment shows investors want proof before paying up.
Read our earnings preview for Enerpac Tool Group Corp.: https://www.earningswhispers.com/article/EPAC/21010
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Oct-08 | |
| Jul-27 | |
| Jul-23 | |
| Jul-10 | |
| Jul-09 | |
| Jul-09 | |
| Jul-07 | |
| Jul-07 | |
| Jul-07 |
