PC Connection Must Show Record Backlog Can Outrun The Demand It Pulled Forward
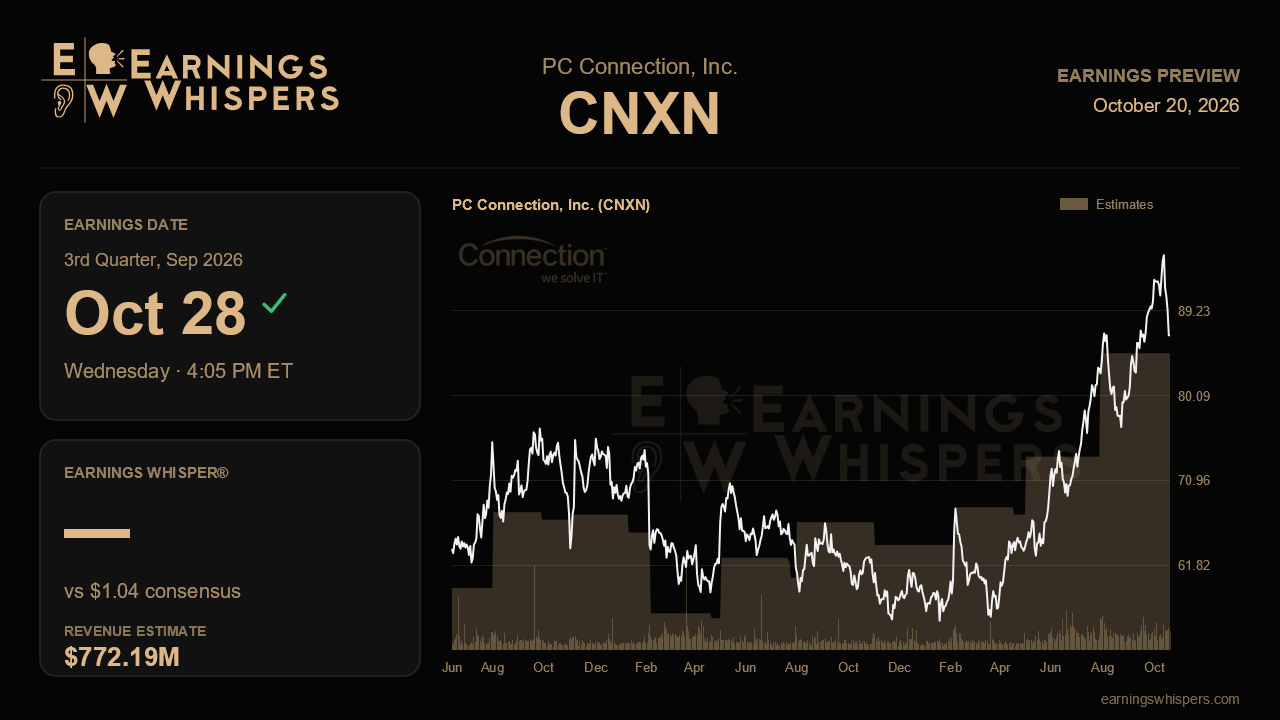
PC Connection's last report was the kind of quarter that changes a narrative: record sales, record operating margin, and the long-running public-sector drag finally gone. The catch is that management also told investors the next quarter would step down from that peak, and that some of the second-quarter strength was borrowed from customers racing ahead of price increases. The third-quarter report, due after the close on October 28, is therefore less about whether the company can top $854 million in sales and more about whether the underlying recovery holds once the one-time boost fades.
The Street is positioned for a softer but still growing quarter. Consensus calls for earnings of $1.04 per share on revenue of $772.2 million, up 7.2% and 8.9% from a year ago, when the company earned $0.97 on $709.1 million. That would mark a roughly 10% sequential revenue decline from the second quarter, consistent with management's warning about the Microsoft June year-end and the usual seasonal dip, without giving formal numbers. The year-ago comparison is forgiving: last year's third quarter saw sales shrink 2.2% while public-sector revenue fell by about a quarter. High-single-digit growth against that base is respectable rather than heroic.
One detail in the consensus deserves attention. Analysts expect earnings to grow more slowly than revenue, which implies further margin dilution even though the company is now carrying an estimated $7 million to $8 million in annual savings from its restructuring. That makes gross margin the swing factor. It held at 18.4% last quarter, flat sequentially but well below the 19.6% posted a year earlier, as lower-margin endpoint hardware crowded out net-basis cloud and software revenue. Business Solutions margin has slid for four straight quarters to 23.0%. Stabilization there, along with operating expenses that stay disciplined as sales dip, would validate the operating leverage story. Another leg down would suggest the record 5.0% operating margin was a high-water mark driven by volume rather than structural improvement.
Demand quality is the second test. Management described a shift from AI experimentation toward enterprise-wide adoption, pointed to a record backlog in Enterprise Solutions and the highest Business Solutions backlog in three years, and noted endpoint units rose only about 3% even as endpoint revenue jumped nearly 20%. That gap means memory-driven price inflation is doing a lot of the lifting. Investors should look for backlog converting into revenue that holds up better than the pull-forward warning implies, and for continued strength in software and networking, which are less dependent on rising component prices. Public sector, now flat after quarters of steep declines, should show genuine growth against an easy comparison if the recovery is real.
Cash flow is the quieter concern. Operating cash flow was negative $49.5 million in the first half as inventory and receivables swelled, and cash and short-term investments fell to $340.7 million. Some build is natural ahead of record backlog, but a seasonally lighter quarter should allow working capital to unwind. If it does not, the inventory could look less like preparation and more like exposure to a price cycle of uncertain length.
The market has been cautious. Shares are up 2.8% since the last report, trailing the S&P 500 by about 1.4 percentage points, and bullish sentiment has cooled to 5.1% from 13.9% heading into the prior release. At $86.60, the stock sits comfortably above its 200-day moving average near $71 and in a higher range than last quarter, yet roughly 11% below its post-earnings high of $96.91. The central question is whether PC Connection can show that its second-quarter breakout was a new baseline dented by seasonality and pull-forward, not a peak inflated by them. Steady margins and backlog conversion would answer yes.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Oct-14 | |
| Oct-02 | |
| Sep-14 | |
| Aug-20 | |
| Aug-19 | |
| Aug-06 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-10 | |
| Jul-09 | |
| Jun-16 |
