PC Connection Crushes Q3 Estimates On Price-Fueled Sales Surge, But Margins, Cash Flow And A Cautious 2027 Outlook Temper The Beat
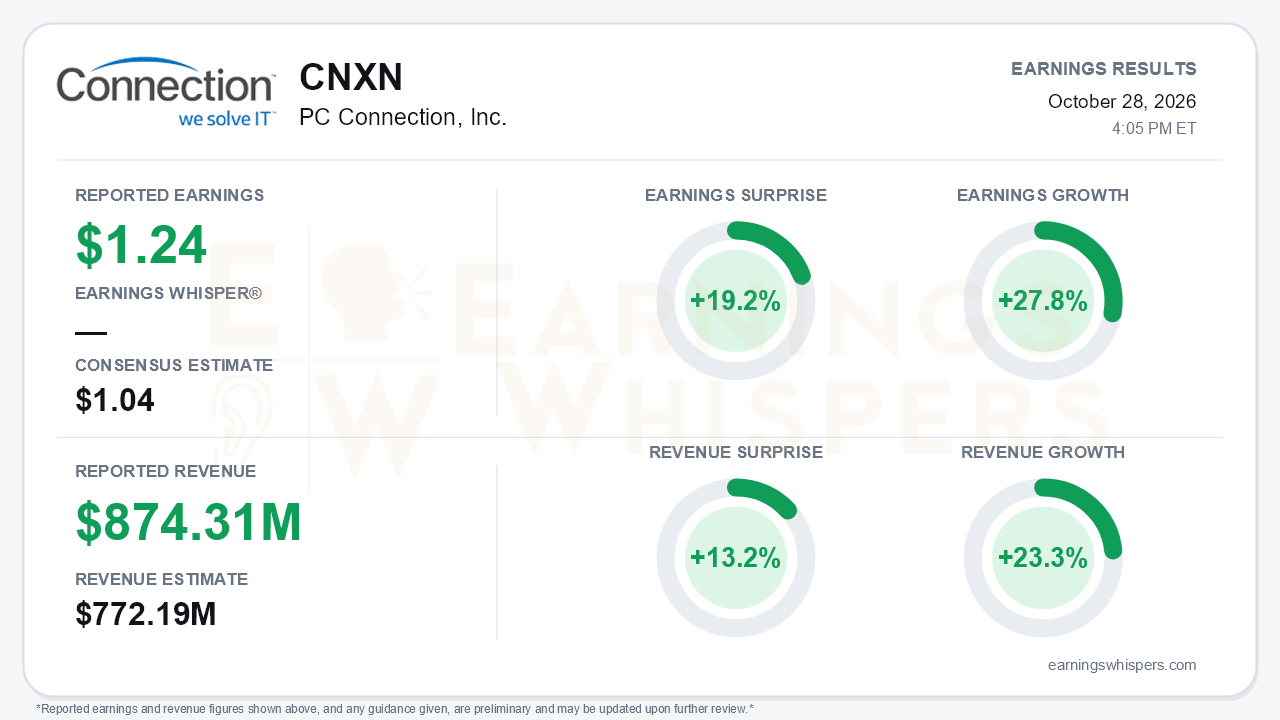
PC Connection delivered its strongest top-line quarter in years, reporting third-quarter earnings of $1.24 per share on record net sales of $874.3 million. That beat the $1.04 consensus estimate by 19.2% and topped revenue expectations of $772.2 million by 13.2%. Earnings grew 27.8% year over year, and revenue rose 23.3%. The revenue gain marks a sharp acceleration from 12.4% growth in the second quarter and 3% in the first, and it came in a quarter that management had guided to a sequential decline. Yet the quarter's composition is more complicated than the headline surprise suggests. Growth leaned heavily on pricing, gross margin compressed, working capital absorbed cash, and management offered its first cautious framing of 2027. That is the central tension.
The quality of the beat deserves scrutiny. Gross margin fell 110 basis points to 18.5%, a reversal from a 30-basis-point expansion in Q2 and a 100-basis-point gain in Q4 of fiscal 2025. Management attributed the decline to large-project customer mix and less netted-down software. Business Solutions took the biggest hit, with segment gross margin dropping to 23.8% from 26.5% even as segment sales rose 27.8%. Operating leverage did most of the work. SG&A fell to 13.8% of sales from 15.3%, lifting operating income 35.4% to $41.0 million and operating margin to 4.7% from 4.3%. Sequentially, however, the picture softened: operating margin trailed Q2's record 5.0%, and EPS slipped from $1.31 despite much higher sales. Lower interest income, at $2.5 million versus $3.7 million a year ago, also trimmed the bottom line.
Beneath the surface, the mix shifted decisively toward infrastructure:
- Server/storage sales jumped 45%, and networking rose 43%, together lifting their share of net sales to 17% from 14%.
- Enterprise Solutions posted record sales of $407.5 million, up 27.4% versus 13.4% growth in Q2, and entered Q4 with record backlog.
- Healthcare grew 34%, more than double Q2's pace.
- Public Sector returned to growth at 4.6%, after flat results in Q2 and a 31% plunge in Q1, with federal turning positive and SLED strong.
The endpoint business is where bears have legitimate ammunition. Notebook revenue rose more than 30%, yet units fell roughly 5%, compared with a 3% unit gain in Q2. That points to price-driven rather than volume-driven growth. The release separately flagged the global DRAM and NAND shortage as a supply risk.
The forward signals are noticeably more restrained than the quarter itself:
- Fourth-quarter revenue is guided down 3% to 4% sequentially.
- Management sees no evidence of a year-end budget flush and described budget crowding among customers.
- For the first time, management said endpoint demand may be down slightly in 2027 because the device refresh cycle is mostly behind.
For a company whose notebooks and desktops still make up 46% of sales, that is a meaningful shift. The AI and on-premises infrastructure story, backed by the record Enterprise backlog, HPE Triple Platinum Plus status and the hiring of new President and COO Matt Zafirofsky, gives the company credible levers to offset a fading PC cycle. Whether those levers can fully replace endpoint volume remains unproven.
The balance sheet shows the strain of growth. Operating cash flow was just $9.7 million in Q3, down from $64.1 million a year ago. Nine-month operating cash flow was a $39.8 million outflow as receivables and inventory ballooned. Inventory reached $226.6 million versus $143.6 million at year-end, and inventory turns slowed to 14 from 18. Cash and short-term investments fell to $343.3 million from $411.4 million in Q1. The company remains debt-free and well-capitalized, but some of the revenue surge has been funded by working capital rather than converted to cash.
Investor expectations had already cooled heading into the report. Sentiment slipped from modestly positive (0.14) after the prior report to roughly neutral (-0.02), suggesting the market was not positioned for euphoria. Price action has been constructive, though. Shares are up 5.1% since the open following July's report and sit about 23% above the 200-day moving average. They are also roughly 8.6% below the 52-week high of $96.91 set on October 13, meaning the stock had already given back part of its pre-earnings run. Most Earnings Whispers trend readings remain positive, although the sequential growth trend is negative, consistent with the guided Q4 step-down.
The bottom line is that PC Connection posted a decisive beat and its fastest growth of the year, driven by infrastructure strength and pricing tailwinds that skeptics may have underestimated. However, margin compression, falling notebook units, cash-consuming working capital and management's first cautious 2027 framing indicate that peak conditions may be close at hand. The infrastructure and backlog story keeps the growth narrative credible, but the next leg depends on proving that servers, networking and AI-related projects can carry the business as the endpoint refresh fades.
Read our earnings preview for PC Connection, Inc.: https://www.earningswhispers.com/article/CNXN/21008
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Oct-14 | |
| Oct-02 | |
| Sep-14 | |
| Aug-20 | |
| Aug-19 | |
| Aug-06 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-10 | |
| Jul-09 |
