Stepan Must Prove Its Second-Quarter Surge Outlasts Pre-Buying As Catalyst Savings Ramp
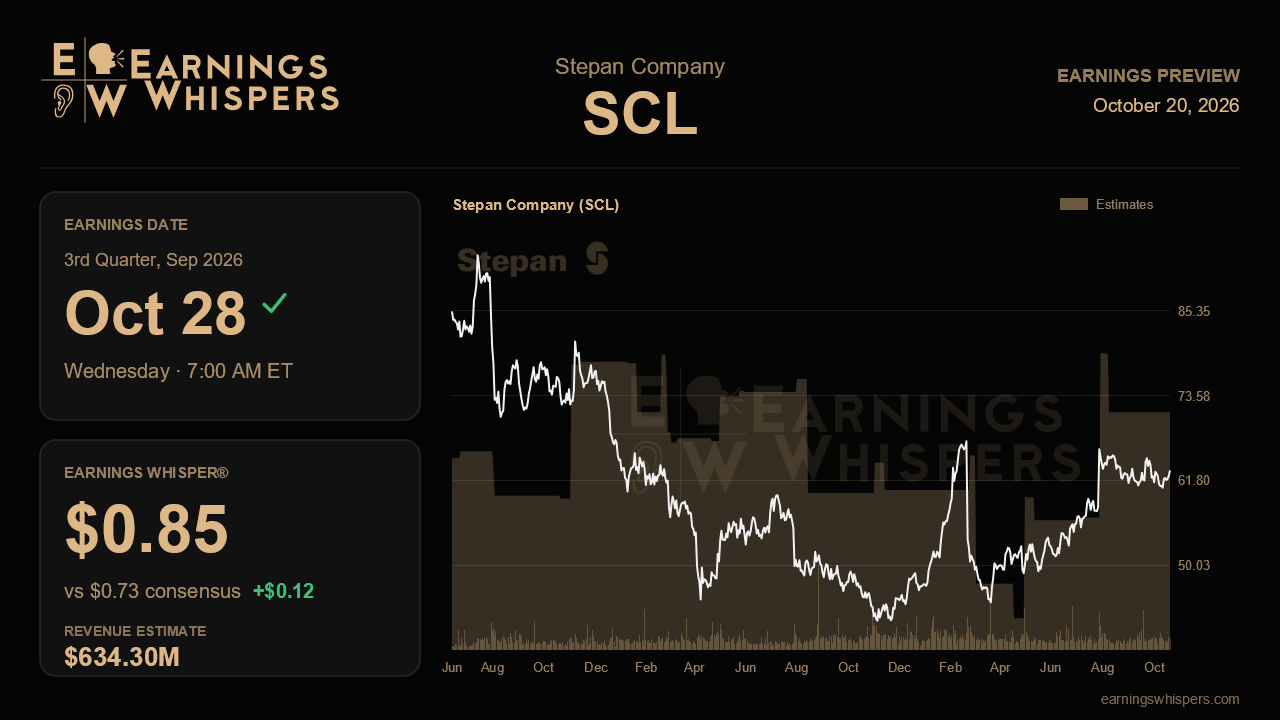
Stepan heads into its third-quarter report with an awkward but interesting problem: management already told investors this quarter would look worse than the last one. After a second quarter in which adjusted EPS jumped to $1.18 and adjusted EBITDA climbed 45% from a year earlier, the company warned that roughly $5 million to $10 million of that profit came from customers buying ahead of Iran-related raw material uncertainty. That made a sequential step down the expected outcome. The real question for the October 28 report, due before the open, is how much of the second-quarter inflection was durable once the pull-forward is stripped out.
The Street expects EPS of $0.73 on revenue of about $634.3 million. That is a sharp drop from last quarter's $1.18 and $684.1 million, consistent with management's caution, but it still implies year-over-year EPS growth of about 52% against a soft $0.48 comparison, alongside a more modest 7.5% revenue increase. The Earnings Whisper sits at $0.85, meaningfully above consensus, which suggests the more engaged crowd thinks analysts may have overcorrected for the pre-buy unwind. In practice, the bar for a convincing beat looks closer to the mid-$0.80s than the published number. Notably, the gap between revenue growth and earnings growth signals that this story rests on margins and cost savings rather than top-line momentum.
That puts Project Catalyst at the center of the report. Management said savings were running at roughly $18 million to $20 million a quarter and should exit the fiscal year near $22 million, keeping it on track for about $60 million this year and $100 million over two years. Evidence that the run rate is still climbing would validate the idea that Stepan's earnings base has reset higher. Surfactants is the other key test. Organic volume rose 7% last quarter with every region and end market contributing, a dramatic change from flat volumes in the first quarter and declines a year ago. Some giveback is expected as pre-bought inventory works through customer systems, but a return to flat or negative volumes would undercut the claim that 500 new customer and product combinations in North America are building real share. In Polymers, continued strength in North American rigid polyols and the spray foam initiative, which tripled volumes last quarter, would help offset a $4 million to $5 million maintenance turnaround and ongoing softness in European construction and Chinese demand.
Cash flow deserves equal attention. Free cash flow turned negative $15 million last quarter on a $58 million working capital build driven by higher raw material costs and sales. If that inventory and receivables build reverses as pre-buying fades, cash generation should rebound and support management's goal of positive full-year free cash flow and lower leverage from 2.5 times. Restructuring charges of $75 million to $80 million and about 100 salaried job cuts land largely in the back half, so investors should separate those costs from underlying performance, while the $30 million Joliet land sale slated for fall offers a separate deleveraging lever.
The market has not embraced the turnaround. Shares slipped about 0.5% since the last report while the S&P 500 gained 3.6%, and sentiment drifted from modestly bullish to slightly bearish. Still, at $62.41 the stock sits comfortably above its 200-day average of $56.13 and in the upper half of its post-earnings range, after trading entirely below $60.24 in the prior quarter.
Ultimately, the report hinges on whether underlying earnings, adjusted for the pre-buy unwind and turnaround cost, still show the margin recapture and Catalyst savings that powered the second quarter. If they do, and cash flow turns, the inflection narrative holds. If volumes and margins fade together, last quarter will look more like a timing quirk than a turning point.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-07 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-08 | |
| Jul-08 | |
| Apr-29 | |
| Apr-28 | |
| Apr-28 | |
| Apr-28 | |
| Apr-28 | |
| Apr-07 |
