Northeast Bank's Lower Bar Tests Whether Record Loan Origination Pace Survives Without Accretion Boost
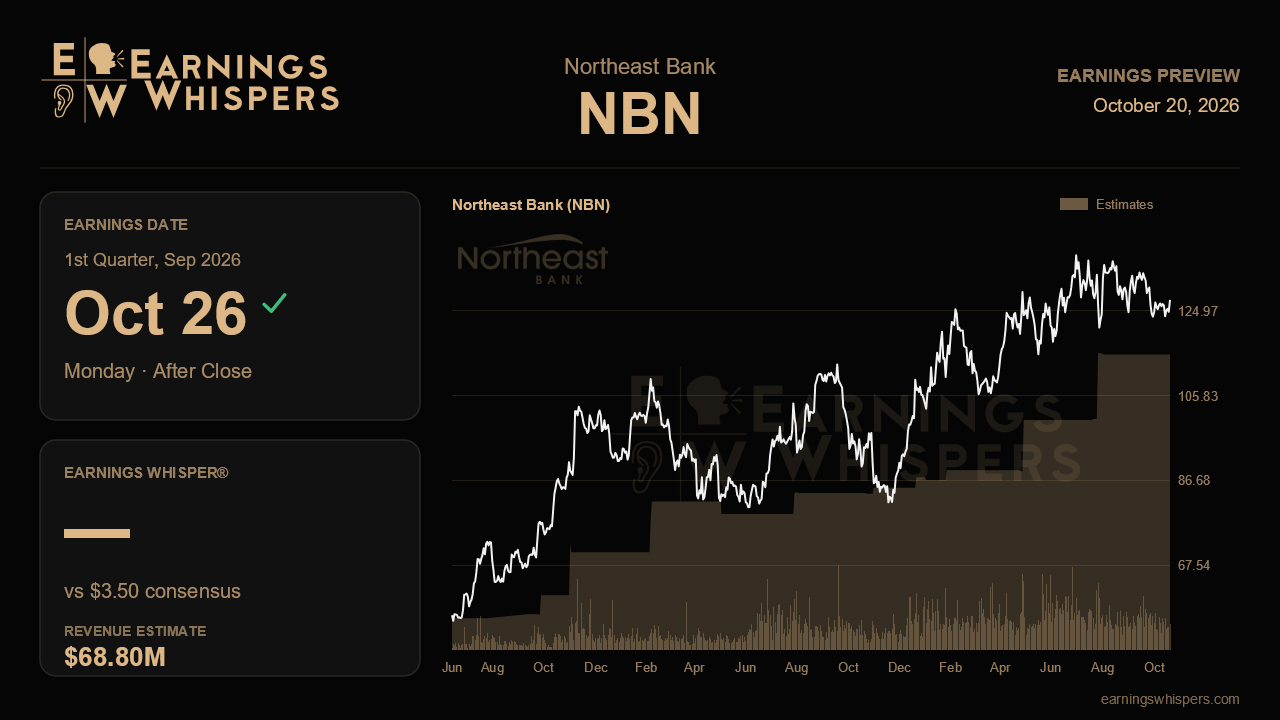
Northeast Bank heads into its fiscal first-quarter report with an unusual setup: the Street expects earnings to fall sharply from the prior quarter even though management closed fiscal 2026 sounding as confident as it has all year. That gap between a cautious consensus and an upbeat operating narrative is what makes this report worth watching. The question is whether the core lending engine can carry results now that the one-time accretion income that inflated recent quarters is fading.
Analysts are looking for earnings of $3.50 per share, well below the $4.05 posted last quarter but still up about 31% from the $2.67 earned a year ago. Consensus revenue of $68.8 million implies a roughly 22% decline from the year-ago period and a steep drop from the prior quarter's $104.7 million. Some of that likely reflects how revenue is measured, but the direction says something: the Street is modeling normalized interest income and no repeat of the transactional gains that flattered recent results. Management did not issue formal numeric guidance, but its comments last quarter amount to a framework. It described the net interest margin as roughly flat once transactional income is stripped out, signaled little further relief on funding costs, and pointed to an effective tax rate of about 28% to 29%, helped by continued purchases of transferable production tax credits.
That framework sets the tests. The margin stepped down to 4.8% last quarter from 5.15% as accelerated accretion on purchased loans cooled, and management called the earlier spike non-repeatable. A margin holding near 4.8% would validate the claim that the decline was mostly timing. A further slide would suggest funding pressure is biting, especially with about $600 million of brokered and retail certificates of deposit repricing and brokered rates edging higher. On the growth side, national lending originations set a third straight record at $257.3 million, and management described July as about as busy as it could remember. A fourth consecutive quarter near that level would confirm demand is durable; a meaningful drop-off would undercut the most important pillar of the bull case. Purchased loan volume is a swing factor too, having rebounded to about $100 million after a weak prior quarter, while management conceded that large credit funds beat it on all four big pools it pursued.
The lagging businesses deserve scrutiny. SBA volume of roughly $35 million a quarter remains far below its old pace and short of management's $20 million monthly target after repeated rule changes. The insured small-balance product, now carrying 25% insurance coverage, left about $96 million of unsold loans on the balance sheet, and any further migration into delinquency would raise credit questions after nonperforming assets improved to 67 basis points. The data warehouse rollout promised operating leverage without added headcount, so expense discipline is the early proof point.
The market has not given the company much credit. Shares are down 6.2% since the last report while the S&P 500 gained 2.9%, and at $124.75 the stock sits just above its 200-day moving average and closer to the bottom of its post-earnings range of $120.25 to $140. Sentiment remains modestly bearish, though less so than heading into the previous report, suggesting skepticism has eased slightly without turning into optimism.
With expectations already reset lower, the bar is not demanding. What matters is quality: whether a steady margin, another strong origination quarter and contained credit show that Northeast Bank's earnings power rests on its spread business rather than on accretion windfalls and tax credits. If they do, the stock's underperformance looks like an overcorrection. If not, the market's caution will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-20 | |
| Jul-27 | |
| Jul-27 | |
| Jul-27 | |
| Jul-16 | |
| Apr-29 | |
| Apr-27 | |
| Apr-27 | |
| Apr-21 | |
| Mar-26 | |
| Jan-27 | |
| Jan-27 | |
| Jan-26 | |
| Jan-26 |
