Univest Needs A Clean Quarter As Credit Questions Shadow Its Margin Momentum
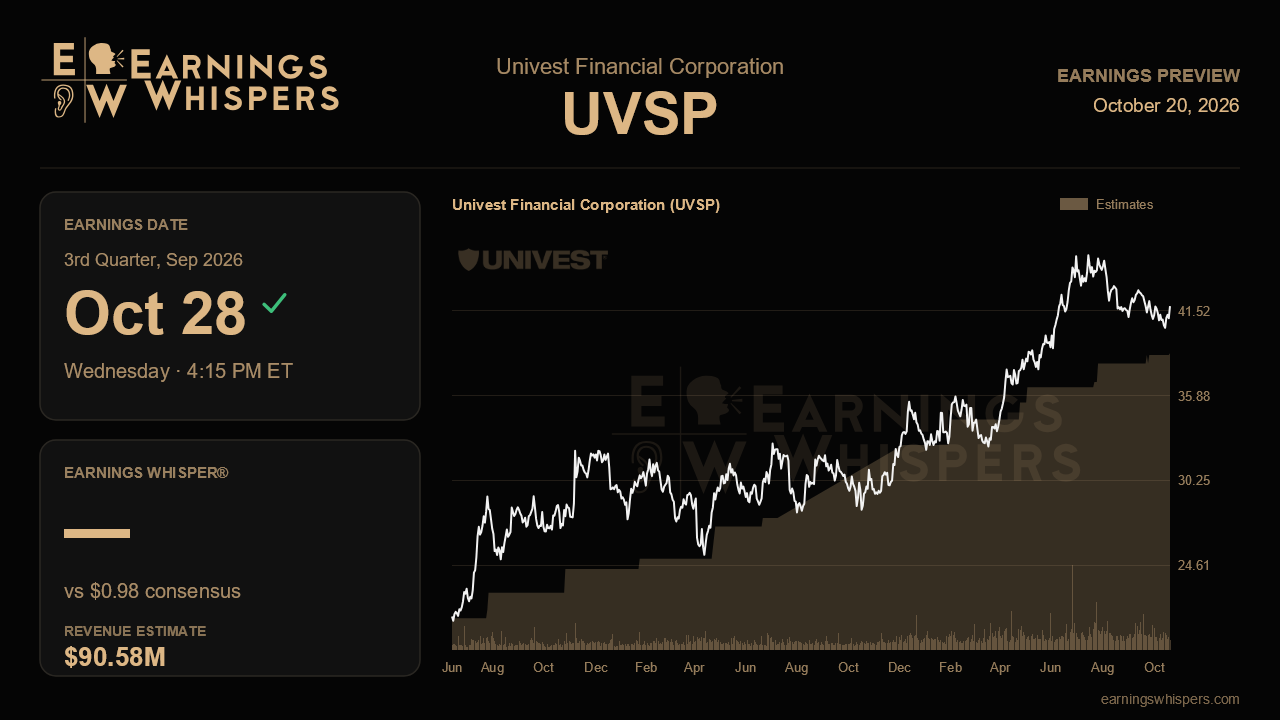
Univest Financial heads into its third-quarter report with a simple but demanding assignment: prove that last quarter's stumble was a one-off. The bank's lending and deposit franchise has been quietly strengthening, yet a $28.6 million commercial loan that slid onto non-accrual and a $5.2 million write-down on a Princeton office property turned a solid quarter into a messy one. The October 28 release, due after the close, will show whether those items were isolated blemishes or the start of a less comfortable credit chapter.
The Street is looking for earnings of $0.97 per share, up about 9% from $0.89 a year ago and a sharp rebound from the $0.82 posted last quarter. That rebound is less heroic than it looks. The REO adjustment alone cost roughly 15 cents in the second quarter, so consensus essentially assumes Univest repeats its underlying run rate without another surprise. Revenue is pegged at $90.6 million, which on paper implies a roughly 31% year-over-year drop. That figure is difficult to reconcile with a bank whose net interest income grew 11.3% last quarter, so the more meaningful yardstick is net interest income itself rather than the headline revenue comparison.
Management's full-year framework gives a useful checklist. The company reaffirmed loan growth of 2% to 3%, fee income growth of 6% to 8% excluding BOLI and REO items, expense growth of 3% to 5%, and provisioning of $11 million to $13 million. It also guided core net interest margin to hold around 3.50%, give or take about 12.5 basis points, after raising its net interest income outlook to 5% to 7% earlier in the year. Notably, that higher income target was not restated last quarter, which leaves a small question mark over whether the margin tailwind is fading. Loan growth has been running well ahead of the full-year target, at 6% annualized last quarter, so the risk is less about volume than about price.
That is the crux. Management described sharper pricing competition and narrowing spreads across every market and loan category, a noticeably more cautious tone than earlier in the year. Its response has been a tilt toward construction lending, where spreads and fees are wider. A stable or rising core margin alongside continued loan growth would validate that strategy; a margin slipping toward the lower end of the guided band would suggest competition is winning. On the funding side, management expected a seasonal build in public funds this quarter and has been cultivating deposits from unions, title companies and law firms. Healthy deposit inflows that keep funding costs contained would support the margin story.
Credit is the swing factor most likely to move the stock. Management could not promise the troubled C&I credit, tied to a seasonal manufacturer and distributor, would be resolved in 2026, and provisioning was described as event-driven. Any additional reserve against that loan, migration of other commercial credits, or a further markdown on the Princeton property would push provisions toward or beyond the top of guidance and undercut the clean-quarter assumption embedded in consensus. Steady buybacks, which accelerated to about 425,000 shares last quarter, would signal management's confidence in capital and credit.
The market has already leaned skeptical. Shares have fallen 3.8% since the last report while the S&P 500 gained 3.7%, and sentiment has turned more bearish than it was heading into the prior quarter. At $41.02, the stock sits just above its post-earnings low of $39.90, though still comfortably above its 200-day moving average. That positioning means a clean print could be rewarded, while another credit surprise could test support. Ultimately, the report hinges on whether Univest can show its growing net interest income is translating to the bottom line without fresh credit or valuation charges getting in the way.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-07 | |
| Jul-24 | |
| Jul-23 | |
| Jul-22 | |
| Jul-07 | |
| Apr-23 | |
| Apr-22 | |
| Apr-07 | |
| Mar-04 | |
| Feb-24 | |
| Feb-16 | |
| Feb-11 | |
| Feb-03 | |
| Feb-01 |
