Univest Misses As A $14.4 Million Charge-Off Eclipses An Accelerating Spread-Income Engine
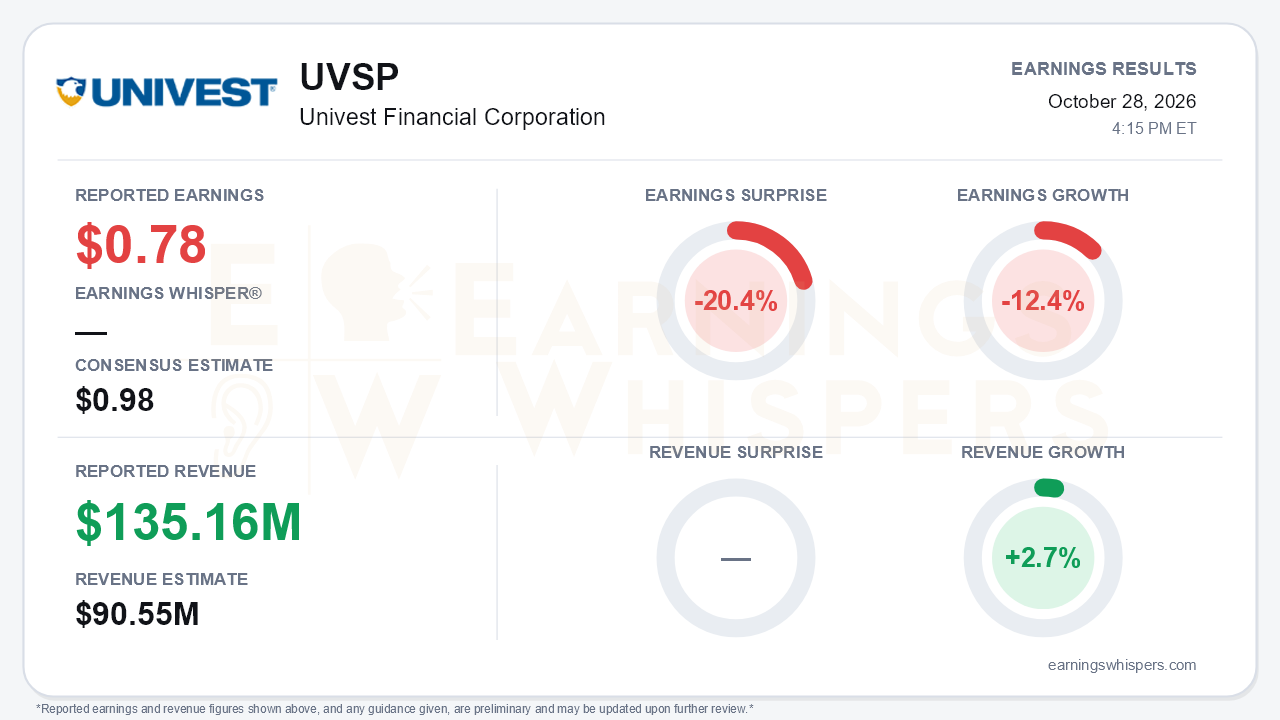
Univest Financial Corporation (NASDAQ: UVSP) reported third-quarter earnings of $0.78 per share, missing the $0.98 consensus estimate by 20.4%. Earnings fell 12.4% from a year ago, and the trend is decelerating: EPS has slid from $0.96 in the first quarter to $0.82 in the second and $0.78 now. The miss had one main cause. A commercial loan relationship that moved to nonaccrual in the second quarter produced a $14.4 million charge-off, which pushed the provision for credit losses to $9.0 million from $517 thousand a year earlier. That is the central tension. The core banking engine is running better than it has in years, but credit costs and a rising expense run-rate are consuming the gains.
The revenue line needs context. Revenue of $135.16 million beat the $90.55 million consensus by 49.3% and grew 2.7% year over year. The reported figure appears to combine gross interest income ($112.9 million) with noninterest income ($22.3 million). On a net revenue basis, net interest income of $67.8 million plus fee income totals roughly $90.0 million, essentially in line with the consensus figure. The headline revenue beat therefore reflects a difference in how revenue is defined, not an operating upside surprise.
Beneath the headline, spread income is strong:
- Net interest income rose 10.5% year over year and 2.3% sequentially.
- Reported net interest margin dipped to 3.42% from 3.49% in the second quarter, but only because excess liquidity from a $421.5 million seasonal deposit surge diluted it by about 13 basis points.
- Excluding that drag, core margin edged up to 3.55% from 3.53%, extending a steady climb from 3.37% in the fourth quarter of 2025.
- Management raised full-year NII growth guidance to 10-11%. That compares with 5-7% in the first quarter and 4-6% originally.
- Pre-provision, pre-tax earnings were roughly $36.0 million, up about 10% from a year ago.
- The efficiency ratio improved to 59.5% from 62.3% in the second quarter.
The rest of the guidance moved the wrong way:
- Provision guidance rose to $15-17 million from the $11-13 million held since January.
- Expense growth guidance increased to 5-6% from 3-5%, driven by staffing, medical costs and a university sponsorship.
- Fee income guidance was trimmed to 5-7% from 6-8%.
The credit picture is more nuanced than the charge-off alone suggests, and bears have legitimate ammunition. Net charge-offs of $17.6 million (0.99% annualized) far exceeded the $9.0 million provision, because the relationship's $9.8 million specific reserve absorbed part of the loss. As a result, allowance coverage fell to 1.15% of loans from 1.28%, a level that had held for four straight quarters. The thinner reserve cushion matters if credit softens further. Management did offer some offsets:
- Nonperforming assets declined to $51.4 million from $63.0 million.
- The remaining carrying value of the troubled credit is supported by a letter of intent to sell the business.
- Management expects criticized and classified loans to fall $35-40 million in the fourth quarter.
If that improvement materializes, the third quarter may prove to be a cleanup quarter rather than the start of a credit cycle. Investors will want evidence before granting that benefit of the doubt.
Growth drivers look less encouraging. Loans fell $27.5 million sequentially after a $101.7 million gain in the second quarter, reflecting a planned $35.3 million shared national credit payoff and the charge-off. Management also described several headwinds:
- Commercial real estate borrowers are pausing new projects as rates rise.
- Structural runoff in residential mortgages continues.
- Loan growth of roughly 2-3% is likely to persist into 2027.
- Deposit competition is fierce, with aggressive CD and checking offers expected to pressure 2027 funding costs.
- Seasonal public funds should run off about $100 million per quarter through June 2027.
That combination makes the expected margin gains (slight expansion in the fourth quarter and a couple of basis points possible in 2027) more fragile than the raised NII guide implies. On the positive side, management signaled greater openness to bank, wealth and insurance acquisitions and continued buying back stock. It repurchased 301,127 shares in the quarter at an average of $42.50, roughly where the stock trades today. Tangible book value per share rose to $28.27.
Investor sentiment was already negative and slipped modestly further, from -0.46 to -0.51. That is a mild deterioration, not a capitulation. The stock has gone essentially nowhere since the last report: at $42.08, it sits 1.3% below the $42.65 opening after the July release. It remains 7.4% above its 200-day moving average of $39.17, so the longer-term trend has not broken. The Earnings Whispers trend readings lean negative, with AVWAP negative and price trend neutral, consistent with a stock that has stalled rather than one being actively sold.
The bottom line is that Univest's spread franchise is clearly improving, with rising core margin, double-digit NII growth and better efficiency. However, this quarter showed how quickly a single credit can overwhelm those gains when loan growth is modest and expenses are rising. The higher provision and expense guides, a thinner reserve and softening loan demand leave the earnings recovery dependent on credit normalizing in the fourth quarter. Until criticized loans actually decline as promised, the market is likely to treat the margin story as necessary but not sufficient.
Read our earnings preview for Univest Financial Corporation: https://www.earningswhispers.com/article/UVSP/20994
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-28 | |
| Oct-20 | |
| Oct-07 | |
| Jul-24 | |
| Jul-22 | |
| Jul-07 | |
| Apr-22 | |
| Apr-07 | |
| Mar-04 | |
| Feb-24 | |
| Feb-16 | |
| Feb-11 | |
| Feb-03 | |
| Feb-01 |
