Sprouts Needs Proof Its Comp Slide Has Bottomed After A 27% Stock Drop
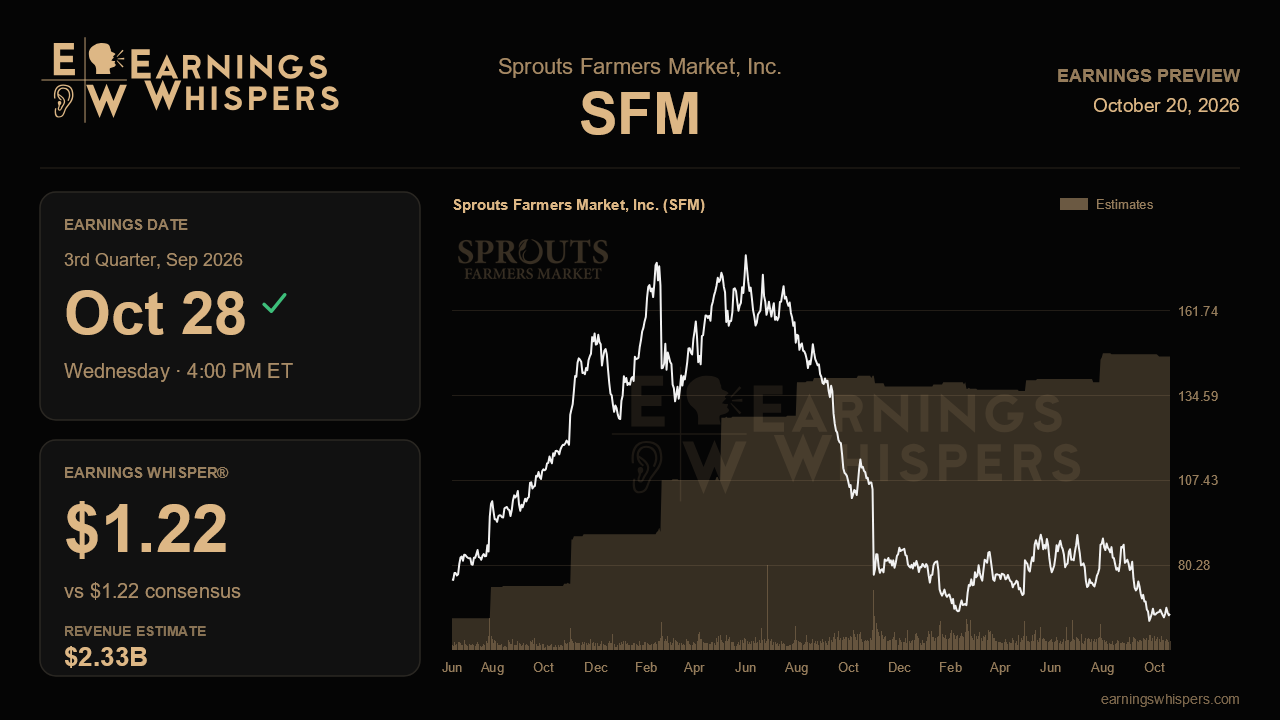
Sprouts Farmers Market heads into its third-quarter report with a message that has grown harder to sell: the toughest comparisons are behind it, and same-store sales should drift back toward its long-term algorithm. The market has stopped taking that on faith. Shares have fallen 26.6% since the last report while the S&P 500 gained 4.1%, so this release is less about a penny of upside and more about whether the comp trend has finally turned.
The Street's bar sits right where management put it. Consensus calls for EPS of $1.22 on revenue of about $2.33 billion, which matches the midpoint of the company's $1.20 to $1.24 guidance. The Earnings Whisper is also $1.22, so there is no hidden optimism in the number. That forecast implies flat earnings from a year ago against revenue growth of roughly 5.9%, a gap that says it all. Sales are still expanding on new stores, but margins are absorbing the growth. Analysts were near $1.28 for the quarter before the outlook was issued, so estimates have already been marked down to fit the company's view.
The trimmed full-year guidance shapes the setup. Management cut 2026 EPS to $5.32 to $5.40 from $5.32 to $5.48 and lowered revenue to $9.08 billion to $9.17 billion from $9.20 billion to $9.38 billion. The stated driver on the last call was about $5 million of extra fuel cost, roughly $2.5 million a quarter in the back half, plus a fresh cyclospora outbreak that hit lettuce and salads late in the second quarter and pushed shoppers toward frozen alternatives. Gross margin, which slipped 12 basis points to 38.7% in the second quarter on loyalty spending and fuel, is now expected to dip slightly in the third quarter rather than hold flat or rise. A margin decline close to that slight description would validate guidance. Anything sharper would suggest the affordability and loyalty investments are costing more than planned.
Comparable sales are the real test. The trend went from +5.9% a year ago to +1.6%, then -1.7%, then -1.0% last quarter, with July running slightly negative even as management said the month was improving as expected. Because this quarter laps that +5.9% figure, a print near flat would be a respectable sign of stabilization, while another drop below -1% would challenge the claim that the worst is over. The full-year comp range of -0.5% to +0.5% leaves limited room for slippage. Commentary on affordability tests matters as well, since last quarter they lifted unit sales but failed to bring in enough traffic, especially among lower-income, less engaged shoppers.
There are real offsets. The company planned its largest opening quarter ever, at least 15 stores, as part of a raised goal of 42 net new units this year, and newer stores have been comping positively. E-commerce accelerated to 12% growth and about 16% of sales, private label holds at 26%, and the completed meat self-distribution rollout plus early vendor funding of the loyalty program are levers that could support margins in 2027. The cost of those openings, however, may weigh on near-term profit, which partly explains why EPS is expected to stand still.
Investors are not leaning in. Sentiment has cooled to barely bullish from a modestly positive reading last quarter, and the $64.26 share price sits well below the 200-day average of $77.07 and only a few percent above the post-earnings low of $61.88. That pessimism lowers the bar, but it does not remove it. The report will hinge on whether comps show genuine stabilization and whether management can hold the full-year range without another cut. If both hold, the case for a return to growth survives. If comps slip again and guidance moves lower, the story shifts from a pause in momentum to a deeper reset.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-16 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Sep-30 | |
| Sep-22 | |
| Sep-14 | |
| Sep-14 | |
| Sep-04 | |
| Sep-01 | |
| Sep-01 | |
| Aug-17 | |
| Aug-17 | |
| Jul-30 |
