Sprouts Farmers Market Narrowly Misses, Then Resets The Story: Guidance Slashed, Margins Sacrificed For Price As Traffic Erodes
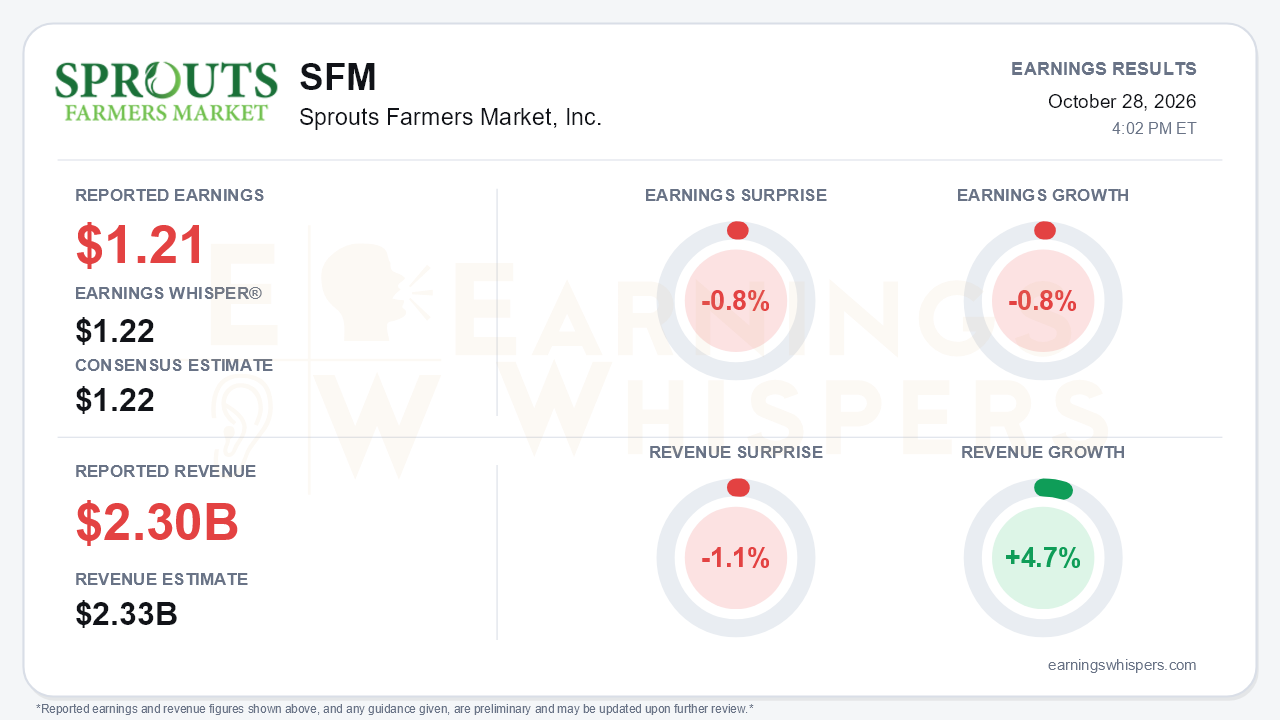
Sprouts Farmers Market (NASDAQ: SFM) missed by only a penny, but the third quarter matters for what came after it. Diluted EPS of $1.21 trailed both the $1.22 consensus and the $1.22 Earnings Whisper number by 0.8%, and earnings fell 0.8% from a year ago. Revenue rose 4.7% to $2.305 billion, which was 1.1% short of the $2.33 billion consensus. The real news was a broad guidance cut, a CEO transition, and management's admission that its pricing strategy "has not delivered." The company is deliberately giving up gross margin to win back shoppers. That makes this quarter a break in the Sprouts growth narrative rather than a modest stumble.
The headline EPS also flatters the underlying trend. Net income fell to $113.4 million from $120.1 million, and EBIT slipped to $152.8 million from $157.4 million. EPS held near flat mostly because diluted shares dropped to 93.7 million from 98.7 million after aggressive buybacks. Comparable store sales declined 0.9%, below the -0.5% to +1.5% range implied by second-quarter guidance. Underneath that, transactions fell 3.3% while basket size rose 2.5%. Management attributed roughly 60 basis points of the comp decline to the cyclospora disruption, but that does not explain the traffic problem. Gross margin fell 50 basis points to 38.2% on shrink, cyclospora and fuel costs. That is a clear step up from declines of about 12 basis points in Q2 and 20 basis points in Q1, so margin erosion is accelerating rather than stabilizing.
The conference call was the more damaging event. Management said comps softened in August and September and did not recover even against easier comparisons. It characterized the pressure as not cyclical. Weakness is also spreading from less-engaged shoppers to core customers, who are buying fewer units and making fewer trips, while competition intensifies and customers migrate to value channels. Shrink, which was expected to provide a fourth-quarter tailwind, is instead getting worse. The tone shift is stark: in Q2 management described results as in line and expressed confidence in returning to its growth algorithm. Now it is calling for an explicit reset and will not give a 2027 view until February.
The guidance cuts were extensive:
- Full-year comps now expected at about -1.7%, down from -0.5% to +0.5%.
- Sales growth cut to about 4.3% from 5.5%-6.5%.
- EBIT lowered to about $605 million from $675-$685 million.
- EPS reduced to about $4.80 from $5.32-$5.40, all on a 52-week basis.
- Fourth-quarter comps guided to -2% to -4%, with EPS of $0.47 to $0.51.
- Fourth-quarter gross margin expected to deleverage about 90 basis points and SG&A about 170 basis points, reversing the slight gross-margin benefit previously expected.
- The estimated contribution from the 53rd week trimmed to $0.16 per share from $0.21.
- The long-term margin commitment reduced to an EBIT margin simply "above 5%."
There are still real assets here. Sprouts opened a record 15 stores in the quarter, reaching 504. The 2026 store vintage is outperforming, and recent vintages are comping positive. The 42 net new store target was reaffirmed, and the pipeline now exceeds 160 approved stores. E-commerce grew 12% and now accounts for more than 16% of sales, with Shipt added as a fourth platform. Sprouts Brand holds steady at about 26% of sales. The balance sheet carries $229 million in cash and an undrawn $600 million revolver, and buybacks are now expected to exceed $300 million for the year.
The forward catalysts center on execution:
- Incoming CEO Nick Konat takes over, with Jack Sinclair moving to Executive Chairman.
- A rebuilt national pricing strategy launches in January 2027, featuring broader and deeper investment in entry price points and conventional produce.
- Holiday price cuts arrive in the fourth quarter.
Bears have legitimate ammunition, though. Management is considering slowing unit growth to protect profitability. That would weaken the one pillar that held up this quarter, and the scale of the price investment remains undefined.
The market had already priced in much of the deterioration before the report. Shares stood at $64.41 going into the release, down 26.4% from the $87.57 open after the July report and 31% below the $93.32 inter-earnings high set that same day. The stock was 16% below its 200-day moving average and only 4.1% above the 52-week low of $61.88 set on September 28. Investor sentiment slipped from modestly positive (0.10) to slightly negative (-0.05). That is a meaningful cooling, but it is not capitulation. The Earnings Whispers price, momentum and AVWAP trend readings are all negative, consistent with sustained selling.
The bottom line is that the small EPS miss understates how much changed. Sprouts is no longer framed as a margin-expanding growth retailer. It is a company sacrificing near-term profitability to repair traffic, under new leadership, with no 2027 roadmap yet. The depressed share price reflects significant skepticism. Upside now depends on evidence that the January pricing reset restores trips without permanently impairing margins.
Read our earnings preview for Sprouts Farmers Market, Inc.: https://www.earningswhispers.com/article/SFM/20987
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 1 hour | |
| 4 hours | |
| 4 hours | |
| Oct-24 | |
| Oct-20 | |
| Oct-16 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Sep-30 | |
| Sep-22 | |
| Sep-14 | |
| Sep-14 | |
| Sep-04 |
