Service Corp Must Prove Funeral Volume Stabilization Can Rescue Margins As Stock Lags
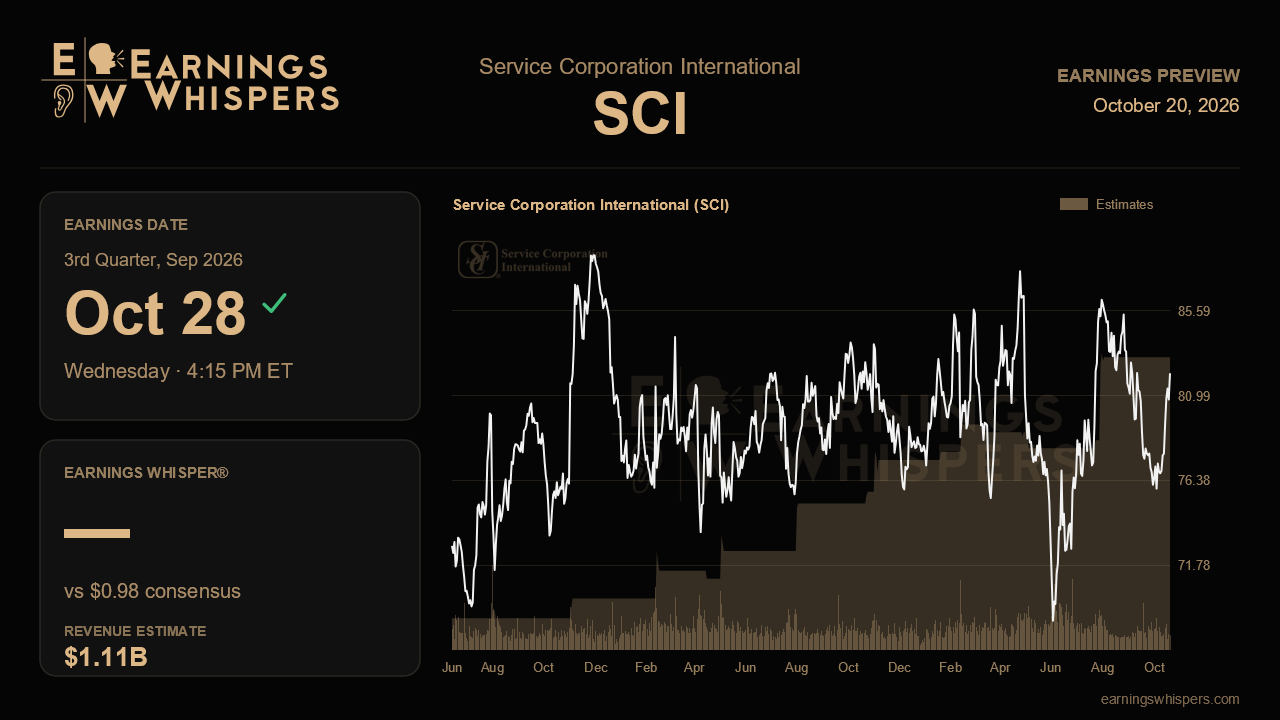
Service Corporation International heads into its third-quarter report with an odd disconnect. Last quarter, management sounded more confident than it had all year, pointing to stabilizing funeral volumes, compounding pre-need sales and a fatter cash flow outlook. The stock has fallen about 10% since then while the S&P 500 gained roughly 4%. The October 28 release, due after the close, is the first real chance to show whether the improving story was real or just a good quarter of talking points.
The Street expects earnings of $0.98 per share on revenue of about $1.11 billion. That would be EPS growth of roughly 12.6% on revenue growth near 4.9%, a healthy spread that depends on operating leverage rather than a surge in demand. The math fits management's framing of double-digit EPS growth in the second half. The full-year picture is more cautious. The company narrowed its 2026 range to $4.10 to $4.30 and kept the $4.20 midpoint. Consensus sits at $4.15, inside the range but below the midpoint. Analysts are not betting against the guide, but they are not giving management full credit either. A solid third quarter that keeps the midpoint in reach could close that gap.
The most important operating test is funeral volume. Core funeral services fell 6.6% in the first quarter against a tough flu comparison. The decline narrowed to 1.7% in the second quarter, with June slightly positive and July roughly flat. If third-quarter volumes come in around flat or better, the first-half weakness looks like a comparison problem rather than a trend. A slide back into meaningful declines would undercut the stabilization story. It would also add weight to management's own warning that post-COVID mortality normalization could weigh on 2027.
Margins are the bigger swing factor for earnings. Funeral gross margin fell to 18.5% in the second quarter, down 130 basis points from a year earlier and well below the 21%-plus posted in the prior two quarters. Management blamed temporary items. These included a cancellation reserve of roughly 200 basis points tied to a vendor transition, a shift toward insurance-funded pre-need that pulls selling costs into the current period, and a $5 million urn-delivery deferral that does not lap until the fourth quarter. Visible progress on the vendor-related reserve would support the claim that these pressures are fading. Another quarter stuck near 18% would make the second-half double-digit growth framing harder to believe.
On the cemetery side, pre-need production grew 8% in the second quarter after 10% in the first. Large sales approached $50 million. Continued high-single-digit production would confirm demand is intact, but much of it lands in backlog rather than current earnings, so cemetery margins near 33% may not move much. Updates on the cremation-in-cemetery rollout, which expanded broadly in July with full network coverage targeted for early 2027, would help investors gauge whether it can become a real growth lever. Management also raised adjusted operating cash flow guidance to a $1.085 billion midpoint and targets $750 million in free cash flow, helped by solar tax credits. Reaffirming those figures matters, as does any clarity on refinancing $137 million of 7.5% notes now coming due.
Sentiment has edged from mildly bearish before last quarter to roughly neutral. The stock, near $80.78, sits just above its 200-day moving average and closer to the bottom of its post-earnings range of about $76 to $91. The bar is not high. The central question is whether funeral margins begin recovering alongside steadier volumes. If they do, the confirmed $4.20 midpoint looks credible and the recent selloff looks overdone. If they don't, the earnings recovery management promised for the second half starts to slip.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-02 | |
| Sep-22 | |
| Sep-15 | |
| Aug-05 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-16 | |
| Jun-11 | |
| May-06 | |
| Apr-30 | |
| Apr-29 |
