SCI Slashes 2026 Outlook After Narrow Miss As Soft Funeral Volumes And Rising Costs Overshadow Strong Preneed Sales
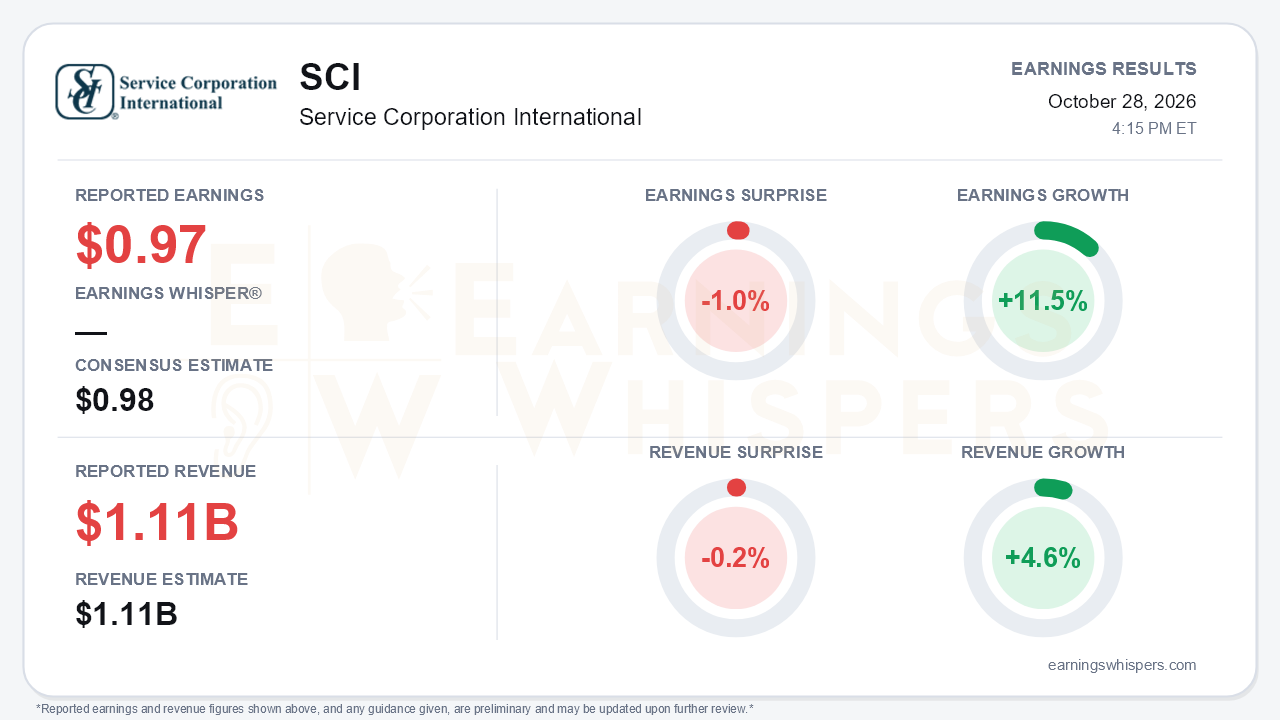
Service Corporation International's third quarter looks like a modest miss, but the more important development was the guidance cut. Adjusted EPS of $0.97 rose 11.5% from a year ago and came in 1.0% below the $0.98 consensus. Revenue of $1.107 billion grew 4.6% and missed by 0.2%. SCI lowered its full-year adjusted EPS outlook to $3.94-$4.04. The midpoint is now roughly $3.99, down from the $4.20 midpoint management had reaffirmed on the second-quarter call, and the fourth-quarter guide of $1.10-$1.20 came in below estimates. Last quarter, management had pointed to double-digit second-half EPS growth and margin expansion. That story has been withdrawn, and management told listeners it was disappointed with results that fell short of internal expectations.
The quality of the 11.5% growth deserves scrutiny. Revenue rose $49 million, but gross profit rose only $6.7 million. Much of the earnings improvement came from below the gross-profit line:
- Corporate G&A fell to $30.6 million from $38.3 million, mainly on lower long-term incentive compensation tied to total shareholder return, which is a product of the stock's weakness, plus a favorable legal settlement.
- Diluted shares fell to 137.2 million from 141.4 million.
- Trust fund income contributed roughly $0.12 of EPS above plan, and endowment care income pushed other cemetery revenue up 19.7%.
GAAP EPS of $1.03 was flattered further by $11.2 million of gains on excess land sales. Beneath those supports, comparable funeral gross margin held flat at 17.6%, short of the original target of 20-60 basis points of expansion. Comparable cemetery gross margin fell 110 basis points to 33.2%.
The call exposed two problems that are moving in the wrong direction.
- **Volumes.** Comparable core funeral services fell 0.5%, and atneed services fell 1.3%. Management had expected an increase. The second quarter's -1.7% decline and stabilizing July had suggested the post-COVID volume drag was fading. Instead, October volumes are down, fourth-quarter volumes are expected to decline slightly, and full-year volume is now about 200 basis points below plan, roughly an $0.18-$0.20 headwind.
- **Costs.** Fixed-cost growth accelerated to 4.1% from 2.7% in the second quarter and about 1% in the first, driven by healthcare, fuel, and media spending.
Pricing remains intact. Comparable average revenue per service rose 2.8%, and matured preneed averages climbed 4.4%. Pricing alone, however, is not absorbing flat volumes and faster cost growth.
The bull case rests on preneed, and here the numbers were genuinely strong:
- Comparable funeral preneed sales production rose 6.1%.
- Cemetery preneed production rose 4.8% in the quarter and about 7.5% year to date.
- Management raised its full-year cemetery production outlook to 6-7%.
Part of the margin pressure is timing rather than deterioration. The cemetery recognition rate slipped to 96.6% from 97.6%, deferring roughly $6 million into backlog. The new guaranteed-wage sales compensation plan also moves selling costs into the current period instead of deferring them, a gross-profit hit of about $5 million. Management expects these effects to ease in 2027 as the compensation change anniversaries. It also expects general agency commission rates to improve, after they were pressured by a shift to single-pay contracts and higher cancellation reserves.
Other 2027 catalysts include:
- a nationwide rollout of cremation memorialization by early 2027;
- waves of price increases;
- cost reviews targeting fleet and promotional spending;
- $34 million of fourth-quarter acquisitions;
- an easier first-quarter volume comparison.
Management expects 2027 growth to land within its long-term EPS algorithm. That is an expectation, not a result, and it comes from a team that just missed its own forecast.
Cash flow remains the cleanest part of the story. Adjusted operating cash flow rose 11% to $296.9 million. Full-year guidance of a $1.085 billion midpoint was maintained, implying about $750 million of adjusted free cash flow. SCI has returned $464 million to shareholders year to date, and leverage eased to 3.7x. Bears still have legitimate ammunition here. The $29.9 million working-capital benefit was largely payroll timing. Combined trust funds also returned -0.7% in the third quarter, so the trust-income tailwind that rescued this quarter is not guaranteed to repeat.
The market had already been leaning skeptical. Shares fell 8.5% from the $89.95 open following the July report to $82.33, about 2.9% above the 200-day moving average near $80. Investor sentiment remained slightly negative but improved modestly, from -0.093 to -0.047. That suggests expectations were tempered rather than washed out heading into a guidance reset of this size. The Earnings Whispers price and AVWAP trend readings remained positive despite the slide. That leaves the stock in a fragile position just above its longer-term average.
The bottom line is that SCI delivered double-digit adjusted EPS growth and strong preneed momentum, but the quarter relied heavily on lower incentive compensation, buybacks, and trust income, while the core funeral business underdelivered. A guidance cut of more than $0.20 at the midpoint, soft October volumes, and accelerating fixed costs shift the debate from near-term execution to whether the preneed backlog and 2027 cost actions can restore the earnings algorithm.
Read our earnings preview for Service Corporation International: https://www.earningswhispers.com/article/SCI/20986
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-02 | |
| Sep-22 | |
| Sep-15 | |
| Aug-05 | |
| Jul-29 | |
| Jul-29 | |
| Jul-16 | |
| Jun-11 | |
| May-06 |
