Plexus Must Prove Its Ramp Can Generate Cash As Stock Lags A Raised Outlook
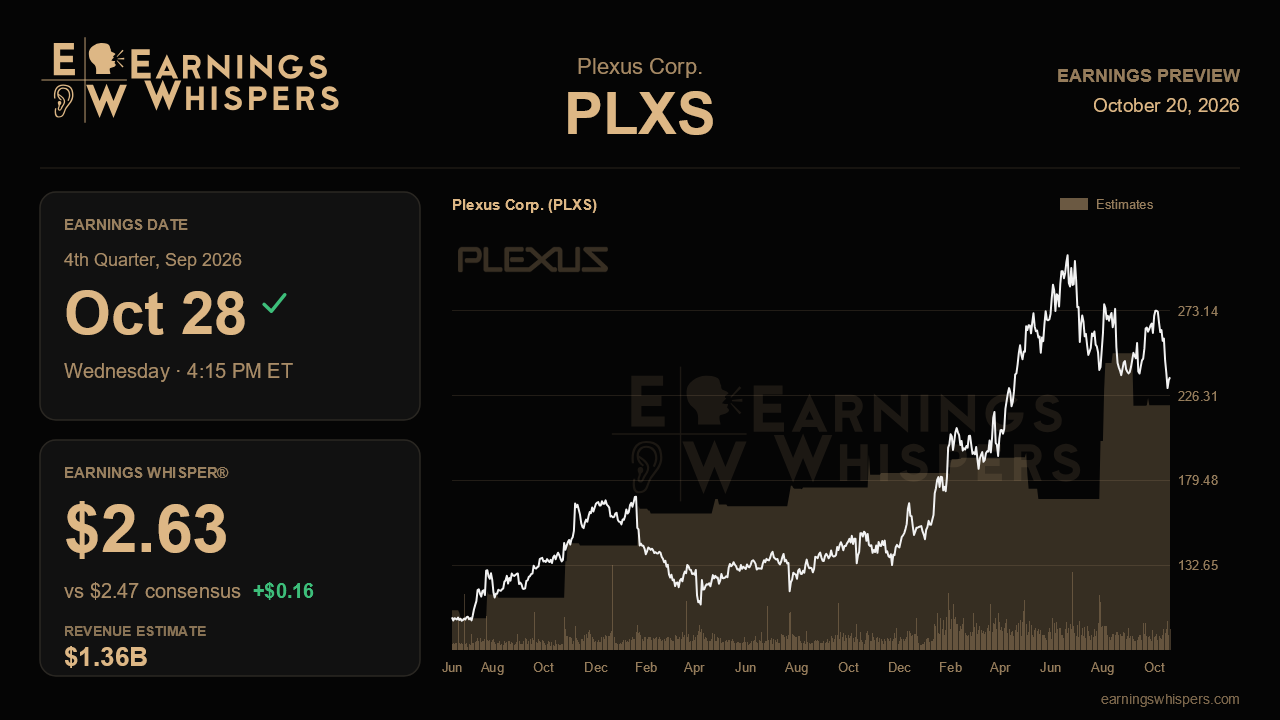
Plexus heads into its fiscal fourth-quarter report with an odd disconnect. Management has raised its full-year revenue growth outlook three times, from roughly 9% to 12% a year ago to more than 20% now, and delivered earnings at or above the top of guidance every quarter. Yet the stock has fallen 5.3% since the last report while the S&P 500 gained 4.1%. The market seems to be asking something the income statement alone cannot answer: when does all this growth start producing cash?
The numbers themselves set a demanding but well-defined bar. Consensus calls for non-GAAP earnings of $2.47 per share on revenue of $1.36 billion, which would be roughly 28.5% revenue growth from the year-ago quarter. Management guided to $2.47 to $2.63 on revenue of $1.33 billion to $1.38 billion. Analysts have moved up sharply since that guidance was issued, but they are sitting exactly at the low end on earnings and in the upper half on revenue. The Earnings Whisper of $2.63 matches the top of the range, implying that the more aggressive expectation is for Plexus to repeat its habit of landing at or above the high end. Given that third-quarter EPS of $2.32 came in above guidance and the company has beaten its own targets consistently, an in-line print at the bottom of the range would likely read as a stumble rather than a success.
The operating story to validate rests on breadth. Last quarter, revenue hit a record $1.305 billion, industrial sales jumped 23% sequentially on semiconductor-capital-equipment share gains, and operating margin reached 6.3%. Management did flag a pause in two engines, guiding both aerospace and defense and healthcare roughly flat sequentially, the latter because of program-ramp delays. That means industrial strength must carry the quarter. Confirmation that semi-cap momentum held, and that healthcare delays are timing rather than lost business, would support the thesis. Any sign that the flattening is spreading would challenge it, especially with healthcare growth already expected to slow to mid-single digits next year.
Forward indicators matter even more. The manufacturing opportunity funnel climbed to a record $4.5 billion, and aerospace and defense wins year to date reached $400 million, more than double the prior two years combined. New catalysts include a battery energy storage partnership for data centers already in production in Bangkok, a data-center power and thermal funnel of about $500 million, and a Malaysia expansion adding more than $500 million of capacity. Investors should want evidence these are converting into revenue, plus more specifics on the preliminary fiscal 2027 outlook, which management said would exceed its 9% to 12% goal with margin expansion.
Cash is the soft spot. The fiscal 2026 free cash flow target slid from about $100 million to $50 million to $75 million, and management guided the fourth quarter to roughly breakeven or slight usage, pushing meaningful cash generation into fiscal 2027. Tightening supplies of semiconductors, memory, passives and circuit boards are forcing inventory pre-positioning, and interest expense is creeping higher. A firmer commitment to over $100 million of free cash flow next year, ideally with customer-funded inventory easing the burden, would address the market's skepticism directly.
Sentiment has improved from bearish ahead of last quarter to modestly bullish now, but the chart tells a more cautious story. At about $235, the stock sits just below its 200-day moving average and near the bottom of its post-earnings range of $230 to $298. That leaves room for relief if Plexus beats and backs up its fiscal 2027 confidence with a credible cash path. The narrative stays intact if growth converts into cash; another quarter of rising revenue with deferred free cash flow may not be enough to close the gap between the business and the stock.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Aug-27 | |
| Aug-12 | |
| Aug-03 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| Jun-12 | |
| Jun-01 | |
| May-24 | |
| Apr-30 | |
| Apr-29 | |
| Apr-29 |
