Plexus Beats And Raises The Bar, But Cash Generation And A Softer Q1 Margin Guide Temper The Victory Lap
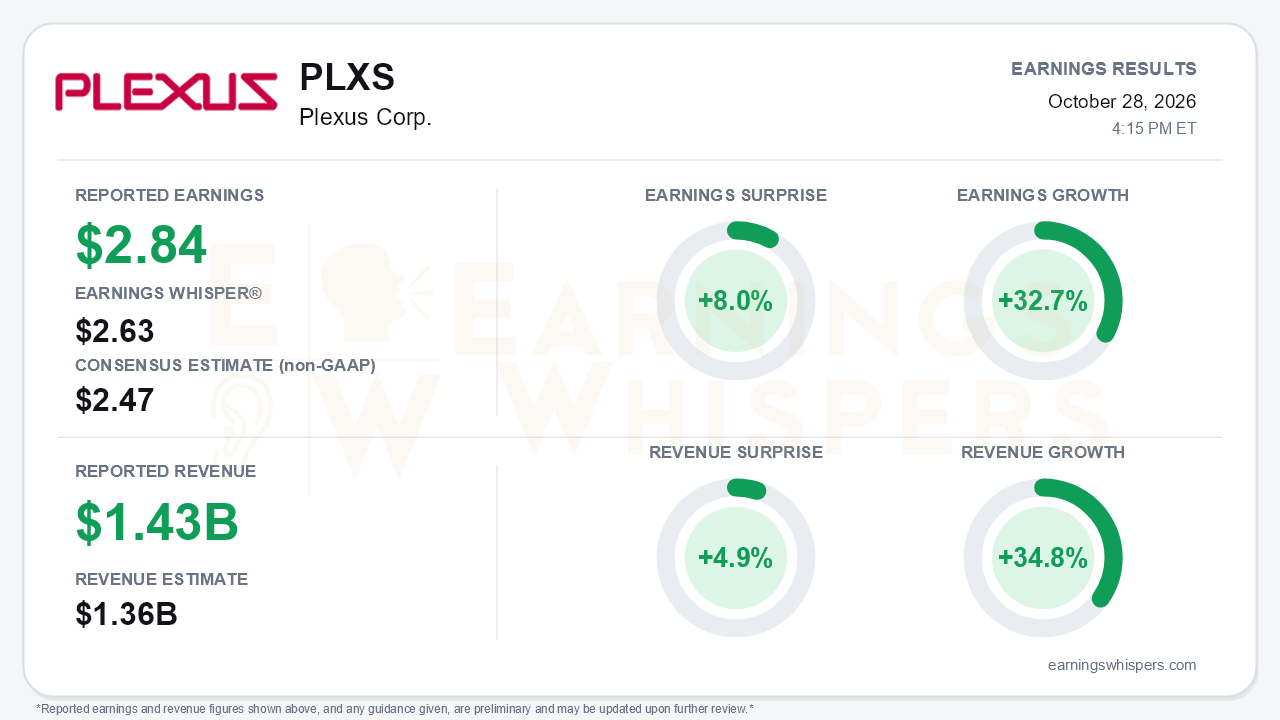
Plexus closed fiscal 2026 with one of its strongest quarters in years. Non-GAAP EPS of $2.84 beat the $2.47 consensus by 8.0% and cleared the $2.63 Earnings Whisper number. Revenue of $1.427 billion topped the $1.36 billion consensus by 4.9%. Earnings grew 32.7% year over year and revenue grew 34.8%, so the top line is now expanding at a pace that would have been hard to imagine when management opened the year guiding to the high end of 9-12%. Revenue, non-GAAP operating margin of 6.7%, and EPS all landed above the guidance ranges. Management then lifted fiscal 2027 growth to mid-to-upper teens and introduced a new 6.5%-7.0% operating margin goal. The central tension is that the income statement and the cash flow statement are telling different stories about how cleanly this growth is being funded.
The quality of the earnings beat itself holds up well. GAAP operating margin rose to 6.0% from 5.0% a year ago and 4.7% in the third quarter. The Q3 figure was depressed by $12.9 million of accelerated stock compensation tied to executive retirements. Gross margin edged up to 10.2%, and non-GAAP operating margin has stepped up from 5.8% a year ago to 6.3% last quarter to 6.7% now. That is genuine operating leverage. Management cited equipment efficiency gains of more than 10% and revenue per employee up roughly 20-25%. ROIC climbed every quarter of the year, from 13.2% to 15.8%, comfortably above the company's 15% goal.
Cash is where the story weakens. Fiscal 2026 free cash flow was a $28.9 million outflow. The company originally targeted about $100 million and cut that to $50-75 million at midyear. Inventory jumped by roughly $448 million and receivables by $285 million. Those increases were funded largely by suppliers and customers: payables rose $417 million and advanced payments $116 million. That is why the 62-day cash cycle looks pristine even as the balance sheet swelled. Current debt rose to $179.5 million from $45.8 million, and quarterly interest expense roughly doubled. Management reaffirmed at least $100 million of fiscal 2027 free cash flow, but it also flagged a first-quarter cash use and capex toward the upper end of its range. Investors have heard a $100 million target before.
The call did more than paper over those issues. It preserved a credible growth story with unusually broad support. Both Aerospace/Defense and Industrial are expected to grow more than 20% in fiscal 2027. Healthcare/Life Sciences was raised to high single digits from at least mid-single digits, and its engineering funnel showed a marked uptick that management described as a historical leading indicator. Semicap grew about 50% in fiscal 2026. Record A&D wins of $490 million exceeded the prior three years combined. The qualified funnel has climbed every quarter to a record $4.9 billion, up 33% year over year. Quarterly wins of $290 million added new customers in defense pilot training, robotic surgery imaging, and battery energy storage.
The near-term guide is less exuberant than the full-year outlook:
- **Revenue:** Q1 revenue of $1.41-$1.46 billion is up only about 1% sequentially, though roughly 34% year over year.
- **Margin and EPS:** The non-GAAP margin guide of 6.0%-6.4% steps down from 6.7% as investment rises, and non-GAAP EPS of $2.46-$2.62 sits below the quarter just reported.
- **Segments:** Industrial is expected down low single digits sequentially on communications normalization, and A&D slipped 4% sequentially in Q4 on materials timing.
- **Flow-through:** Incremental margins are tracking at the low end of the 8-12% range.
- **Concentration:** Top-10 customer concentration rose to 56% from 49% a year earlier.
None of these points derails the thesis, but bears have legitimate ammunition on durability and concentration, especially with semicap cyclicality in the mix and management declining to look past fiscal 2027.
Investor sentiment shifted meaningfully, from -0.23 before the prior report to +0.18. That moves from mildly negative to modestly positive. The stock has not followed. At $239.34, shares are down 3.5% since the open after the July report and sit essentially on their 200-day moving average of $239.56. The company bought back $21.4 million of stock in the quarter at an average of $254.32, above where shares now trade. Earnings Whispers trend readings are mixed, with price trend neutral and AVWAP still negative. That fits a market that has acknowledged the growth but not yet paid up for it.
The bottom line is that Plexus delivered a convincing beat-and-raise, with record revenue, expanding margins, a higher long-term margin target, and a funnel that keeps growing. The open question is conversion. Growth has consumed far more working capital than management planned, and the first-quarter guide implies a pause in both sequential revenue and margin. If fiscal 2027 produces the promised $100 million-plus of free cash flow alongside mid-to-upper-teens growth, the flat share price will look like an oversight. If cash disappoints again, the improved sentiment may prove ahead of the fundamentals.
Read our earnings preview for Plexus Corp.: https://www.earningswhispers.com/article/PLXS/20977
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Aug-27 | |
| Aug-12 | |
| Aug-03 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| Jun-12 | |
| Jun-01 | |
| May-24 | |
| Apr-29 |
