NN Faces Proof-Of-Ramp Test As Data Center, Defense And Medical Wins Enter The Numbers
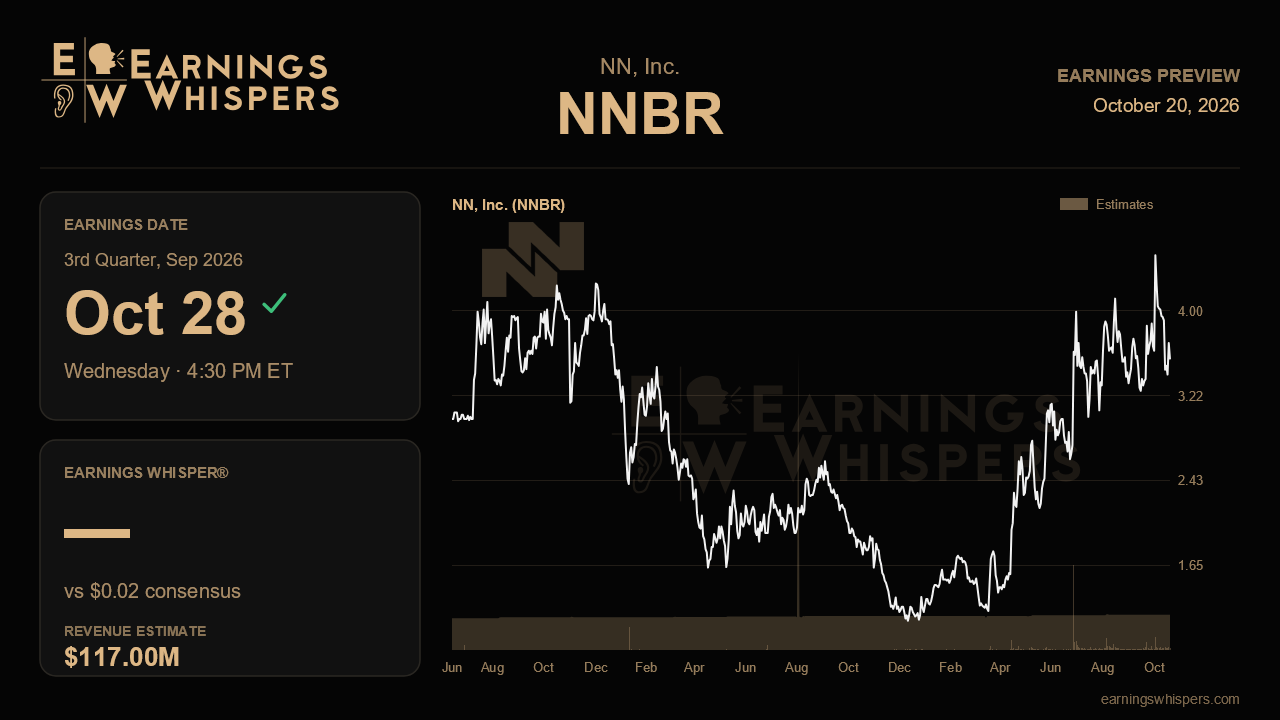
NN, Inc. heads into its third-quarter report with an unusual mismatch between narrative and stock price. Management spent the last call describing a company moving from turnaround to accelerating growth, then lifted its full-year sales outlook again afterward. Yet the shares have fallen about 16% since that report while the S&P 500 was essentially flat. The October 28 release, due after the close, is the first quarter in which the three marquee wins management touted in data center, defense and medical are supposed to begin showing up, which makes it a test of whether the story is arriving on schedule.
The Street is not asking for heroics. Consensus calls for earnings of $0.02 per share on revenue of $117.0 million. That revenue figure would represent healthy 12.6% growth from the $103.9 million posted a year ago, and the per-share number compares with a $0.01 loss in the same quarter last year. Sequentially, though, both figures step down noticeably from the second quarter's $128.7 million in sales and $0.11 in EPS. That dip deserves attention. If analysts are building in some seasonal softness or a slow start to the new programs, a revenue print that holds closer to second-quarter levels would be a meaningful signal that the ramps are contributing earlier than modeled.
Guidance frames the bar. NN now expects 2026 revenue of $470 million to $490 million, up from $460 million to $480 million, which itself followed earlier ranges of $450 million to $470 million and $445 million to $465 million. Full-year consensus of $474.2 million sits in the lower half of the newest range, so analysts have not fully embraced management's latest optimism. That leaves room for upside if the company reaffirms or nudges the range again, but repeated raises also mean a mere reiteration could feel flat. The company also lifted its adjusted EBITDA outlook to $55 million to $65 million last quarter and raised its long-term margin target to 14% to 16% after posting a 14% margin in the second quarter. Holding margins near that level on lower sequential revenue would go a long way toward validating that the improvement is structural rather than a one-quarter volume benefit.
The data center opportunity is the swing factor. Management described a pipeline approaching $100 million, 50 machines being installed for liquid cooling connector work, and sales expected to exceed $1 million a month starting in November, alongside a China build-out at Wuxi with room sought for roughly 200 more machines. Third-quarter revenue will not capture much of that, so the more useful evidence will be installation progress, confirmation of the November timing, and any update on new business wins, which stood at $80 million booked through July against a full-year target of $80 million to $100 million. Progress on the term-loan refinancing with Marathon also matters, since accelerating capital spending needs funding and the earlier preferred-for-stock swap pushed the share count to 82.6 million. Metals inflation and tariffs remain working-capital headwinds, though management said costs are passed through.
Sentiment has swung from modestly bearish before the last report to modestly bullish now, even as the stock retreated. At $3.70, shares remain well above the 200-day moving average of $2.61 but sit in the lower half of their post-earnings range of $3.19 to $4.79, suggesting the market wants proof before paying up again. The central question is simple: does NN show that its new programs are converting from announcements into revenue and margin on the timeline management promised? Clear evidence of that would support the accelerating-growth thesis, while slippage in the data center ramp or the refinancing would hand skeptics their argument.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-08 | |
| Oct-02 | |
| Sep-22 | |
| Sep-15 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-23 | |
| Jul-20 | |
| Jul-20 | |
| Jul-13 |
